Category: AZ Real Estate

  • Greater Phoenix Real Estate Update 9/10/2021

    A rising tide lifts all boats.

    Real estate creates wealth. It has created long-lasting, multi-generational wealth, and it has done the opposite. Why? Appreciation. Home price appreciation, overtime, benefits everyone.

    There is a lot of talk about softening, normalization, moderating, weakening, etc. They all mean the same thing; the real estate market is calming down. But before you exhale a sigh of relief, the market remains very, very hot.

    “We are seeing some signs of softening in the housing market, but context is important here… We’re still very much in a sellers’ market, but we are seeing some early signs of softening.”

    -ODETA KUSHI, DEPUTY CHIEF ECONOMIST, FIRST AMERICAN

    National Real Estate:

    The average American tenure in a home has increased substantially over the past 30 years and is now up to 10 years. A recent report stated that by 2037 we will be up to 15 years. At the rate we are going, we will reach that long before 2037. Less turn over = less available inventory = greater rate of appreciation (provided demand remains consistent).

    According to Fannie Mae’s August survey of homebuyer sentiment, consumers think it is a good time to sell a home but a bad time to buy a home due to high prices and low supply. Without the buyers, who do the sellers sell to?

    “The housing market has clearly become slightly more favorable to buyers. Homes are taking longer to sell, which gives buyers more time to make thoughtful decisions about whether to make offers. Home prices have plateaued, so buyers shouldn’t feel rushed to buy before prices rise further. And the fact that more sellers are dropping their list price is a sign that sellers have to be realistic about their price expectations.”

    -DARYL FAIRWEATHER, REDFIN’S CHIEF ECONOMIST

    While the market is normalizing, it is doing so from a very high level, so despite the recent declines in pending listings, we are still significantly above historic norms.

    Commercial real estate is also benefitting from the demand for real estate. In July, commercial property sales prices were up 1.2% month over month and 11.8% year over year. Unsurprisingly, multifamily has seen the highest rate of appreciation at 1.6% month over month and 13.5% year over year, the highest annual appreciation rate in 15 years.

    Prior to the pandemic, 60-75% of Zillow searches were for suburban homes, today it is 90%. At the same time, the number of suburban listings has declined 72% more than the urban listings.

    The AZ Market:

    Context truly is key. When the temperature cools from 514 degrees in March to yesterday’s 347, it is still super-duper hot (Cromford Market Index reference). The CMI measures the relationship between supply and demand and is the best leading indicator available. Anything over 100 is a seller’s market and prices rise at 110. Prices drop at 90. In order for prices to drop demand needs to be below supply. Demand is nearly 13% above balance while supply is 67% below balance.

    Despite the normalizing of the market, it is not normal. Demand has actually increased recently which is unusual because this is the time of year demand typically declines. After a 44% inventory increase over the past three months, inventory seems to be leveling out again and the increases have flattened. Leveling out at 7,400 listings is less than ideal. The size of the Greater Phoenix market calls for 25,000 listings and we haven’t seen 20,000 active listings since 2016.

    Jim Belfiore of Zonda is predicting that 35,000 new houses will be built in 2021, the most since 2007. There are 32,700 apartments in process but only 11,000 are expected to be completed this year. Apartment vacancy rates are close to 3% which is the lowest rate since the 1970s.

    iBuyers & Appreciation:

    In Q2 2021 iBuyers had a premium of 9.6% on their sales. Much of that gain was due to home price appreciation. This appreciation rate gave Opendoor and Zillow the confidence to move forward with extremely high offers, often significantly above market value. Acquisitions boomed and in July, iBuyers accounted for 8.1% of all home purchases in Maricopa County. This led to many flashy headlines about an upcoming giant Q3.

    The iBuyers must have missed my market update a couple of weeks ago when I wrote about the declining rate of appreciation. I wrote, “In January the Greater Phoenix median sales price was $340,000; now it is $405,000. That is over a 19% appreciation rate in this year alone. Most of those gains took place at the beginning of the year with 15.5% of the gain occurring from January to May. The median sales prices from May to August increased by 3.15% and from June to August the increase was 1.25%. The appreciation rate is slowing, and this is good for the overall health of the market.” You can find the full update here.

    On Wednesday, Mike DelPrete (with a little help from me) detailed how the changing home price appreciation rates are impacting iBuyer premiums in a big way. He wrote, “Home price appreciation rates are beginning to cool in major markets across the U.S., including Phoenix, where the median iBuyer home price appreciation has fallen 50 percent since May. Opendoor’s median home price appreciation for homes sold in August is just 2.7 percent, down a massive 75 percent from 10.7 percent in May.” Click here for his article and supporting graphs.

    Lending:

    The average mortgage borrower has $173,000 in equity which means that Americans as a whole have $9.1 TRILLION in equity, a record high. Cash-out refinances are increasing, interest rates are low and it makes a great headline. Keep in mind, while the refis are up, they are not near record highs and borrowers today have nearly double the amount of equity they had in 2005.

    Real Estate News:

    • Offerpad went public last week via merger with former Zillow CEO Spencer Rascoff’s SPAC. It launched with a $2.7 billion valuation and in recent days increased by 27% to its goal of $10 per share.
    • A Federal Judge denied NAR and Zillow’s motion to dismiss discount brokerage REX’s lawsuit stating that NAR’s “no-commingling rule” violates antitrust laws. NAR’s current rule states that MLS listed properties and non-MLS listed properties may not be “co-mingled” in the same section on a listing platform, like Zillow.
    • Opendoor recently acquired two home renovation companies, Skylight and Pro.com.
    • California Regional MLS, the nation’s largest MLS, is updating its requirements for the listing agent disclosure on online listing pages. Now, on all online CMLS listings the listing agent, contact info, and brokerage are required. Will this spread across the country?

    Final Thoughts:

    Today’s low levels of inventory created huge leaps in appreciation. As that calms, skittish buyers will return to the market and more sellers will list their homes. It will be a long time before we see 25,000 listings, but maybe we could get up to 10,000 in Q1 2022, and what a market that will be!

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 9/3/2021

    Inventory levels are up but not enough. Home price appreciation is starting to slow but not by very much. Mortgage rates remain low, but did everyone refinance last year? Conditions are improving but the market isn’t healthy, yet, but it is on its way. Remember when 8% appreciation was a lot? 2018 and 2019 each had 8% appreciation. That feels like a lifetime ago.

    Slow and steady wins the race. Gradual shifts are manageable, they sometimes even go unnoticed. Slow and steady does not create a bubble. Slow and steady does not lead to a crash. Slow and steady is boring and sometimes boring is good.

    National Real Estate:

    For the second month in a row, NAR’s Pending Home Sales Report declined. In July it dropped 1.8% from June and is down 8.5% year over year. The west was the only region to see a month over month increase but remained 5.7% below July 2020. Expect all year over year data to be negative through the end of the year as our market normalizes, 2020 was an anomaly.

    The median single family home sales price declined slightly since July when it reached $399,900, the year over year appreciation rate is declining. At $389,000; single family homes are up 10% year over year.

    The Case-Shiller National Home Price Index was released this week stating that home prices are up 18.6% year over year; that is true but the report is looking at June’s sales, not last week’s. Case-Shiller is used by Wall Street analysts and the federal government. It is very accurate and useful for industries and businesses that do not need to focus on the most timely data. For the 25th month in a row, Phoenix took the top spot for year over year appreciation at 29.3%. I expect that in the coming months this figure will decline some but will remain ahead of the rest of the country.

    “While the housing market feels like it has legs that never get tired, inventory and affordability constraints are still expected to put a damper on price growth. Some early data suggests that the buyer frenzy experienced this spring is tapering, though many buyers still remain in the market. Nevertheless, less competition and more for-sale homes suggest we may be seeing the peak of home price acceleration. Going forward, home price growth may ease off but stay in the double digits through year-end.”

    -Selma Hepp, CoreLogic Deputy Chief Economist.

    The FHFA also released its report showing that in Q2 2021 home sales prices increased 17.4% year over year. Q2 ended in June and today’s market is healthier than the June market.

    The top 10 markets for investors in 2020 (not in order) were Corpus Christi TX, Boise ID, Kansas City MO, Atlanta GA, Memphis TN, Salt Lake City UT, Wichita KS, Provo UT, Phoenix AZ, Springfield MO.

    For every accepted offer in July, there were 3.5 more offers written. In March it was not usual for sellers to receive 40, 50, 60+ offers on one listing.

    29% of new home inventory has yet to break ground.

    Last week was the first week in 16 weeks that single family inventory did not increase. It remained flat week over week at about 431,000 which is a 40% increase from the bottom we hit on April 30 at 307,000. Despite the significant increase, inventory remains tight. Experts are not sure if this is a blip or if inventory is leveling out far lower than expected. This is also the case for Greater Phoenix, since April 30 our inventory is up 52%, and in the past three weeks our inventory if up by just over 2%.

    The AZ Market:

    Despite all of the new apartment buildings coming, experts say that we are not at risk of overbuilding. Vacancy rates are down to 4.1%, a year ago they were at 5.7%. Lack of supply has driven apartment prices up 18% year over year. Between the completed projects and forecasted ones, it is expected that Greater Phoenix will have an apartment increase of 17,563 units in 2021. That is more than the annual amount each of the past three years.

    New home sales are down 31% from May and 37% year over year. They are also down 15% from August 2019 to August 2021. Low inventory, high prices due to labor and material shortages are to blame. The median new home sales price is up 29% year over year in August to $440,000.

    The Federal Reserve:

    While the Fed has stated that it will likely begin tapering its bond and mortgage backed security purchases as early as this year, a few things have to happen first. 1.) inflation stabilization and decline 2.) low unemployment 3.) declining COVID rates. Once those happen and the Fed will announce the start of the tapering, expect rates to jump as much as half to one percent. Rates are being artificially held down by the MBS purchases.

    Prior to 2008, the Fed’s balance sheet was less than $1 trillion. With the quantitative easing during the Great Recession, the balance sheet jumped to $4.5 trillion. Now, after 18 months of bond and MBS purchasing the balance sheet is around $8.3 trillion.

    Real Estate News:

    • The Biden Administration plans to help non-profits and owner-occupied buyers purchase GSE backed foreclosures before corporate investors have the opportunity to come in and purchase the properties.
    • Opendoor is now offering a self-guided, virtual home inspection for sellers. Owners who sell to Opendoor will have the option to do a 30 minute virtual walk through with an Opendoor representative or have the more formal two to four hour home inspection. Opendoor will still do an in-person exterior inspection.
    • In 2019, 53% of Americans wanted a bigger home, today that number has risen to 60%. This is true regardless of age, race, and education.
    • According to a report Zillow released on Wednesday, the average 2021 homebuyer is 45 years old, has a significant other, graduated from college, and will likely purchase a home in the south. Some other fun facts from the report:
      • The biggest group of buyers at 26% are aged 30-39.
      • 40% of buyers have kids under 18 living with them.
      • 44% bought in the suburbs, 38% in cities, and 19% in rural areas.
      • 50% have at least one dog and 39% have at least one cat.
      • 37% were first time home buyers, down from 43% in 2020.

    Final Thoughts:

    There was not a lot of exciting news this week and that is ok. Slow and steady wins the race.

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 8/27/2021

    Residential real estate pulled our economy out of the shortest recession in history. As last year’s market frenzy cools, the severe imbalance of supply and demand lessens and prices continue to increase, just at a slower rate. According to the 2020 US Census, housing units increased by 6.7% while population grew by 7.4%; both were declines from previous decades, but it doesn’t change the fact that demand (population) outpaced supply (housing units). Over the past 10 years, Maricopa County’s population increased by 15.8% and housing units increased by 8.3%.

    Demand outpacing supply combined with 10 million job openings and only 5.7 million jobs left to recover; residential real estate has garnered significant attention from investors. When an asset class or sector underperforms, investments are redirected into performing asset classes/sectors. Investors do their homework and invest where money will likely grow the most. Year over year rental rates are up along with property appreciation. John Burns of John Burns Real Estate Consulting said, “Investors won’t be slowing down at all. They’re only accelerating.”

    And don’t worry about the coming year over year negative reports. 2020 was an anomaly and is not a good comparison for a normalizing market.

    Rentals & the Eviction Ban:

    Yesterday the Supreme Court lifted the CDC’s eviction ban, stating that the CDC did not have the authority to create the ban in the first place, ending it six weeks earlier than the planned October 3 end date. In June, the Supreme Court ruled that the only way to further extend the eviction ban was through an act of Congress, which did not happen. Through the end of July, only $5.1 billion of the $46.5 billion in rental relief funds had been distributed.

    According to a new report from Zillow, nationwide rent prices were up 9% in July, year over year. Greater Phoenix saw the largest year over year rent increase, at 23%.

    In 33 of the 50 largest American cities, the typical rent is higher than the typical monthly mortgage payment. This is true in Greater Phoenix.

    National Real Estate:

    On Monday, NAR released its existing home sales report for July. Some interesting data points:

    • Total inventory is up 7.3% from June to 2.6 months of supply but down 12% from July 2020 when it was 3.1 months.
    • Nearly 90% of total sales in July were listed for less than a month.
    • 23% of sales were all cash, up from 16% in July 2020.
    • 30% of July sales went to first time homebuyers, down from 31% in June and from 34% in July 2020.

    “We see inventory beginning to tick up, which will lessen the intensity of multiple offers. Much of the home sales growth is still occurring in the upper-end markets, while the mid- to lower-tier areas aren’t seeing as much growth because there are still too few starter homes available.”

    – Dr. Lawrence Yun, NAR’s chief economist

    Total inventory (including both new and existing) peaked in 2008 then started declining. The declines have been consistent since 2014. While inventory has been rising since February and the market started showing signs of seasonality, which is good, we do not want to see inventory drop again, as it usually does in the fourth quarter. If demand remains the same and inventory declines then we see a faster rate of appreciation, which at its current levels, is unsustainable and has only just started to slow.

    Available Inventory

    The AZ Market:

    In January the Greater Phoenix median sales price was $340,000; now it is $405,000. That is over a 19% appreciation rate in this year alone. Most of those gains took place at the beginning of the year with 15.5% of the gain occurring from January to May. The median sales prices from May to August increased by 3.15% and from June to August the increase was 1.25%. The appreciation rate is slowing, and this is good for the overall health of the market.

    There are 62% more active listings with an asking price over $400,000 than under.

    In July, iBuyers accounted for 8.1% of all home sales in Maricopa County.

    In Q2 2021, 17 houses sold for at least $1,000,000 over the initial list price, up from 8 in Q1 2021. Fifty houses sold for at least $500,000 over the initial list price in Q2 2021, up from 15 in Q1 2021.

    85224 in Chandler is the only Arizona zip code to make it in the top 50 in Realtor.com’s 2021 Hottest Zip Codes in America list.

    Greater Phoenix, through July, has recovered 99% of jobs lost due to the pandemic and only needs 2,500 more jobs to match February 2020’s employment rate. Arizona has recovered 93.7% of jobs lost.

    According to the 2020 Census, at an 11.2% increase, Phoenix grew faster than any other major city over the past 10 years and passed Philadelphia as the nation’s fifth largest city. Buckeye took the top spot for fastest growing city in the country, among cities with at least 50,000. It grew by 80%!

    For more on the Greater Phoenix market, click here for my update from last week which is exclusively about our local market.

    New Construction:

    Lumber prices are down from the peak in May at $1,515 per 1,000 board feet to $472 per 1,000 board feet in early August. Due to the backlogs, it is unlikely that new home buyers will feel the pricing relief anytime soon.

    Month over month builder confidence declined by 5 points in August to 75, the lowest reading in 13 months. The decline is attributed to high material costs and labor shortages. Any reading over 50 is considered a good market. In April 2020 the index dropped to 30.

    “There are now almost 690,000 single-family homes under construction – the largest number since 2007. This is clearly a positive sign given the remarkably low levels of inventory on the market.”

    – Mike Fratantoni, the MBA’s chief economist

    After three months of declines, new home sales in July increased by 1% from June, beating expectations. June’s sales numbers were revised up. New home inventory is up 5.5% to a three-month average of 5.9 months. Builders tend to pull back once they hit 6.5 months.

    Commercial Real Estate:

    Much of commercial real estate has recovered from the pandemic and is now beating out February 2020 prices. The Green Street Commercial Property Price Index, which is based on REIT net asset values, beat February 2020’s ranking by 1.3%. In July, prices were up 14% year over year and up 2.4% from June.

    With prices growing over 20%; mobile home parks, self-storage, and industrial grew the fastest. In Greater Phoenix, the industrial vacancy rate is down to 4.7%. However, some asset classes are still down. The year over year prices for retail and lodging are down 7%, office is down 8%, and mall values are down by 18%. In Greater Phoenix, the office vacancy rate has increased for five consecutive months and the vacancy rate is up to 19.7%.

    Real Estate News:

    • Offerpad is the first iBuyer to turn a profit. In Q2 2021 they brought in $9.2M in profit. Based on the overly inflated offers from Opendoor and Zillow, it is likely the only iBuyer that will be profitable for some time.

    Final Thoughts:

    Danielle Hale the chief economist for Realtor.com summed it up well when she said, “Continued economic recovery is key to maintaining (real estate) sales momentum, and anything that disrupts progress, such as rising COVID cases, could knock home sales off course. We’ve already seen a pullback in builder confidence and mixed construction data as builders balance buyer interest with supply challenges, rising costs, and concerns about the future of the economy and housing affordability. Still, with listing price growth beginning to recalibrate in response to shifting supply and demand dynamics, we should see a steady pace of home sales over the next few months, especially if mortgage rates remain low.”

    Copyright 2021 Sarah Perkins

  • AZ Forbearance Update 8/25/2021

    In this 13 minute video, Lydia Wietsma and I discuss the latest in forbearance, delinquencies, jobs, BPOs, and inspections. We have had a lot of positive news lately which helps both homeowners and buyers.

    Employment:

    In Greater Phoenix, through July, has recovered 99% of jobs lost due to the pandemic and only needs 2,500 more jobs to match February 2020’s employment rate. Arizona has recovered 93.7% of the jobs lost.

    Housing:

    Housing inventory is slowly increasing, giving more options to our exhausted buyers. With the inventory gains, appreciation has started to slow which is also good for the overall health of the market.

    Delinquencies:

    Delinquency rates continue to decline as more and more renters and borrowers are getting caught back up on their payments. The 30-day delinquency rate and 60-day delinquency rates are at the lowest levels in the history of the Mortgage Bankers Survey. The 90+ day delinquency rate remains elevated above pre-pandemic levels.

    Deadlines:

    Forbearance: If your loan is backed by HUD/FHA, USDA, or VA, the deadline for requesting an initial forbearance is September 30th, 2021.

    If your loan is backed by Fannie Mae or Freddie Mac, there is not currently a deadline for requesting an initial forbearance.

    Click here to find your servicer or to see who backs your loan.

    Foreclosures: The foreclosure ban has been lifted. The CFPB has specific criteria that a lender or servicer must abide by when going through the foreclosure process. This will delay many, but not all foreclosure proceedings until the end of the year. For more information click here.

    Evictions: The CDC extended the eviction ban which covers about 90% of renters through October 3. This is hotly debated with strong opinions on both sides. Despite calls that the ban is unconstitutional experts recommend against moving forward with any evictions until the ban is lifted. The FHFA has banned evictions on all of its foreclosed properties with renters living in them.

    Click here and here for renter advocacy information.

    Forbearance Numbers:

    Since our last video, the number of borrowers in forbearance declined by 100,000. We are now down to 3.26% of borrowers or 1.6 million borrowers are in a forbearance plan. Despite the low number in a plan, this was the slowest decline in over a year.

    Forbearance by Stage:

    • 10% of total loans in forbearance are in the initial stage.
    • 82.3% are on extension.
    • 7.7% are re-entries.

    Forbearance Exits from June 1, 2020 through August 15, 2021:

    42.7% of borrowers continued making their payments (22.6%), got caught up upon exiting (13.1%), or paid off the loan with a refinance or sale (7.4%).

    The percentage of exits for the group to be most concerned about, borrowers who exited their forbearance plan still behind and without a loss mitigation plan in place increased to 16.1% from 15.7% two weeks ago.

    Inspections & BPOs:

    Requests have slowed down and scaled back to normal levels. The tax lien notices have declined significantly.

    Most of her BPOs lately have been for fourplexes. They seem to all be investors who are needing to sell. We are seeing elevated investor transactions both for corporate buy and hold or iBuyers.

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 8/20/2021

    Today is all about the AZ market. Yesterday, Lawyers Title hosted a presentation with Tina Tamboer with the Cromford Report. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.

    Supply & Demand:

    Supply is all of the properties; demand is all of the humans.

    The relationship between supply and demand dictates pricing in all sectors. There are influences that solely impact supply or demand, but those influences do not directly change sales prices. Mortgage interest rates influence demand and buyer behavior, but it does not impact supply.

    The wild card currently impacting pricing comes from the corporate investors and iBuyers who are paying well over market value for many properties.

    When affordability declines demand usually declines. Greater Phoenix’s affordability is down in Q2 2021, yet demand is increasing.

    Pricing:

    For nearly 2.5 months the median sales price has been right around $400,000. As you can see below, monthly payments did not increase much as prices increased because of the declining interest rates. It wasn’t until this spring that we saw a spike in monthly payments. The monthly mortgage payment for the median house is $1,859. Up nearly 23% from November 2020 when it was $1,518.

    There is even less relief for renters. To rent the same median property, renters are now spending $2,195 a month.

    Affordability:

    As many suspected, affordability declined in Q2 2021 and the US as a whole and Greater Phoenix fell below the ideal affordable range of 60-75 for the first time since late 2018. Through Q2 2021 in Greater Phoenix a household earning the median income ($79,000 annually), can afford 56.4% of what is for sale. A year ago, it was 70%.

    The low interest rates have worked in our favor for a long time. When rates increased up to 5% at the end of 2018, we dipped below the ideal affordability range and demand declined. When affordability drops below 60, we begin to see demand resistance.

    iBuyers:

    The affordability trends will impact corporate investors and iBuyers. Demand declines when things are not affordable, and it can shift quickly. In 2005 affordability went from 75 to 27. If not enough people can afford what is on the market, properties will sit for longer, and price reductions increase.

    iBuyer acquisitions are up 573%, their inventory is up 544%, and their sales are up 93% year over year. Both Opendoor and Zillow had their largest acquisition month ever in July. Offerpad is not as aggressive as the others (which could be why Offerpad was profitable for the first time ever in Q2 2021 and both Opendoor and Zillow Homes lost money).

    iBuyer offers are excessively high, sometimes bidding against their own offers. According to a recent report from Mike DelPrete, Opendoor paid 7.7% above market value on its acquisitions in Q2 2021 nationally. Tina mentioned instances of offers over $75,000 above market value. Other people’s money is very easy to spend.

    A year ago, owner-occupants drove the housing market. People were buying houses to live in. Today much of the demand is led by iBuyers and investors, both large and small. Since June 23% of Opendoor’s sales, 19% of Zillow’s sales, and 11% of Offerpad’s sales have gone to corporate investors.

    Overinflating values and creating false demand is extremely unhealthy for a market. This is not what the market is supposed to do. The iBuyers will either have to wait for the market to catch up or sell for a loss. The 3.1% monthly appreciation rate from the spring has slowed and is expected to slow further, likely down to 0.5% or 1% a month by the end of the year.

    Forbearance:

    Forbearance numbers are only available on a national level and continue to improve. As of Monday, there are about 1.6 million borrowers in a forbearance plan, a huge decline from the over 8 million in a plan last May.

    The majority of borrowers exiting forbearance are staying in their home, with no flood of foreclosures coming. Estimates could go as high as about 20% of borrowers will need to sell at the end of their forbearance plan. 20% of 1.6 million is 320,000. If we divide that by the 50 states, then each state (if divided evenly) would see about 6,400 foreclosures.

    For a deeper dive into forbearance, foreclosures, and delinquencies check out my latest Forbearance Update here.

    Supply: 

    Shelter is a basic human need. Over the past 10 years our population grew by 20% and total inventory grew by 11%. We have more demand than we have houses.

    Single family permits are up 39.7%. And builders are struggling to keep up with the demand due to supply chain shortages and labor shortages. It is now taking 10-14 months to build a house.

    Supply stopped dropping in February. It is up 61% since February and up 44.3% since May. There was an initial shift in February and then a bigger shift in May as prices continued rising.

    Supply Increases by Price:

    • $300K – $400K up 62.4% since February and up 47.6% since May
    • $400K – $500K up 187% since February and up 99.7% since May
    • $500K – $600K up 171% since March and up 76.9% since May
    • $600K – $800K up 149% since February and up 64.5% since May
    • $800K – $1M up 100% since February and up 38.5% since June
    • $1M – $1.5M up 50.9% since February
    • $2M – $3M down 5.3% since March
    • $3M+ is up 2.1% since March

    Price Reductions:

    With the increase in supply, we are seeing an increase in price reductions. We often hear about sellers upset that they had to drop their price when their friend received multiple offers over asking only a few months ago. It was a different market in March and today’s sellers cannot expect the same.

    May 9 was the turning point and appreciation began moderating. In a normal market, you can expect to see about 400-500 reductions per week. In 2018 we hit 600. Now we are hitting about 200, still low but increasing. Not unusual, just unusual for the past year. Sellers can no longer push the market.

    A price drop of $5,000 used to be the norm. Two weeks ago it was $15,000 per reduction, a week ago it was $14,000, and now it is down to $10,000.

    In April the median days on market was 6. We are now up to 8 days.

    Demand:

    We have been hanging around normal demand for the past few months. Then last week demand increased. Where did that come from? Investors? iBuyers? The increased demand will keep us in a seller’s market longer. Increased supply decreases the strength of the seller’s market and increased demand increases the strength of a seller’s market.

    ibuyers have no effect on supply since they buy and sell. They impact demand. Show an extra transaction that can inflate demand metrics because they never have an occupant in the property.

    2019 had slightly above normal demand. Today there are 6.2% more listings under contract than in 2019 but 12.9% lower than in at this time last year.

    Typically demand decreases in Q3 and Q4. We should see inventory gains and fewer buyers. Many listings will likely be over-priced, and buyers will not pay over asking when they have a lot of options.

    We are still having a record year for luxury, amazingly high demand remains, usually this late in the year, luxury slows down as owners pull their unsold properties off the market by about June.

    Cromford Market Index (CMI):

    The best tool for predicting future price appreciation trends and is available on the main page of the Cromford Report: https://cromfordreport.com/ (without a subscription)

    • 100 is balanced and prices rise at the rate of inflation (currently 5.4%), below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110. 2014 was a balanced market.
    • On 3/20/2020 we were at 241
    • On 5/15/2020 we were at 145.2
    • Yesterday we were at 349.7
    • We peaked on 3/14/2021 at 514.9
    • Prior to this run, the previous peak was 312.9 in the spring of 2005.
    • CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI. It tells us where we are.

    When the CMI weakens we see other weakening follow, like sales prices, appreciation, over asking, etc. We are now averaging a decline of 29.3 points over 30 days. Previously it was dropping 50 points over 30 days. It is slowing due to the increased demand.

    While the CMI will probably not move in a straight line, we are moving towards a weaker seller’s market. Tina expects we may level out around 200-240. It will feel like a buyer’s market but it won’t be. Likely will get to the 2019 numbers.

    As the seller’s market weakens, people will get very nervous about a market crash and declining property values. Remember demand needs to be lower than supply for prices to drop. With supply 69% below normal and demand nearly 9% above normal, it will take a long time for demand to be lower than supply. Before the 2008 crash there were 57,000 active listings. Today there are fewer than 7,100 active listings.

    Using 4 week averages and tons of past data, we can draw a trendline from the CMI, illustrating when we might reach a balanced market. No reason to believe that this will stay in a basic trendline. It will adjust and probably stay in the 200-240 range. It is only what we know today. Since each city is so different, it is best to check each one weekly. To show the variation between cities, these are the timelines in which they could reach balance:

    • Phoenix 7.3 months
    • Chandler 3.6 months
    • Glendale 3.8 months
    • Mesa 5.8 months
    • Gilbert 5.6 months

    Appreciation:

    CMI moves first and then appreciation follows, usually about 3-6 months later. In a seller’s market, the rate of appreciation is higher than the rate of inflation. The luxury market is pushing appreciation rates up even higher.

    Appreciation rates are slowing. It has gone from a year over year increase of 39.3% in May to 28.4% in August.

    For over a year we had a monthly appreciation rate of 3.1% but in the past few months, it has slowed considerably. Today it is at a 1.4% increase and will likely continue to slow throughout the rest of the year.

    Contract Ratio

    The contract ratio compares how many listings are on the market to how many are in escrow. Has it cooled off? Yes. Cold? No. In April it reached 332.5 and today it is 161.2. We are in a hot seller’s market but not an extreme seller’s market. In 2019 was 76. 75-80 is normal for August.

    Before the pandemic, the market was in a frenzy. We didn’t have enough supply and still don’t. In March we had 10 levels of insanity illustrating the seller’s market. Today we have 5. It is cooling but is not cold. We have been in a weakening seller’s market since March. It is only now getting noticed.

    54% of listings are selling for over asking. Two months ago the median amount over asking was $25,000 it has since dropped to $15,000. Now sales are averaging about 1% over asking versus the 1.8% it reached in the spring. Expect this to come down throughout the rest of the year.

    Final Thoughts:

    Overall, the market is still very busy. We are on the cusp of weaker seller’s market. We are seeing fewer purchases from regular owners and more from investors and ibuyers. It is still a good time to buy. BUT we need to watch the affordability levels. It is not about whether the buyer can afford it now but about how many future buyers can afford to buy it from today’s buyer?

  • Greater Phoenix Real Estate Update 8/13/2021

    It’s earnings season so the headlines are dominated by big business quarterly revenue numbers. Wall Street and residential real estate have a bumpy history.

    In late 2008 when the Greater Phoenix real estate market’s heart stopped beating and everything went eerily quiet, I didn’t understand what happened. Like many, I wondered, how could everything stop seemingly overnight? I asked, “where did all of the money go?” And I was told, “it never existed in the first place.” I learned that money did not just evaporate on Wall Street and that housing could take down Wall Street, or was it the other way around?

    In 2011 the market bottomed with a median sales price of $107,000 in greater Phoenix. Since 2014 we have been in a seller’s market and the recovery was slow. For a time, real estate felt local again. But was it?

    Venture Capital Funding:

    In 2015, young company, Opendoor, entered its first market, Phoenix. The company pioneered the iBuying concept and was backed by Softbank’s Vision Fund, one of the biggest funds in the world, allowing Opendoor to remain after continued losses. Seven years later the company still has not turned a profit but has billions more to keep trying, especially since going public last year. Big venture capital money continues its quest to disrupt real estate. Opendoor’s situation is not unique, the industry is ripe with unprofitable giants backed by big money. The chart below illustrates the magnitude of venture capital money in real estate, not limited to Opendoor.

    Credit: Mike DelPrete’s 2021 Emerging Models Report

    Valuations:

    Establishing valuations is complicated and the businesses with the highest valuation does not mean that they are the most profitable. Click here for more info on establishing valuations. Earnings alone only tell most of the story. As accurate pricing is established by both supply and demand, profitability is established by dollars brought in and dollars spent. The only way to be profitable is for a company to spend less than it makes.

    For example, eXp’s year over year Q2 2021 $1 billion in revenue led to an earnings increase of a whopping 183%. That combined with an 87% increase in agent count illustrates future growth potential and explains why eXp’s valuation has skyrocketed. eXp’s profit was $37 million or 3.7%.

    Meanwhile, RE/MAX’s revenue grew by 48%, bringing in $76.05 million for a profit of $5.2 million or 6.8%. RE/MAX has consistently been profitable for years, yet its valuation has remained stable.

    Earnings:

    Q2 2021 year over year earnings look extremely impressive given that the post lockdown real estate recovery started in May 2020.

    The AZ Market:

    Join us next Thursday 8/19 as Tina Tamboer with the Cromford Report does a 1 hour deep dive into the greater Phoenix housing market. For details and registration click here.

    Q2 2021 was one of the biggest multifamily construction quarters on record, there were 623,500 units under construction in the 150 largest apartment markets nationwide. In greater Phoenix there were 28,600 multifamily units under construction, increasing our multifamily base by 7.6%.

    These numbers are high but warranted. Nationwide apartment rents are up 8.3% year over year and occupancy is at a record high at 96.9%. Greater Phoenix continues to top the charts in year over year rents growth at 21.6%.

    Policy:

    The CDC extended the eviction ban through October 3 with slightly different criteria, covering about 90% of renters. In May, the Supreme Court ruled that the only way to extend eviction protections is with Congress’ approval. President Biden officially made that request to Congress while it is in recess, the only way for it pass is through a unanimous call-in vote. Furthermore, when the Supreme Court made its ruling it stated that it agreed with the plaintiffs in that the Supreme Court did not believe that the CDC had the authority to extend the ban in the first place. Of the $46 billion allocated for emergency rental relief, only $3 billion has been disbursed.

    On July 31, the foreclosure moratorium expired. The CFPB implemented specific rules in which lenders must abide by when foreclosing which will further delay most foreclosures. Abandoned properties will be foreclosed on first. There will be some foreclosures but not a flood. For greater detail on this and forbearance, please check out my AZ Forbearance Update from Wednesday, here. One major factor at play is the historic levels of equity most homeowners have.

    New iBuyer:

    Rocket Homes, a subsidiary of Rocket Companies which owns Rocket Mortgage, the country’s largest lender, is hiring employee real estate agents and is planning a “soon to be released iBuyer program” that will be managed through a third-party partner company.

    Rocket Homes, a licensed brokerage, which is already licensed in all 50 states (has been licensed in AZ since 2018) said that beginning in the fourth quarter of 2021, employee agents working from downtown Detroit will provide services to sellers at a discounted commission rate of 1.5% (the co-broke offered is unclear). The remote employee agents will advise on listing price, handle photos, enter listings in the local MLS, negotiate offers, and handle paperwork. Sellers who would prefer to work with an agent in their market will be referred to the Rocket Homes Verified Partner Agent Network. Sellers who don’t want to work with an agent at all can use Rocket’s ForSaleByOwner.com platform for free.

    Real Estate News:

    • A new Connecticut law is now regulating what Realtor teams may call themselves. They can use “team” but not “group” or “LLC” and also requires a $565 initial registration with an annual fee of $375. This is an awfully complicated way to increase state revenue. Will it catch on?
    • Citigroup, JP Morgan Chase, and other banks are offering a new high risk, high reward bond product and investors want in. While they are a very small part of the market, banks are selling riskier products that packages mortgages, car loans, and corporate debt. Investors are responsible for the losses when borrowers default on the loans packaged in the bonds.

    Final Thoughts:

    Long before residential real estate pulled us out of the shortest recession in history, Wall Street and Silicon Valley were plotting ways to infiltrate housing. While big money and new technology provide powerful incentives, it is very difficult to replace a well-informed, well-connected, local real estate professional.

    Copyright 2021 Sarah Perkins

  • AZ Forbearance Update 8/11/2021

    In this 15 minute video, Lydia Wietsma and I discuss the latest in policy, forbearance, foreclosures, and inspections.

    Policy:

    There is a lot of confusion with all of the info coming out of Washington DC. There are proposals, bills, executive orders, extensions, approvals, and appointments announced every day. The Biden administration is proposing a lot of bills that impact housing.

    Here is a brief update on several of the policies coming out of DC:

    • The $1 trillion proposed infrastructure bill passed the Senate and is now in the House for negotiations.
    • A new $3.5 trillion social infrastructure bill has been proposed in the Senate which includes down payment assistance options along with other housing aid.
    • Eviction ban was extended through 10/3. This extension has created quite a buzz among the real estate industry. I expect many more lawsuits in the coming weeks.

    Lifted Foreclosure Ban:

    This did not create a foreclosure frenzy as the CFPB implemented a strict foreclosure process for lenders and servicers. It is likely that we will not see many foreclosures until later in the year after borrowers have exhausted their loss mitigation options.

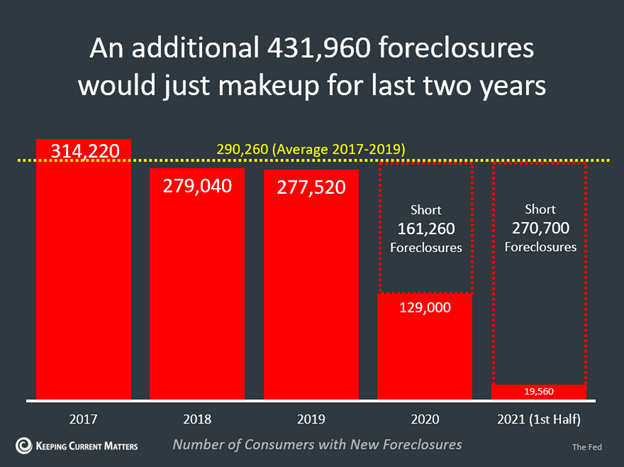
    Keep in mind that in any year there are foreclosures. The ban that lasted nearly 18 months created a backlog that will have to be worked through. From 2017-2019 there was an average of just over 290,000 foreclosures nationwide which gives us a shortage of about 432,000 foreclosures.

    Given that nationally homes have appreciated about 17% year over year and here locally about 27% year over year, most borrowers in foreclosure will be able to do a normal sale rather than having to go through foreclosure.

    Nationwide, it is estimated that about 4% of borrowers are upside down on their homes by 25% or more. This number has decreased from 6% last year.

    The report went on to say, “Equity gains in Arizona were particularly extreme. In the first quarter of the year, 16 percent of mortgaged homes in this state were considered equity-rich by Attom’s definition. In the second quarter of 2021, that number rose to nearly 40 percent.”

    Forbearance Numbers:

    The total number of loans in forbearance continues to decline. We are down to 3.4% of loans which is about 1.7 million borrowers.

    Forbearance by Stage:

    • 9.7% of total loans in forbearance are in the initial forbearance plan stage.
    • 82.9% are in a forbearance plan extension.
    • 7.4% are forbearance re-entries.

    Forbearance Exits from June 1, 2020 through August 1, 2021

    43.7% of borrowers continued making their payments (22.9%), got caught up upon exiting (13.3%), or paid off the loan with a refinance or sale (7.5%).

    The percentage of exits for the group to be most concerned about, borrowers who exited their forbearance plan still behind and without a loss mitigation plan in place remained flat at 15.7%.

    Future Forbearance Exits:

    According to Black Knight data services, next month is anticipated to have the largest number of forbearance plan exits this year.

    Missed Payments:

    While mortgage delinquencies are easier to track, missed rental payments are not. Based on my research, I think the MBA’s recent update stating that Q2 2021 saw a big improvement in missed housing payments and the total number for both borrowers and renters is below 5 million nationwide is fairly accurate. The data shows that there are about 2.86 million rental households behind on their payments and 2.19 million borrowers behind on their mortgage payments.

    Servicers & Inspections:

    Inspections are way up. Many more for corporate buyers, not just iBuyers but also buy and rent companies also. The servicers have gone quiet on the future of foreclosures but continue to prepare for the coming months of uncertainty.

    Be mindful of the information out there. Be sure that it is current and from a reputable source. And remind borrowers and renters there are still options available. Discuss exit strategies.

    Options:

    Forbearance and foreclosure assistance: https://www.consumerfinance.gov/coronavirus/mortgage-and-housing-assistance/help-for-homeowners/avoid-foreclosure/

    AZ Eviction Help: https://azevictionhelp.org/

  • Greater Phoenix Real Estate Update 7/30/2021

    In the past, the Phoenix housing market tended to run about 8-12 months ahead of the rest of the country. Over the past 18 months, our market has pretty much been on pace with the rest of the country until very recently. I would say that our market is running about a month ahead of the rest of the country so be mindful of national headlines, it is old news in Phoenix.

    Economy:

    The economy is in growth mode and many economists expect huge employment growth in September when the additional $300 a week in pandemic unemployment benefits expire. There are two scenarios in which economists forecast a growth reversal and push us into recession. The first is if the increased COVID cases shuts down the economy again. The second is the Federal Reserve tapering its $120 billion in monthly bond and mortgage-backed security purchases too quickly because if they do, interest rates will spike. The Fed met this week and are keeping rates as is. They are also not planning on beginning to taper their purchases until late in 2022. Given that the Federal government is the nation’s largest borrower, the Fed is not in any hurry to raise rates.

    Hopefully, the consumer inflation truly is transitory and settles down by the end of the year. It is the asset inflation that is impacting the economy. We have seen exponential asset inflation over the past 10 years. Economists, Wall Street, and Washington DC call it inflation. We call it appreciation. Houses in Greater Phoenix have appreciated 274% since 2011 when our median sales price bottomed out at $107,000. Today the median sales price is $400,000 which gives us a year-over-year appreciation rate of 27%.

    The AZ Market:

    On Wednesday I pulled the top 5 zip codes for year over year appreciation and was surprised that despite our nearly non-existent sub $300,000 inventory, it was not the lower-priced zip codes with the greatest appreciation rates. Only one zip code has a median sales price even close to the overall median. Luxury took the top spot.


    The top 5 zip codes for year over year appreciation:

    1.) 85253 at 49.8% with a median sales price of $2,397,500 (Paradise Valley)

    2.) 85260 at 43.8% with a median sales price of $575,000 (Scottsdale)

    3.) 85297 at 41.9% with a median sales price of $518,750 (Gilbert)

    4.) 85022 at 41% with a median sales price of $375,000 (Phoenix)

    5.) 85262 at 40.3% with a median sales price of $1,175,000 (Scottsdale)


    This huge appreciation is not like the 2005 bubble. Today’s appreciation is based on low levels of supply. In 2005 it was the high levels of demand, and of course a bunch of other stuff. We did have pent up demand due to the lockdowns in Q2 2020 which caused the frenzied purchasing in Q3 and Q4 2020. Demand peaked in late November 2020 at 35.4% above balance and declined continuously until July 20 when it bottomed at 5.1% above balance. Demand today is 5.9% above balance. That is an 22% decline in demand since November. But it didn’t feel that way because inventory has been so extremely low. The market intensity peaked in March and inventory is up 42% since then.

    “What a frantically interesting and engaging industry.”

    Mike DelPrete, Real Estate Tech Strategist

    Monthly sales have decreased by about 12% in the past two months. This is seasonally normal and also to be expected due to the increased supply and decreased demand. The slowing intensity feels weird, but our market is actually moving in a healthier direction. If you have clients expecting a market crash or price decline, they will be disappointed. This moderation will only slow the appreciation.

    An easy way to show anyone expecting a crash why we won’t see one is by using the Cromford Market Index, which is an awesome leading indicator. The index is available to anyone, without a subscription, at www.CromfordReport.com. Anything over 100 is a seller’s market. More importantly, the demand index would have to move below the supply index.

    Today’s buyers are better educated than ever before and they are doing their homework and are not writing such high offers. From the low point in mid-February to now weekly price reductions are up 182%. The majority of the reductions are in the $400K to $800K price range as this is the range with the highest increase in new inventory.

    In Q2 2021, investor purchases were up 15% from Q1 2021, Phoenix topped the charts with an increase of 25% in Q2 2021 from Q1 2021. Phoenix was also the most popular destination for Redfin users when looking outside of their own city.

    National Real Estate:

    • Purchase mortgage applications declined by 2% last week and that was after a 6% decline the week before. Purchase mortgage applications have declined, on an annual basis, for the past three months, reaching their lowest level since May 2020. High prices and continued competition are blamed for the declines.
    • On Saturday the foreclosure moratorium will expire. The CFPB implemented specific rules in which lenders must abide by when foreclosing which will further delay most foreclosures. Abandoned properties will be foreclosed on first. There will be some foreclosures but not a flood. Experts predict maybe 300,000 foreclosures which would be about 6,000 per state if divided up evenly. For details on the CFPB’s foreclosure rules, forbearance, and delinquencies, check out my update from Wednesday, here.

    “Pending sales have seesawed since January, indicating a turning point for the market. Buyers are still interested and want to own a home, but record-high home prices are causing some to retreat. The moderate slowdown in sales is largely due to the huge spike in home prices.”

    Dr. Lawrence Yun, NAR Chief Economist

    iBuyers:

    In order to compete in this fast-paced market, during the first half of 2021, the country’s biggest iBuyers (Opendoor, Offerpad, Redfin, Zillow) expanded their buy box by upwards of 40% and increased their offers to an average of 104.1% of market value. In 2020 the same iBuyers offered an average of 97.6% of market value.

    Simultaneously, iBuyers also dropped their fees to an average of 5.1% at the end of Q2 2021 from an average of 7.2% in 2020. Between the increase in offers and decrease in fees, consumer’s costs are down by 35% this year.

    And iBuyer purchase activity is way up. In the past three months, Opendoor has acquired more properties than it did in all of 2020.

    Final Thoughts:

    Throughout the rest of the year, expect a further weakening of the seller’s market. The declining affordability and buyer fatigue combined with increased inventory are leading us towards a more normal, balanced market. When housing is more balanced, it is not quite as exciting, but it is much healthier and allows for long-term growth. We finally are getting to the calm after the housing storm.

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 7/23/2021

    Real estate continues to normalize and shift from an extreme seller’s market to a less extreme seller’s market. Both the leading and lagging real estate indicators illustrate a slowly moderating housing market. The numbers show that things are changing, nothing is happening too quickly, so the movement is relatively healthy and going in the right direction. Buyers have more options and sellers are making some concessions.

    Yet we face a lot of unknowns. Is this inflation truly transitory? Will the mid-September expiration of the expanded unemployment benefits drive employment growth? How many houses will actually be foreclosed on once the foreclosure moratorium is lifted on 7/31? And how long will that process take? How many renters will be evicted once the eviction ban is lifted on 7/31? What will the proposed infrastructure bill actually look like and how much will go to housing? When will the Fed taper its MBS purchasing? What about the rising COVID numbers?

    Economy:

    In a recent podcast, economist Dr. Peter Linneman discussed real estate and the economy with Willy Walker with Walker & Dunlop, a large commercial lender. These are some of his main points:

    • Consumer inflation is transitory because inflation was negative last year. However, asset inflation has been significant for nearly a decade. (Greater Phoenix housing bottomed out in August of 2011 and homes have been appreciating since September of 2011.)
    • Expect huge employment growth in September, and not before then, because the additional $300 a week in COVID unemployment benefits expires on 9/6/21.
    • In 2020, about 300,000 Americans inherited $50,000 or more; 3 – 10 years earlier than expected due to COVID deaths. This created a large group of unplanned home buyers who otherwise would have waited years for the down payment funds.
    • While he agrees with many other housing experts that we have been under producing for well over 10 years, he disagrees with NAR which states that nationwide we are short 6.8 million units, he thinks the deficit is closer to 3 – 4 million units. Ivy Zelman thinks it could even be closer to one million. He said in multi-family our deficit is about 700,000. All reasons for continued price increases as long as demand remains, but not a dire situation.
    • Expect another era of roaring 20s. There is a lot of money in the system and not a lot of reason to pull it out, if greed turns to fear there will likely be a correction. Rates will stay low, the Fed will not raise them because they need to keep Federal debt cheap so the government can afford the debt. Additionally, he does not see the Fed tapering its monthly bond and MBS purchases. It has kept the market very liquid. The growth may slow but will stay positive.
    • We need to expand to capacity. Supply is lagging. During the pandemic lockdowns, we continued to consume but did not replace what was consumed. This expansion will drive growth and the roaring 20s, though it will be bumpy. The growth will not last forever, do not fight it, asset ownership will create wealth, spend wisely.

    National Real Estate:

    • According to NAR, the median existing-home sales price is up 23.4% year over year and after four months of declines in sales, in June, existing home sales increased by 1.4% from May.
    • The frenzy is calming and the sky rocketing, year over year appreciation rates are just starting to slow.

    “At a broad level, home prices are in no danger of a decline due to tight inventory conditions, but I do expect prices to appreciate at a slower pace by the end of the year. Ideally, the costs for a home would rise roughly in line with income growth, which is likely to happen in 2022 as more listings and new construction become available.”

    -Dr. Lawrence Yun, NAR Chief Economist

    “Supply has modestly improved in recent months due to more housing starts and existing homeowners listing their homes, all of which has resulted in an uptick in sales. Home sales continue to run at a pace above the rate seen before the pandemic.”

    -Dr. Lawrence Yun, NAR Chief Economist
    • Total inventory is up nationwide, giving buyers welcomed relief with slightly more options as inventory levels remain low.

    The AZ Market:

    • New home sales declined by 16% from June to July, yet strong demand remains.
    • Single family rents increased by 6.6% in May, year over year. Phoenix once again saw the largest year over year price increase at 14% followed by Tucson (11.1%) and Las Vegas (10.7%).
    • Arizona tourist spending declined by 41% in 2020 from 2019. In order to boost tourism, Governor Ducey recently announced the Visit Arizona Initiative which will utilize $101.1 million of federal relief funds.

    New Construction:

    Builder confidence, while still very high, declined by one point to 80 in July due to ongoing labor shortages and the high prices of materials.

    New construction mortgage applications declined by 3% in June from May and was down 23.8% from last year. 2020 was the biggest new construction year since 2006.

    In June, new single family starts are up 6.3% from May and up 29.1% year over year. Which is good news as completions were down in June by 6.3% from May.

    “In other words, builders aren’t hedging long-term plans on short-term improvements after the past year of pandemic challenges. As factors like materials costs stabilize over the next three months, buyers may start to see some inventory and price relief in the new construction market.”

    -George Ratiu, Realtor.com Senior Economist

    Lending:

    The adverse market fee, which was a 0.5% fee added to Fannie Mae and Freddie Mac refinances, has officially been axed. Starting August 1, the FHFA will no longer collect this fee. This is welcomed news for borrowers and the mortgage industry.

    In June, second-home mortgage rate locks declined by 11% year over year. Much of the decline is attributed to Fannie Mae’s and Freddie Mac’s cap on second home and investment property mortgages at only 7% of total loan volume.

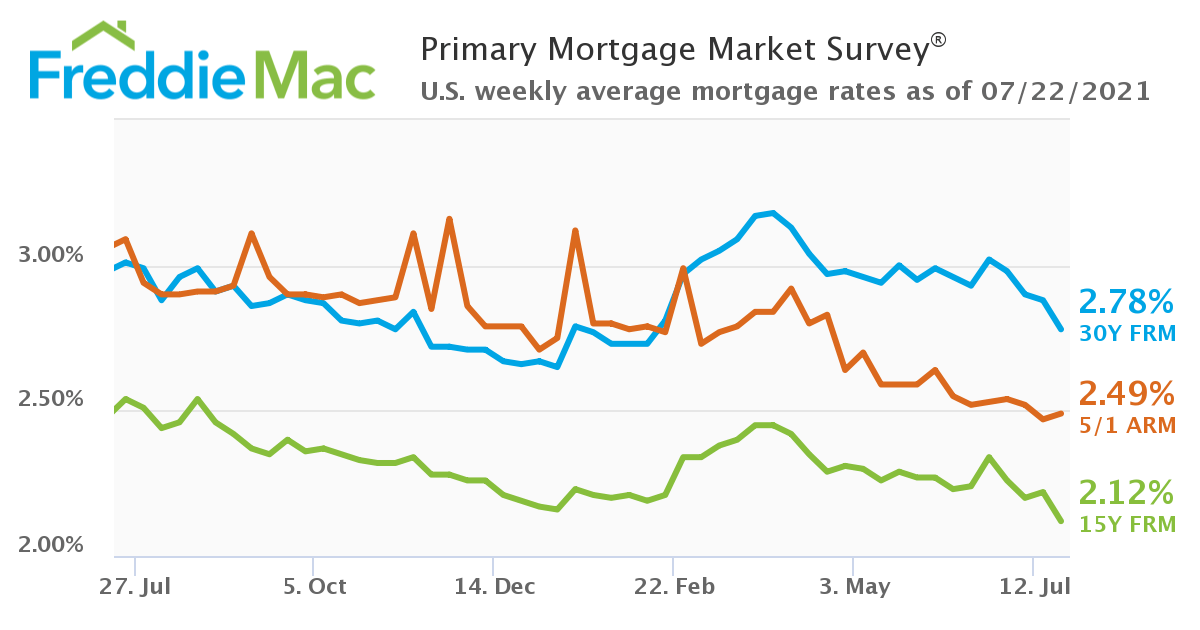
    Mortgage rates dropped again, and the 15-year mortgage reached an all-time low.

    Despite money being so cheap, cash purchases are on the rise. Through April of this year, 30% of purchases are with cash, up from last year’s 25.3%.

    Real Estate News:

    • In 2019, Blackstone, an investment management company with $649 billion in assets, attempted to exit residential real estate investments when it sold its interest in Invitation Homes. The exit did not last very long, in May Blackstone announced the roughly $1 billion purchase of 5,800 apartments in San Diego County with the promise to keep rents affordable for tenants earning 80% or less than the area’s median income. In June, Blackstone announced a $6 billion purchase of Home Partners of America which owns more than 17,000 single family rentals across the country. And this month Blackstone announced a $5.1 billion acquisition of AIG’s affordable housing assets. With over $12 billion in residential real estate investments announced in the past 60 days, Blackstone is back in a big way.
    • In addition to Opendoor’s existing Agent Partner Program, it just announced a second Realtor referral program, Agent Access, which pays out a 1% referral fee plus bonuses ranging from $1,000 to $10,000 based on total number of referrals sent. Opendoor Partner Agents are not allowed to participate in Agent Access.
    • Last Friday, Cloudstar, a data security provider and cloud-hosting company, fell victim to a sophisticated ransomware attack. Its 42,000 users including hundreds of title and escrow companies, currently do not have access to secure documents as everything was taken offline. The company is currently working with forensics experts and law enforcement as negotiations progress.

    Final Thoughts:

    Throughout the rest of the year, expect a further weakening of the seller’s market. The declining affordability and buyer fatigue combined with increased inventory are leading us towards a more normal, balanced market. When housing is more balanced, it is not quite as exciting, but it is much healthier and allows for long-term growth. It is time for the calm after the storm.

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 7/9/2021

    The American economy is big, like nearly $23 trillion big. For perspective, one billion seconds ago it was 1990. One trillion seconds ago was 30,000 BC. The foundation of this giant machine is based on the fundamentals of supply and demand. The price of a loaf of bread, the house down the street, and even 2676 Bayshore Drive (sold for $33.2M in March) is established based on supply and demand.

    Demand is weakening slowly, it always does in Q2 and Q3. That is not what is causing the market to soften though. The softening is caused by the increase in supply. But don’t worry too much, as long as supply remains below demand, we will stay in a seller’s market.

    Even with the extreme ups and downs of the housing data last year, every existing home sales print of 2021 has been higher than last year. This is with the excessive year-over-year price growth and low total inventory. What is apparent to all of us now is that more Americans are buying homes with mortgages in 2020-2021 than any single year from 2008 to 2019. Total sales growth is still trending higher this year but not booming, and considering our demographics and mortgage rates, things look normal on the demand front. 

    -Logan Mohtashami, HousingWire’s Lead Economist

    NAR Membership:

    NAR now has over 1.5 million members. In 2005 there were just under 1.3M members, in 2010 there were about 1M, and in 2015 there were just under 1.2M. That is a 50% increase in 11 years. At the same time, Realtor incomes are declining because of increased competition. In 2020, 54% of Realtors made less than $50,000.

    Differentiation is the key to survival. This week, Mike DelPrete, the premier real estate disruption expert released his 2021 Emerging Models in Real Estate report. Ultimately, the most successful model includes both tech innovation and human interaction.

    “Human beings have the same sorts of psychology that’s important to them when it comes to finding and purchasing shelter for themselves and their family. And a lot of that comes down to trust, a lot of it comes down to having an expert advisor or someone to guide them through the process.”

    -Mike DelPrete

    National Market Update:

    This week, for the ninth week in a row, single family inventory increased to 374,000. That is an 18% increase since April 30. Despite the inventory gains, a healthy market has about one million active single family listings, and to reach a buyer’s market, inventory levels would need to be around 1.5 million listings. This also means that there are four Realtors for every single family listing in the country.

    During Brian Buffini’s recent mid-year update he asked Dr. Lawrence Yun, NAR’s chief economist, what is the single most important thing all Realtors should know right now. Dr. Yun’s answer, “Do not overprice listings.” Buyers are more educated than ever before, and if a listing is on the market for 30 days buyers want to know what is wrong with the house and avoid it.

    Most price gains are made in Q1 and early Q2, which was especially true this year. In 2020 it was the opposite and prices took off in Q3. As we continue to normalize, the ridiculous price appreciation will slow and buyers will be able to negotiate (did I mention we are starting to see seller concessions?). The year over year data is starting to get weird and will not represent the market accurately. Be sure to look at month over month data or compare to 2019. For example, this chart will continue a downward trendline, despite continued growth. Near vertical appreciation is certainly exciting but is not sustainable.

    The AZ Market:

    New home sales prices increased by 13% in the first four months of 2021. Annual new construction appreciation may reach 20% this year. The existing home median appreciation rate has started to decline, down to only 29% from 32% last month. Remember being nervous about 10% appreciation rates? I do.

    To put those percentages into dollar perspective, in June, the median sales price for Greater Phoenix new construction is up by nearly $100,000 year over year! Also, in June, the median sales price for existing home sales is up by $90,000 year over year and up by $120,000 since June of 2019!

    With appreciation like that, people are getting priced out of the market which led to a 16% decline in new home sales from May to June. Existing home sales declined by only 5% over the time period.

    Lending:

    Purchase mortgage applications declined by 1% week over week, which is a combined decline of 6% over the past two weeks. The purchase applications are requesting larger loan amounts which is impacting first time home buyers the most.

    Unemployment:

    The numbers continue to improve, despite a slight uptick in percentage due to a larger workforce. 15.6 million jobs have returned, about 70% of lost jobs.

    Economist Elliot Eisenberg explains, “During June, employers created 850,000 new jobs, the best growth since August 2020’s 1.58 million. Leisure and hospitality led the way with 343,000 jobs. Better yet, unemployment rose to 5.9% from 5.8% as slightly more persons joined the labor market. Job creation totals a strong 3.25 million YTD, but employment remains 6.76 million below its pre-Covid-19 level. Hourly earnings rose an elevated 3.6% Y-o-Y. Taper talk will start relatively soon.” His last sentence is the most concerning. If not done well, tapering the Fed’s bond and MBS monthly purchases could spook the markets but that is a discussion for another day.

    Real Estate News:

    • Zillow announced updates to its Premier Agent “Best of Zillow” criteria. In addition to requiring high customer service scores, agents “transaction history and their readiness to take on customer connections and grow with Zillow” will also be heavily weighted. Zillow is looking at conversion rates, local market conditions, number of monthly connections, and effectively using a CRM.
    • Brokerage platform startup, Side, which reached a valuation of $1 billion, also known as unicorn status, only three months ago recently announced its IPO and that it is now valued at $2.5 billion.

    Final Thoughts:

    Not only will Phoenix get a big boost in downtown spending thanks to the Suns making the NBA Finals, but the entire state could get an economic boost due to additional exposure and publicity. Local economist Elliott Pollack said, “People tend to pick up things from watching TV. They like the area. They like what they see. They like what they hear and so if they’re looking to move … that might be the tipping point to come to Phoenix. If you’re a business, it could be the same thing.”

    Those supply and demand fundamentals remain, we are adding inventory to satisfy the demand, regardless of where it comes from. While it is important not to oversupply demand, a more balanced market is crucial for the overall health of the economy. This is how home price appreciation is tamed and how inflation is calmed.

    Go Suns!

    Copyright 2021 Sarah Perkins