Category: AZ Real Estate

  • Greater Phoenix Real Estate Update 7/2/2021

    The market is softening = slowing = normalizing = moving closer to balance which are all good things even though it feels weird. After the wild ride of 2020 and the nearly non-existent inventory levels of Q1 2021, the real estate market is working out its kinks. I have mentioned it before and will say it again, it is impressive what a person can get used to. We got used to 10 or 15 buyers for each listing. We even (kinda) got used to only 4,000 active listings (when we should have 25,000). Now we have to prepare today’s buyers and sellers (and ourselves) for another new normal, a much healthier one.

    National Real Estate:

    Existing home sales declined again for the fourth consecutive month in May but the rate of decline is slowing. Sales are down by nearly 1% since April and 14% since February to a seasonally adjusted rate of 5.8 million units. In 2020 there were 5.64 million existing home sales. Low inventory, falling affordability, and buyer fatigue are blamed for the declines. Sales are nearing pre-pandemic levels as the market continues to normalize and the pent-up demand from last year is exhausted.

    Speaking of falling affordability, the median existing-home price for all housing types in May was $350,300, up 23.6% from May 2020 ($283,500). This is an NAR record high and marks 111 straight months of year-over-year gains since March 2012.

    Pending home sales increased by 8% in May, month over month, after declines in April. The increase is attributed to the low interest rates and increasing inventory. Nationally, active inventory is up by nearly 16% since February.

    New Construction:

    New construction sales declined by 5.9% in May month over month, to an annualized rate of 769,000 units. This is the second month in a row of declines, April also had a 5.9% decline in new home sales. Rising sales prices combined with lumber, labor, and material shortages are blamed for the decline.

    Meanwhile, housing starts increased by 3.6% during the same time period putting new construction inventory levels at 5.1 months. When inventory levels are 4.3 months or less builders are happily building, when inventory levels are 4.4 to 6.4 months builders need evidence of sales growth to continue building, and at 6.5 months or more builders slow or even stop production. Builders only build houses they know they can sell.

    The new construction sales chart below shows the initial declines in sales followed by a giant increase and the recent declines from that peak level.

    The AZ Market:

    Here in Greater Phoenix, when it comes to real estate, everything is magnified. In 2008, when the market crashed, as a country values declined by 25%. Phoenix saw 45% declines. Today, as the entire country sees 23.6% year over year appreciation, Phoenix’s appreciation rate reached 33%, year over year. It should come as no surprise that as the market normalizes, Phoenix is normalizing faster. Inventory is up nationally 16% since February, in Phoenix, it is up by nearly 28% since February.

    May’s Case-Shiller Home Price Index was released on Tuesday. For the 11th month straight, the US has seen price gains. In May it was 15.4%, year over year, the highest reading in over 30 years. Greater Phoenix has topped this chart for the past 23 months and in April came in with a 22.3% year over year price gain. Case-Shiller is what the federal government, national builders, and Wall Street use to gauge price appreciation.

    Cities like San Francisco and New York had huge rental declines. Not only do Phoenix and Tucson top the charts for rental appreciation but four valley cities are in the top 10 fastest growing rents since March 2020.

    ShowingTime’s latest data shows that home showings saw an unusual dip in May, which could indicate further market stabilization. Nationally, showings usually peak in April and remain high through June. In AZ showings slow in the summer more than other parts of the country. We are currently running 32.4% below this time in 2019 and 24.4% below this time in 2020. (Phoenix declines were larger than the national declines)

    Evictions, Foreclosures, and Forbearance:

    Last week the CDC extended the eviction moratorium through the end of July and stated, “this is intended to be the final extension of the moratorium.” On Tuesday the Supreme Court denied the requests to lift the nationwide eviction moratorium filed by the Alabama and Georgia Realtor associations last November. Justice Brett Kavanaugh agrees that the CDC overstepped its authority by issuing the ban but denied the request. The Supreme Court will frown on any further extensions without congressional approval.

    Last week the foreclosure moratorium was also granted a final extended for another month, now set to expire on July 31. On Wednesday the CFPB announced its final ruling on how mortgage servicers are to handle foreclosure proceedings. Only those borrowers who do not qualify for assistance, fail to meet the assistance agreement, who are unable to be reached, or the home has been abandoned are able to be foreclosed on once the moratorium is lifted. Servicers must contact delinquent borrowers prior to foreclosing to offer loss mitigation plans. The rule goes into effect on August 31 which likely means that servicers will not be able to initiate foreclosure proceedings until the end of the year. For more information on the CFPB’s ruling and forbearance info, check out my AZ Forbearance Update from Wednesday, here.

    Lending:

    Rising sales prices likely caused the 5% week over week decline of purchase mortgage applications last week. They are also down by 17% year over year.

    Ginnie Mae announced a new 40 year mortgage term option created for struggling borrowers in order to lower their monthly payments and keep them in their home. The product will be available in October and will be sold on the secondary market.

    New Laws:

    • Within hours of the June 23 Supreme Court ruling, stating that the FHFA’s structure is unconstitutional, giving new power to the president to fire the head of the FHFA, the White House announced plans to replace Mark Calabria, the head of FHFA. Calabria then resigned and by the end of the day, Sandra Thompson was appointed as acting director of the FHFA. Her appointment will likely lead to more policy change and diminishes the likelihood of Fannie Mae and Freddie Mac’s exit from conservatorship. The irony behind this activity is that this lawsuit was brought by investors hoping to end the conservatorship so profits would flow to the investors rather than the government. Thompson’s appointment all but guarantees that Fannie and Freddie will remain in conservatorship for years to come.

    Real Estate News:

    • Not only are consumers using cryptocurrency to buy houses, now people are talking about utilizing non-fungible tokens (like crypto, stored on blockchain ledgers) for homeownership. This NFT-ing of real estate would allow the ownership of a home to be held in one digital wallet which opens up new options for fractional ownership.
    • A credit card provider says it’s partnering with landlords, like Blackstone and Lennar, to help provide “every young person a path to homeownership” by allowing them pay their monthly rent with a credit card, and apply the points they earn to making a down payment on a home. (I am not sure this is best idea)
    • Offerpad is now a mortgage broker. Offerpad Home Loans is licensed in AZ, CO, and AL and plans further, rapid expansion. Will they offer seller carrybacks? If so, the impact to traditional lending could be significant by nearly eliminating appraisals and other typical loan application steps required by traditional lenders.
    • Yesterday the Department of Justice withdrew the proposed settlement and the lawsuit it filed last November against NAR. The settlement for the antitrust lawsuit required NAR to repeal or change several rules regarding buyer agent commissions. The DOJ plans to refile the suit at a later date.

    Final Thoughts:

    Elliott Pollack wrote on Monday, “The impacts of supply and demand imbalances continue to be on full display in each weekly release of economic data. Consumer spending on goods has been hampered, not by lack of demand, but rather bottlenecks in production and the supply chain. Demand has stayed incredibly strong due to pent-up savings, and is driving up prices, with housing at the forefront. Fortunately, with continued vaccinations, more and more of the economy has reopened and spending will shift from goods towards services. This will help drive the country toward full economic recovery and will bolster those industries hit hardest such as food services, tourism, and hospitality.”

    Copyright 2021 Sarah Perkins

  • AZ Forbearance Update 6/30/2021

    In this 19 minute video, Lydia Wietsma and I discuss the latest in forbearance, extensions, and tax liens. We share this information to help provide guidance for real estate professionals and struggling borrowers.

    Deadline & Extensions:

    There is a lot of news around forbearance right now. Today is the final day to get started on a forbearance plan. At the end of the day, no new forbearance plans will be created.

    Do not confuse the end of forbearance with the other moratoriums that were extended last week. Both the eviction and foreclosure moratoriums were extended for one more final month. Those moratoriums will expire at the end of July.

    Forbearance Numbers:

    The forbearance numbers continue to decline. About 3.93% of mortgages or roughly 2 million borrowers remain in a plan after 17 weeks of declines.

    Forbearance by Stage:

    • 10.7% of borrowers are in the initial stage. Initial requests this week dropped to their lowest rate since forbearance plans started 15 months ago. According to Mike Fratantoni, MBA’s senior vice president and chief economist, the pace of new forbearance requests remained at an acutely low level of 4 basis points or 0.04% of borrowers.
    • 83.1% of borrowers are on extension, down from recent weeks.
    • 6.2% of borrowers are re-entries, up from recent weeks also.

    Forbearance Exits from June 1, 2020 through June 20, 2021

    45.2% of borrowers continued making their payments, got caught up upon exit, or paid off the loan with a refinance or sale upon exit. This number continues to decline slightly each week.

    15.2% of borrowers exited their forbearance plan still behind on their payments and without a loss mitigation plan in place.

    Even with the end of forbearance, borrowers still have options. Black Knight estimated that of the loans in forbearance, 96% have at least 10% equity in their homes – typically enough to sell through traditional real estate channels to avoid a default or short sale.

    CFBP:

    On Tuesday, the Consumer Financial Protection Bureau (CFPB) extensive mortgage servicing regulations it hopes will prevent “unwelcome surprises” for borrowers exiting forbearance.

    The CFPB outlined the rules for mortgage servicers to follow in the coming months and them, “Unprepared is unacceptable.”

    Servicers may initiate foreclosure proceedings only after the borrower has submitted a loss mitigation application, and either isn’t eligible for, breaks or rejects the loss mitigation plan. If the borrower was already six months past due by March 2020 or if the property is abandoned, the loan servicer is exempt from those requirements.

    The CFPB rule also outlines escrow shortages which can be included in the loss mitigation option. There are limits on how much servicers require borrowers to deposit in an escrow account over the next year.

    Lenders and servicers may offer streamlined loan modifications, as long as the modification does not increase the monthly payments, or increase the mortgage term beyond 40 years. Servicers may not charge extra fees for the loan modification, and if a borrower accepts a loan modification, the servicer must waive any late fees.

    The CFPB wants servicers to be proactive about communicating with borrowers about their options, especially if they are not in a forbearance plan.

    If borrowers are still delinquent, servicers must contact them ahead of the end of their forbearance period to give them the option to complete a loss mitigation plan.

    Finally, the rule adds clarity to the definition of financial hardship to mean any hardship that the pandemic brought on, either indirectly or directly, from March 2020 to February 2021.

    The rule will take effect at the end of August.

    To learn more about the CFPB, submit a complaint, or better understand borrower protections visit https://www.consumerfinance.gov/

    Servicers, BPOs, and Tax Liens:

    BPO requests are up. 15 new ones last week and 16 so far this week. Lydia is not only giving a statement of value but is also checking the exterior condition and whether or not the property is vacant.

    In addition to the regular BPO visits, she is also being asked to deliver tax lien letters to homeowners that do not have a mortgage but are behind on their property tax payments. Tax lien foreclosures have also been suspended and will resume when the moratorium is lifted.

    Buyers and sellers need to let their Realtor know if they have done a forbearance on any property in the country. It is not something that can be just swept under the rug and it is not something to be ashamed of. As inventory grows strategies change. Forbearance was created to keep people in their homes and has been successful at doing so.

  • Greater Phoenix Real Estate Update 6/25/2021

    Today is all about the AZ market. On Tuesday, Lawyers Title hosted a presentation with Tina Tamboer with the Cromford Report. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.

    Why Do We Have a Housing Shortage?

    From 2000 to 2009 we over-built for the population. From 2010-2020 we under-built for the population. In 2004-2006, speculation building on credit caused huge problems. When the lending dried up, we had huge price declines. This is not a gap that can be closed easily.

    True demand is based on population. With 290 people moving here a day, we have the population to support more building.

    As housing units increase and reduce the gap between building and population growth the strong seller’s market will weaken and could even go flat. Check out the population growth versus housing unit growth. In 2008 we built 0.6 units for every added person. In 2012 it was 0.11 new units per person. In 2020 (through July) it was 0.30. 0.4 per person is ideal.

    In 2000 there were 2.44 people per household, it then declined through 2009 and bottomed out at 2.32.  Through July 2020 it reached 2.53 people per household. Arizona is #13 for having the most people per household in the country. How many houses are only for tourists? We do not know for sure. There is not a lot of available data on short term rentals. There are many properties that are short term rentals that are not registered as short term rentals.

    The areas with the most new developments are also the areas with the most population growth. Queen Creek tops the charts at 16.2% population growth. Pinal County’s population growth outpaced Maricopa County’s.

    The Greater Phoenix Economic Council (GPEC) expects a 14% population increase by 2029. 11.2% of that growth in Phoenix, 13.8% on the east side, and 26.4% on the west side. This population growth is projected in conjunction with all of the job growth. GPEC has really focused on bringing in a lot of new jobs. In 2010 we were all real estate and tourism. Today our job market is much more diverse.

    New Development: 

    • For interactive maps on land use and locations of new development, visit http://geo.azmag.gov/maps/landuse/
    • Single family permits are up 40% year to date. 25% fewer than in 2005 at this time.
    • Builder associations are reporting real material shortages. 90% of builders are saying that something is behind and slowing them down. 95% are saying it is a slow down in appliances.
    • Lumber prices are dropping but are not expected to reach pre-pandemic prices.
    • Home renovations are starting to slow because people are going back to work.

    Cromford Market Index (CMI):

    Available on the main page of the Cromford Report: https://cromfordreport.com/ (without a subscription)

    • 100 is balanced and prices rise at the rate of inflation, below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110. 2014 was a balanced market.
    • On 3/20/2020 we were at 241
    • On 5/15/2020 we were at 145.2
    • Yesterday we were at 422.6
    • We peaked on 3/14/2021 at 514.9
    • Prior to this run, the previous peak was 312.9 in the spring of 2005.
    • CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI.

    How long can we expect to be in this market? Some people think we are on the cusp of a market crash. While it is not a crash, the market is softening. Inventory is increasing more quickly than demand is declining. Demand has declined by 0.7 points in the past 30 days, while inventory has increased by 1.6 points. More options for buyers. It is not about the demand right now, it is about supply.

    More listings are coming to market and staying active. The CMI is dropping because inventory is increasing. As inventory increases sellers are getting fewer offers and people are noticing.

    How long will be in a seller’s market? Do not predict the CMI. It is not predictable. It is the predictor.

    If we are dropping 27 points a month it will take a year to go to balance. By the end of December, we could be at 265, still a very strong seller’s market. This is a trendline, things can change quickly and each city has its own distinct market trendline.

    As the seller’s market weakens, people will get very nervous about a market crash and declining property values and think may wait to buy. Remember demand needs to be lower than supply. With supply 75% below normal and demand nearly 7% above normal, it will take a long time for demand to be lower than supply. Before the 2008 crash, there were 57,000 active listings. Today there are fewer than 6,000 active listings. We do not have lots of listings. The housing market isn’t like bitcoin. We are not overbuilding without the population growth. Prices are not going to drop.

    Using 4 week averages and tons of past data, we can draw a trendline from the CMI, illustrating when we might reach a balanced market. No reason to believe that this will stay in a basic trendline. It will adjust. It is only what we know today. Since each city is so different, it is best to check each one weekly. To show the variation between cities, these are the timelines in which they could reach balance:

    • Phoenix 14.3 months
    • Chandler 13 months
    • Scottsdale 8 months
    • Mesa 5.5 months
    • Gilbert 4.8 months

    Always look at demand. Today’s high CMI is mostly based on low supply. When demand drops below normal, there are fewer transactions, but prices still go up, just more slowly. Mortgage lenders loosened credit slightly in May. Demand increases when it is easier to get a loan. Low rates are still desirable.

    For Sellers:

    This means that as we come out of a strong seller’s market and into a weaker one they may have to pay seller concessions. In a strong seller’s market, only about 3% of sellers pay concessions. In a weak one, 25% of sellers pay concessions. They also have to make more repairs and the property will likely spend more time on the market. The market is still super hot and it is a great time to sell.

    For Buyers:

    It is still a great time to buy. Interest rates are low. Home prices will only continue increasing. Buyers last year who opted to wait are now paying 30% more for the same house. In Q1 2021 62.8% of homes sold were affordable. In 2005 26.6% of homes were affordable. Wages have increased 26% in the last 5 years. Rents are up 23%. To buy the median house with 10% down the monthly payment is $1843 a month. To rent the same house, renters are spending $1975 a month. It is cheaper to buy.

    Inflation:

    Hit 5%. People are talking about housing prices dropping due to inflation. Low inflation is not necessarily good. Low inflation happens when people are not spending their money. Inflation increases because people are spending a lot of money. We had a stimulus that drove more spending. The spikes in spending doesn’t always last. We were told to stay home and then they gave us money so we spent it on stuff like boats, guns, cars, clothes, appliances, etc. We were not making any new stuff to replace what we bought so we ran out and prices went up. Supply and demand.

    Inflation is the relationship of appreciation. The rate of inflation is the appreciation in a balanced market. The buyer’s market appreciates a lower rate than the rate of inflation. Seller’s markets appreciate at a rate higher than the rate of inflation.

    Forbearance:

    Forbearance could speed up the rate at which we move to balance. There are about 2 million mortgages in forbearance. What will happen in July? Struggling borrowers have until June 30 to enter into a forbearance plan and will have the ability to stay for 12 months. Forbearance exits will be spread out across the next 12 months. Most homeowners are staying in their homes after exiting their plan. About 15% of borrowers are leaving forbearance without a loss mitigation plan in place. Divided up by state, we could have about 6,300 borrowers that need to sell.

    Supply:

    Supply is up 28% since February but is still 40% below this time last year. If we got 6,300 new listings we would match where we were in 2018.

    Certain price ranges have bigger increases than others:

    • $300K-$400K is up 31.4% since February.
    • $400K-$800K is up 79.5% since February.
    • $800K-$1M is up 67.6% since February.
    • Over $1M is up 10.1% since February.

    More and more homeowners are comfortable with selling their home now. We are seeing the high side of seasonality and going into the summer slowdown, which is normal. We are following the 2019 trends, which is a good thing. A more balanced market is a healthier market.

    Price Reductions:

    Price reductions have increased by 70% from 2/14/21. We are seeing a lot of price reductions but not a lot compared to other years. This is a trend.

    Demand:

    Listings under contract are down 16.9% from this time in 2020 and down only 5% from this time in 2019. Again, here price point matters:

    • $300K-$400K listings under contract are down 3.6% below 2020.
    • $400K-$800K listings under contract are up 24.3% above 2020.
    • $800K-$1M listings under contract are up 42.2% above 2020.
    • $1M+ listings under contract are up 56.4% above 2020.

    So far in June, 61.5% of listings sold over asking, reflecting contracts written 30-45 days ago, the market was different 30-45 days ago. June closings are closing 2% higher than their list prices. 97% is the normal range for closing. June is 102%. The median amount over asking is $20,000.

    The median days on market is still only 6 days, the same as February. This number will start to go up due to the increased inventory.

    2021 is now the new benchmark with the biggest sales count ever from January through May. There have been 1.1% more sales than in 2005.

    Luxury had the biggest year ever in 2020 and so far in 2021 it is continuing. The first 5 months of 2021 saw an increase of 147% in closings for properties over $1M.

    Final Thoughts:

    The seller’s market is weakening but we do not have desperate sellers so we are not in a buyer’s market. Inventory is rising and demand remains solid. May had an appreciation rate of 39% and June, so far, is at 38% appreciation. The appreciation rates will slow as more inventory comes to market and slowing appreciation is a good thing. There is lots of job growth with more to come.

  • This Week in Greater Phoenix Housing 6/21/2021

    In this 10 minute video, Amber Kovarik and I discuss the latest in real estate and lending.

    Supply, Demand, and Appreciation:

    It is incredible what a human can get used to. Some people are afraid of moving into a more normal, more balanced market. We got used to operating under extreme pressure due to high demand and low inventory. That market isn’t healthy and it peaked in March. Now, we are, very slowly, moving towards a healthier market and it is a good thing.

    In the past 3 weeks, inventory has increased by 13%, while that is a large increase we still only have 5800 active listings. Demand is about 7% above normal, which means that demand is solid but is continuing to decline, more slowly than inventory is increasing. Even with these increases, it will take years to get to normal supply levels.

    The Greater Phoenix appreciation rate is over 30%. 18 months ago, the idea of 10% appreciation seemed excessively high. The relationship between supply and demand dictates appreciation. In 2005 it was the extremely high demand from the speculative buyers that pushed prices up so significantly. Today it is the extremely low inventory levels and more/less regular demand that is pushing up the prices. Today’s buyers are qualified buyers looking to live in these houses.

    As more and more sellers are willing to list their properties, the increased competition will slow appreciation and allow for more buyers to enter the market, which is a good thing. It will not put us in negative appreciation. We are seeing an increase in price reductions. Now is not the time to overprice listings. Buyers are doing their homework.

    Equity:

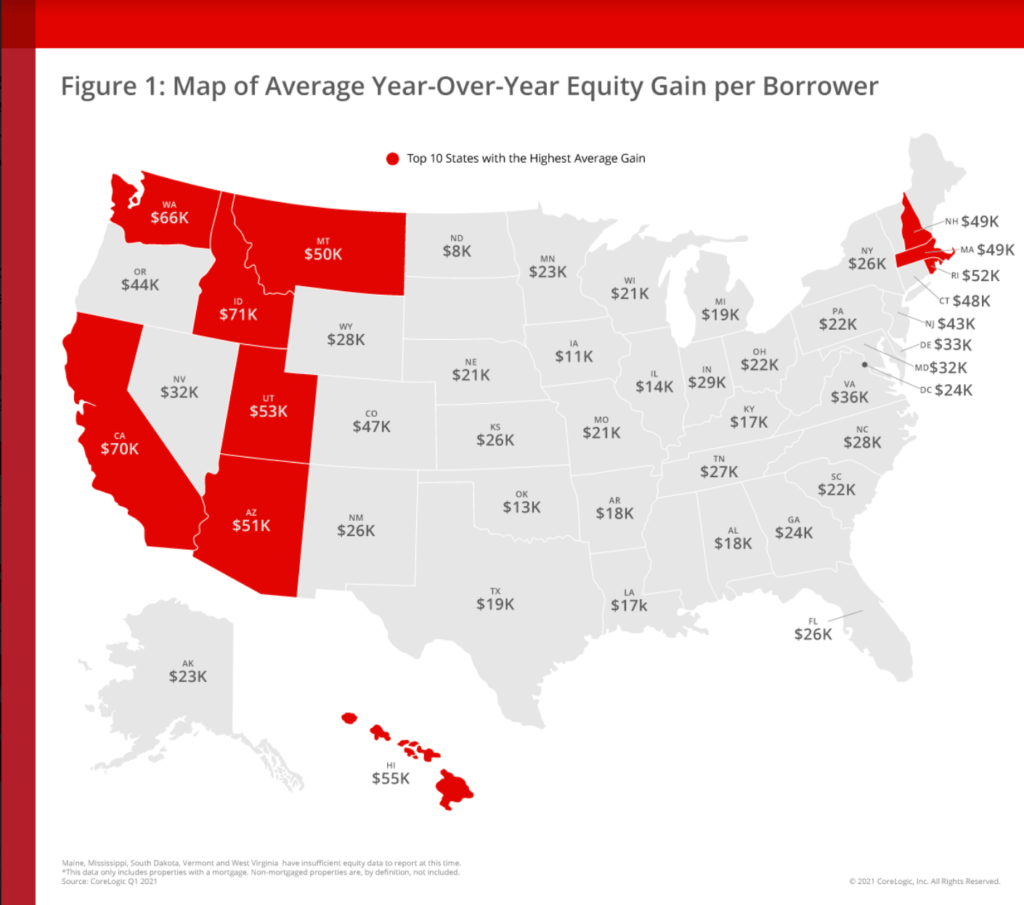
    A recent report from CoreLogic states that homeowners gained $1.9 trillion in equity in Q1 2021, which is a year-over-year increase of 19.6%. Going deeper that breaks down to an increase of $33,400 in equity per homeowner and is the highest gain in over 10 years. Arizona’s year-over-year average equity increase is $51,000!

    Housing Shortage:

    According to a recent NAR report, construction declines and housing demolition over the past 30 years,  has created a 6.8 million unit housing shortage nationwide. NAR is calling for a “major national commitment” for more building of all housing types, especially for more affordable housing units. To close the gap, builders will have to build 2 million homes a year for the next 10 years. The challenge here is that builders build to make money and when demand declines, they stop building, which means to reach the building levels NAR calls for, government assistance will be necessary.

    3D Printed House:

    Habitat for Humanity is building its first 3D printed house in Tempe. The goal is to expedite the building process while reducing labor and construction costs. About 70% of the building will be printed and the remaining 30% will be built through traditional construction. The selected family will move into the 1,600 square foot, 3 bedroom, 2 bathroom home this fall.

    Federal Reserve:

    Last week’s Fed meeting announcements moved the markets significantly, inflation increased a lot more than expected. Some analysts believe inflation has peaked. Rates are up. All eyes will be on next month’s inflation report as it could be very telling about the future.

    FHA Announcement:

    On Friday we got some good news from FHA regarding guidelines on student payment loans. Currently, regardless of the payment status, we have to hit the borrower for the greater of:

    • 1 percent of the outstanding balance on the loan; or
    • The monthly payment reported on the borrowers credit report; or
    • The actual documented payment; provided the payment will fully amortize the loan over its term 

    The NEW guidelines state we must use:

    • the payment amount reported on the credit report or the actual documented payment, when the payment amount is above zero; or
    • 0.5 percent of the outstanding loan balance, when the monthly payment reported on the borrower’s credit report is zero 

    This new guideline is effective for all case numbers on or after August 16th. 

  • Greater Phoenix Real Estate Update 6/18/2021

    The real estate market continues to shift and change, slowly moving towards normalization. Prices continue to increase, demand is slightly subsiding, and inventory is growing (and has a LONG way to go). The intensity is cooling (from 500 degrees to 350 – its still HOT), and fatigued buyers are writing fewer offers before one is accepted. The headlines attempting to explain the still very hot, yet cooling market seem to be causing more confusion than clarification.

    National Real Estate:

    A recent report from CoreLogic states that homeowners gained $1.9 trillion in equity in Q1 2021, which is a year over year increase of 19.6%. Going deeper that breaks down to an increase of $33,400 in equity per homeowner and is the highest gain in over 10 years. Arizona’s year over year average equity increase is $51,000!

    Demand is slowing and the market is cooling. Pending sales are down (4.4% in April from March). Mortgage applications are down 7% from the average levels from January and February 2020. Redfin’s demand index is down 12% from the peak in late March. These shifts are not a bubble bursting but gradual changes towards a more normal market. Given the extreme imbalance during the winter and spring, it will take well over a year before we have a balanced market.

    Active single family inventory climbed another 3.8% this week to 342,000. That’s now up 11% from the bottom on April 30, but still 51% lower than this time last year when inventory started falling 1-2% a week.

    The Altos market action index is another tool to gauge demand. Any reading above 30 is a seller’s market. The notable change is that the weekly reading (dotted line) dipped below the 90-day rolling average for the first time all year. This shows that the market is not getting hotter from here but is still very hot.

    The AZ Market:

    -For a deep dive into the Greater Phoenix market, join us on June 22 for a Cromford Market Update with Tina Tamboer. For details and registration, click here.

    -Greater Phoenix’s median monthly appreciation rate has declined by maybe 1%, down to 31% year over year. (yes, you read that correctly) Healthy appreciation is 3-6%. Today’s huge appreciation rates are due to low inventory levels and not super high demand. Demand remains solid but is only about 7% above normal.

    -Inventory levels in Greater Phoenix have increased by 10% since the end of May, matching listings counts from the end of January.

    -Habitat for Humanity is building its first 3D printed house in Tempe. The goal is to expedite the building process while reducing labor and construction costs. About 70% of the building will be printed and the remaining 30% will be built through traditional construction. The selected family will move into the 1,600 square foot, 3 bedroom, 2 bathroom home this fall.

    -In Q1 2021 the Maricopa County Assessor’s Office received twice as many construction permit requests as in 2019 and 2020. A total of 19,232 residential and commercial permits were requested. This increase was expected.

    “[We’ve] been seeing this trend now for a number of years, so I think we’re all scaling toward that. It wasn’t like one day the door got opened and a flood of water just rushed in, this has been just kind of a growing trend that we’ve been monitoring over the last several years.”

    – Eddie Cook, Maricopa County Assessor

    -NAR has identified both Phoenix and Tucson as top 10 commercial real estate markets in 2021.

    –Phoenix took the top spot in Origin Investments’ machine learning database that identifies cities with “promising fundamentals for success.”

    New Construction:

    Lumber prices have declined by 40% since early May. Timberland industry executives, from several different companies, have been selling off company stock at unusually high rates indicating that Wall Street expects lumber prices to continue to decline.

    “This level of selling is simply unusual and to have this type of alignment among peers like this is unusual. It shows a consensus within the group about how they are thinking about their stock prices.”

    -Ben Silverman, director of research at stocks analytics firm InsiderScore

    The speedy price appreciation of not only lumber but appliances and other materials needed for new construction slightly reduced June’s builder confidence rating to 81 in June, from 83 in May, the lowest level since August 2020. Ratings over 50 reflect strong market conditions.

    Nationwide, single family housing starts increased by 4.2% from April to May while completions were down by 2.6% and permits declined over the same time period.

    Housing Shortage:

    According to a recent NAR report, construction declines over the past 30 years has created a 5.5 million unit housing shortage nationwide. NAR is calling for a “major national commitment” for more building of all housing types, especially for more affordable housing units. To close the gap, builders will have to build 2 million homes a year for the next 10 years. When you combine the underbuilding count with housing demolition (intentional or disaster) the shortfall grows to 6.8 million units.

    NAR is asking the government for help. It will take federal policy to increase the rate of construction to the levels needed. Builders build homes to make money and after the 2008 crash, builders are even more careful with the bottom line. When interest rates rise, new construction takes a bigger hit than resale. In 2018 when mortgage rates moved up to 5%, new construction inventory grew to 6.5 months and builders stopped building. When rates declined in early 2019 inventory declined and builders started building again. When rates increase or demand declines, what will keep the builders building?

    “Unless the government steps in to build when new home sales demand gets soft, we will not add homes to the builders’ demand algorithm. Builders have learned to tightly control inventory by retreating from construction when demand becomes slack. Building more homes is bad business during weaker times.”

    -Logan Mohtashami, HousingWire’s Lead Economist

    Rentals:

    The average size of apartment units under construction is 50 square feet larger than the average apartment unit built over the past five years. The new units allow space for a home office.

    In May, the median rent for multifamily properties increased by 2.5% year over year, matching the growth rate of March 2020. At 9.6%, Phoenix had the second-highest multifamily rent growth behind the Inland Empire, CA. San Jose, San Francisco, and NYC still have negative growth but are improving.

    In April, single-family rents grew by 5.3% nationwide, more than double the April 2020 growth (2.4%). Phoenix’s growth led the country, again, at 12.2% year over year. Chicago and Boston both saw negative growth.

    Remember when rental prices increase as quickly as sales prices the market is operating on healthy fundamentals. When rents decrease while sales prices increase it is a bubble market. Prices decline due to vacancies, which neither the purchase nor rental market have much of.

    Real Estate News:

    Final Thoughts:

    Remember real estate changes slowly. Yes, it has never moved so quickly but it doesn’t change overnight, despite what it seems. By understanding the implications of the slight shifts, we can all better council our clients. And while Sean Black, CEO of Knock, believes that within 5 – 10 years buying a house will be like booking a short term rental on Airbnb, a lot has to happen first.

    Copyright 2021 Sarah Perkins

  • AZ Forbearance Update 6/16/2021

    In this 18 minute video, Lydia Wietsma and I discuss the latest in forbearance, extensions, tax liens, and servicing.

    Forbearance Numbers:

    For 15 straight weeks, the forbearance numbers have been decreasing. There are now about 2 million loans in forbearance or about 4.04% of all mortgages, nationwide.

    Forbearance by Stage:

    • 10.6% of borrowers are in the initial stage of forbearance and new requests dropped down to their lowest level since March 2020.
    • 83.6% of borrowers are on extension, down from previous weeks. Well over 50% of borrowers on extension have been in forbearance for over 12 months.  More and more borrowers are reaching the 15-month mark for their plans and are required to exit forbearance. It is expected that there will be about 700,000 exits this month alone.
    • 5.8% of borrowers are re-entries, up from previous weeks.

    Forbearance Exits from June 1, 2020 through June 6, 2021:

    45.7% of borrowers continued making their payments, got caught up upon exit, or paid off the loan with a refinance or sale upon exit. This number continues to decline slightly each week.

    15.3% of borrowers exited their plan, still behind on their payments and without a loss mitigation plan in place. This number has been increasing.

    “We are seeing an increase in the share of forbearance exits, where borrowers do not have a loss mitigation plan in place. Homeowners who are reaching the end of their forbearance term need to contact their servicer to discuss the next steps in the process, as servicers cannot extend the forbearance term without talking to the borrower.”

    Mike Fratantoni, MBA’s Senior Vice President and Chief Economist

    Forbearance News:

    The FHFA extended forbearance for multifamily rental properties only. The extension is through the end of September. For a landlord to extend forbearance they are required to extend the tenant protections meaning they cannot evict a tenant solely for lack or payment among other things. The eviction ban is set to expire on June 30. Many industry groups, including NAR and the MBA, have asked the CDC to allow the ban to expire.

    For any other property type, the window to enter forbearance is closing. June 30th is the last day to get started on a plan.

    CFPB:

    Finance watchdog, the CFPB is looking to make examples out of lenders and servicers for crossing any lines. They are particularly looking at how forbearance plans are handled. With the administration change, so did the CFPB leadership. The organization did not police as much from 2018-2020 having only fined companies about $800 million. A much smaller number than the $12 billion in fines distributed from 2012-2018. The new leadership stated, “They’re looking to pin some heads on the wall, to show that there’s a new cop on the beat. They want to make examples.”

    Equity & Debt:

    We had talked a lot about the increasing equity environment we are currently in. When you combine that and the responsible lending of the past 10 years it is no surprise that mortgage debt has been kept in check. This chart shows that we do not have a lot of mortgage debt growth since the market crashed 13 years ago but equity certainly has increased.

    From Freddie Mac Deputy Chief Economist Len Kiefer:

    Tax Liens:

    Tax Lien letters are going out from the servicers. This is likely only for properties without a mortgage as most mortgage companies make the tax payments as well. Tax lien foreclosures have also been restricted by the foreclosure moratorium. It may be the iBuyers who have hired the servicing company to distribute the letters and do additional inspections. While we do not know all of the details, we do not know that multiple iBuyers are working with servicing companies for inspections. It is easy to suspect that there is more at play here as well.

    Deadlines:

    There are two weeks left before the end of the forbearance window and the eviction and foreclosure moratoriums are lifted. Based on her interactions with the servicer she works with, Lydia does not believe that they are expecting another extension. They are prepping to move forward come July 1.

  • Greater Phoenix Real Estate Update 6/11/2021

    At Weight Watchers, the first five pounds lost is celebrated, regardless of the end goal. The celebration is to acknowledge the initial progress towards a healthy lifestyle. While today’s residential real estate market remains unhealthy (remember when 10% appreciation was a lot?), initial progress has been made. Prices are leveling off, supply is increasing, and immediate sales are declining. This is good for buyers, especially first-time homebuyers, who are the key to the real estate market. Without them, the machine stops.

    National Real Estate:

    Pending Sales:

    Pending home sales declined by 4.4% in April from March but were up 51.7% year over year (keep in mind April of 2020 was not a big month for contract signings). Low supply and fast-rising prices are blamed for the decline.

    “Contract signings are approaching pre-pandemic levels after the big surge due to the lack of sufficient supply of affordable homes. The upper-end market is still moving sharply as inventory is more plentiful there.”

    -Dr. Lawrence Yun, NAR’s chief economist

    Another potential correlation is the decline in personal savings rates, which dropped from 27.7% in March to 14.9% in April. People are spending more on services and entertainment as the economy reopens. Last year’s closures allowed people to accrue a down payment much more quickly than in the past.

    While pending sales do not tell the whole story, they are a leading indicator and help us gauge where the market is going.

    Pricing:

    51% of homes sold above asking price in May. Last May it was only 26%. As more inventory comes on the market, these numbers will fall and appreciation will slow, which is good for the overall health of the market.

    In a balanced market, about 30% of listings take a price cut before they sell. In hot markets, it is about 25%. Today, we are at 17.1%. This number is ticking up each week from a low of about 8%. The insanity of the pandemic market is calming down and starting to normalize showing we are not in a bubble market.

    According to a recent report from Black Knight, the annual rate of home price growth hit 14.8%. The top five markets with the biggest growth are (1) Austin at 24.9%, (2) Phoenix at 24.4%, (3) Riverside at 22.3%, (4) Seattle at 20.8%, and (5) Sacramento at 20.8%. These levels of appreciation are not sustainable and are nearing the tipping point where affordability issues will slow the appreciation.

    Inventory:

    Active single-family listings increased again by about 2,500 to nearly 330,000. Inventory is up 7% from the April 30 bottom but remains 53% lower than this time last year. There still are more buyers than sellers.

    Three weeks ago, just over 29,500 listings sold in less than 24 hours. This week it was just over 23,000. Homes are staying active slightly longer than before.

    The AZ Market:

    For a deep dive into the Greater Phoenix market, join us on June 22 for a Cromford Market Update with Tina Tamboer. For details and registration, click here.

    58% of homes sold above asking price in May in Greater Phoenix, so far in June that number is 62%. In the past 30 days pending sales have declined by 5%, inventory is up 6%, and price reductions are up 23%. On Monday, Elliott Pollack & Company wrote a great explanation about what this means.

    He wrote: “For about 22 consecutive months, Maricopa County has led the nation in housing price appreciation. In the last year, prices are up somewhere around 20% according to several sources. The Information Market suggests that prices for May 2021 are up 43% since May 2019. And in May of this year, the median sale price of a resale home surpassed the median price of a new home, something that is rarely seen. Prices are rising due to (1) limited for-sale inventory and (2) demand as Greater Phoenix continues to see in-migration.

    So are we in a bubble? A bubble is typically driven by a surge in asset prices that is fueled by irrational behavior and disconnected from fundamentals. By that measure, what is happening in housing today is the opposite of a bubble and should help drive the economy. While the impact of the Great Recession and the collapse of the housing market is still a fresh memory, the damage to the economy was from the subprime mortgage fiasco. There is little evidence today that lending standards are anywhere near those of 2004 through 2007.  

    Some observers believe that it will be quite a while before supply overwhelms demand. The demographics of the population provide a huge tailwind for housing. The key is Millennials and those behind them. They make up the bulk of first-time homebuyers and their numbers will keep growing over the next decade.  

    The hot housing market will eventually cool as supply catches up to demand. But in no way does this runup in the market suggest that a bubble has formed similar to what we saw 15 years ago. The age of high-risk derivatives is gone as financial regulations have prevented a repeat performance. Rather this market is built on a solid foundation of a homeowner’s ability to pay a mortgage. We just need more housing.”

    Inflation:

    According to economist, Elliot Eisenberg there are two types of inflation currently impacting the US economy. Base-effect inflation measures declining prices which we had a year ago so the year-over-year numbers are large. This inflation should settle down by the end of 2021. Bottleneck inflation is based on current shortages both in supply chain and labor and shows up as month-over-month inflation. This is the inflation to watch today.

    Employment:

    After two months of missing the expected job numbers, the data suggests that the supercharged economic recovery may be a little bumpier than initially anticipated.

    “This is also a great time to remember that it is much easier to shut down an economy than it is to open one back up and we are still experiencing the pain and effects from government actions over a year ago.”

    -Elliott Pollack

    Only 559,000 jobs were added in May, 671,000 were expected, bringing the unemployment rate down to 5.8%, a year ago it was 14.8%. There are currently 8 million job openings and 9.3 million people unemployed in all categories.

    The lackluster job reports reduce pressure on the Federal Reserve to taper its $40 billion monthly mortgage-backed securities buying program. When to begin the tapering will likely be discussed at the upcoming Federal Open Market Committee meeting on June 15-16. Experts believe it will be late this year or early next year and when the tapering begins mortgage interest rates will rise.

    “The decrease in initial claims for unemployment insurance in recent weeks, the continued robust demand for workers as shown by the high level of job openings, and other data showing increasing economic activity, point to more hiring over the summer. MBA is sticking with our forecast of a 4.5% unemployment rate by the end of the year.”

    – Mike Fratantoni, senior vice president and chief economist for the MBA

    Real Estate News:

    • Offerpad may be the first major iBuyer to become profitable. In Q1 2021 Opendoor’s net loss was $270 million or nearly $13,000 per home, Zillow Offers’ net loss was $58 million or about $30,000 per home, while Offerpad’s net loss was only $233,000 or $229 per home.
    • Earlier this week the DOJ announced that it had tracked down 63.7 of the 75 Bitcoins Colonial Pipeline paid ransomware hackers, illustrating that cryptocurrency is trackable. Could this lead to an increase in legitimate, large-scale transactions – like buying real estate – using cryptocurrency? Potentially.

    Final Thoughts:

    Sam Khater, Freddie Mac’s chief economist said, “The economy is recovering remarkably fast and as pandemic restrictions continue to lift, economic growth will remain strong over the coming months. Despite the stronger economy, the housing market is experiencing a slowdown in purchase application activity due to modestly higher mortgage rates. However, it has yet to translate into a weaker home price trajectory because the shortage of inventory continues to cause pricing to remain elevated.”

    Copywrite 2021 Sarah Perkins

  • AZ Forbearance Update 6/2/2021

    In this 14 minute video, Lydia Wietsma and I discuss the latest in forbearance, delinquencies, and loan servicing. Scroll down for the summary.

    Forbearance Numbers:

    This week was week number 13 of continued improvement in the forbearance numbers and are now down to 4.18% of loans in forbearance or about 2.1 million borrowers. This is fewer than half the total amount of borrowers who were initially in a forbearance plan in May 2020 which was about 8.47% of borrowers which was way below the predicted 30% of borrowers who were expected to go into forbearance. The chart below represents last week’s data but a powerful illustration nonetheless.

    Forbearance By Stage:

    • 11.6% of borrowers are in the initial stage of forbearance and new requests dropped down to their lowest level since March 2020.
    • 82.8% of borrowers are on extension, down from previous weeks. Well over 50% of borrowers on extension have been in forbearance for over 12 months. This means that a large number of forbearance plans will be expiring soon.
    • 5.6% of borrowers are re-entries, also up from previous weeks.

    Forbearance Exits from June 1, 2020 through May 23, 2021:

    46.3% of borrowers continued making their payments, got caught up upon exit, or paid off the loan with a refinance or sale upon exit. This number has declined slightly in recent weeks.

    15% of borrowers exited their plan, still behind on their payments and without a loss mitigation plan in place. It is critical for struggling borrowers who are nearing the end of their forbearance plan to call their lender or loan servicer to discuss the options. There are options.

    Based on this info, if 15% of the 2.1 million borrowers exit forbearance who are still behind on their payments and without a loss mitigation plan, means that nationwide there would be about 315,000 borrowers who would need help upon exit. Divided by 50 states, each state would have about 6,300 borrowers without a loss mitigation plan. These are the ones who need to know their options so they do not lose their homes. And 315,000 is a far cry from the 10 million foreclosures we had nationwide during the crash.

    Delinquencies:

    In April, the national delinquency rate dropped to 4.66%. A borrower who is in forbearance and not making payments is counted in these numbers. 900,000 borrowers have gotten caught up in the past 12 months. At 1.768 million, the seriously delinquent rate remains 4x the rate from February 2020.

    Black Knight data services, which supplies much of the data we discuss, is predicting that delinquency rates will normalize to pre-pandemic levels by the end of this year.

    Please note the 1.8 million borrowers are I mentioned in the video are not the total number of borrowers delinquent but a rounded number of the total borrowers that are 90+ days late.

    Deadline – June 30, 2021:

    The deadline to enter into a forbearance plan is June 30, 2021. Time is of the essence and struggling borrowers must reach out to their lender or mortgage servicer to get started. Check out the available resources below.

    The ban on rental evictions and the foreclosure moratorium also expire on June 30, 2021. It is possible that any of these programs may be extended at any time without any warning. The CFPB proposed a foreclosure moratorium through the end of 2021, which is still being discussed.

    Servicing:

    Requests for inspections are up! Lydia received 17 inspection requests in 2 days and not all are iBuyer owned. Sometimes it is to deliver letters encouraging borrowers to call their servicers to find out about their options. A large lender is offering 0% interest on second loans for the deferred amount. The servicing companies are hiring more staff to prepare the June 30 expirations. There is a backlog of pending foreclosures due to the moratorium so we will see an increase in notices of trustee sale.

    The Market:

    Do not overprice listings. Despite a 32% year-over-year appreciation rate, the market is starting to slow a bit. Some listings are lasting days rather than hours on the market.

    Resources:

  • Greater Phoenix Real Estate Update 5/28/2021

    “Buy land, they’re not making it anymore.” ~Mark Twain

    April saw its best sales rate in 15 years and at the same time sales declined again for the third straight month. Homes are selling faster than ever before, and prices are higher than ever before; yet the signs are all there, the market is slowing – very slowly – and just starting to normalize.

    “One of the main reasons that inventory can keep falling as it has and sales overall continue to grow is precisely because of this faster market velocity. And unlike previous periods when demand for homes was high and time on market short, notably the pre-2008 housing boom, the market this time around is driven by sound fundamentals unlikely to fade anytime soon.”

    ~ Treh Manhertz, Zillow

    National Real Estate:

    Pending sales for the seven-day period ending May 16 were down 10% from four weeks prior, compared to an 8% increase during the same period in 2019. (NAR)

    In the past week, single family inventory increased by 10,000 listings or 3%. This is the biggest increase in new inventory since June of 2019. That is a three-week trend of increasing inventory and it takes three weeks to see a trend. Nationwide, during normal market cycles, inventory tends to peak around August. Expect more slow increases in inventory in the coming weeks. It will likely take years to get to normal levels.

    Last week just over 29,500 listings sold in less than 24 hours. This week it was just shy of 27,000. Homes are staying active only hours longer than in previous weeks.

    88% of homes are selling in 30 days.

    Price reductions tend to be very cyclical. Usually, by mid-May we see more people cutting their prices before they go too deep into the summer. We are just barely starting to see the seasonality now with 16.3% of listings taking a price reduction. The average is around 28%. Markets remain very hot, yet we are slowly starting to move closer to normal. Now is not the time to push the market or overprice a listing.

    New Construction:

    New home sales fluctuate more than resales month to month. It is not unusual to go positive growth, negative growth, positive growth. A more stable approach to new construction is by measuring monthly supply levels, averaged over three months. At 6.5 months builders stop building. Below 4.4 months business is good and builders are building. At 4.4 to 6.5 months, the market is fine. April’s report shows a 3-month average supply of 4.23 months.

    Housing permits, starts, and builder’s confidence levels remain strong. Affordability challenges for both buyers and builders are the root of the falling numbers. Buyers and builders are both benefitting from the low-interest rates which will not last forever.

    In order to manage labor and supply chain shortages as well as the skyrocketing costs of materials, many builders are adjusting how they work with buyers. Some builders are building spec houses to sell outright, some are waiting to go under contract once they are closer to the build start date, and some builders are going under contract without a finalized price.

    “In the short-term, inventory shortages will persist. U.S. Census Bureau data from earlier this week showed residential housing starts have started to slow due to challenges in the cost and availability of building materials.”

    ~Joel Kan, MBA’s Vice President of Economic & Industry Forecasting

    The AZ Market:

    Greater Phoenix took second place in two recent price index reports. One for losing affordability and the other for the annual appreciation rate, which is pushing 32%!

    On Monday, local housing economist Elliott Pollack wrote, “Permits in Greater Phoenix were above 3,000 for the second month in a row, bringing the year-to-date total to almost 12,000 permits. The median sales price for both resales and new homes increased to $365,000 and $370,878 respectively, narrowing the gap between resale and new home prices to just $5,878.”  

    MLS Aligned is a new showing scheduling service that is co-founded and owned by five MLS’s, including ARMLS. Due to a 12-year-old ARMLS policy that doesn’t allow vendors to also be broker members, ARMLS will not extend the contract with ShowingTime after its expiration on 1/1/2022. Zillow is both a member of ARMLS and the owner of ShowingTime. The other co-owners are Metro MLS in WI, MLSListings in Silicon Valley, RMLS in OR, and UtahRealEstate.com.

    Earlier this year Scottsdale formed a municipal committee that consists of residents, Realtors, hospitality officials, and two city council members to research and track the city’s short-term rentals. Over the past three weeks, two city employees found 1,000 short-term rental locations that are currently are in violation of contract or tax licensing requirements. Will this committee set a precedent for other cities?

    Greater Phoenix retail vacancy rates decline as 99.6% of the lost retail jobs have been recovered. Leasing activity is up 18% year over year and up 85% since the whole decline in Q2 2020.

    Greater Phoenix has recovered 73.6% of jobs lost while the US has only recovered 63.3% of jobs lost.

    Earlier this week the Case-Shiller Index released its March numbers. Nationally, March saw a 13.2% year-over-year appreciation rate. Greater Phoenix had the highest appreciation rate of 20% year over year. Economists, Wall Street, and the federal government use Case Shiller’s data on appreciation rates. The index is considered a “repeat sales index” which means that it looks at the difference in sales price from when a property is purchased and when it is sold. It is a very accurate way to monitor home prices. The downside is that it is a very slow report, these are only March’s numbers.

    Commercial Real Estate:

    Apartment complex vacancy rates are expected to hit 4.55% this year, 4.38% in 2022, and 4.18% in 2023. All of those are lower than the 20-year average and significantly lower than the 7.2% apartment vacancy rate reached in 2009.

    Corelogic recently announced that single family rents increased nationwide by 4.3% in March. The cities with the largest-double digit rental increases were Phoenix and Tucson. Renting costs more than buying!

    Lending:

    Purchase mortgage applications increased for the second time in May after a weak April with multiple declines.

    In 2020, 15% of buyers purchased homes with cash. Through mid-May 2021 that number has grown to 25%.

    A new bill has been proposed to create a new loan program similar to a VA loan that allows first responders, law enforcement, and teachers to borrow up to 100% of the acquisition price.

    Real Estate News:

    • Chlorine prices have increased by 36% year over year. New pool demand is up 20% year over year after 2020’s large increase over 2019. Expect chlorine prices to continue to climb.
    • In addition to the Georgia and Alabama Association of Realtor’s lawsuits against the CDC’s eviction moratoriums; the Florida Association of Realtors filed a lawsuit against the CDC stating that the CDC does not have the authority to be the “nation’s landlord-in-chief.” NAR supports all three lawsuits and stated, “

    “Nearly half of America’s rental housing is provided by mom-and-pop property owners who own four units or less. These providers will be hesitant to pour their sweat and savings into housing if a government entity without oversight can seize their only ability to generate income. Many have struggled for more than a year to pay their bills and maintain their properties as legally required. This future uncertainty will suppress the availability of affordable rental housing in America.”

    Final Thoughts:

    Yesterday, Elliot Eisenberg wrote, and it sums up our market beautifully, “April existing-home sales fell 2.7% M-o-M, to 5.85 million/year, the best April sales rate since 2006. That said, it was the third straight monthly decline. While low rates and remote working still boost demand, a lack of homes, especially at lower price points, vertiginous Y-o-Y price appreciation of 13% to 19% depending on how you measure, and no new meaningful growth in home construction activity are quietly taking their toll.”

    Copyright 2021 Sarah Perkins

  • This Week in (Greater Phoenix) Housing 5/24/2021

    In this 12 minute video, Amber Kovarik and I talk about supply, demand, lending, and discuss what the numbers mean and what the actual buyer experience is like versus only following general data trends. The numbers don’t always tell the whole story.

    The market is confusing right now. Inventory is increasing and demand is decreasing. Yet, 80.5% of offers being written right now are for listings with multiple offers. Over 57% of closings are closing over asking.

    The reason we watch supply and demand so closely is that they help us gauge the leading indicators, like housing permits, loan applications, number of new listings, and number of listings going pending. The Cromford Market Index is the best leading indicator available. It peaked at an insanely high number of 514 on March 14. Anything over 100 is a seller’s market and yes, I just said 514. Yesterday it was 453. What that means is it is still a super hot seller’s market. It also means that the sky-high appreciation rate is starting to slow. This is good for everyone.

    In March there were 10 buyers per listing and today there are 5 buyers per listing. Remember it only takes one buyer to sell a house.

    As people are out and about more, the personal savings rates will decline. Dr. Lawrence Yun, Chief Economist for NAR, expects “revenge spending” on more services and entertainment in the coming months which will slow some of the frenzy we have been experiencing. He also expects that bidding wars will not be commonplace in 2022.

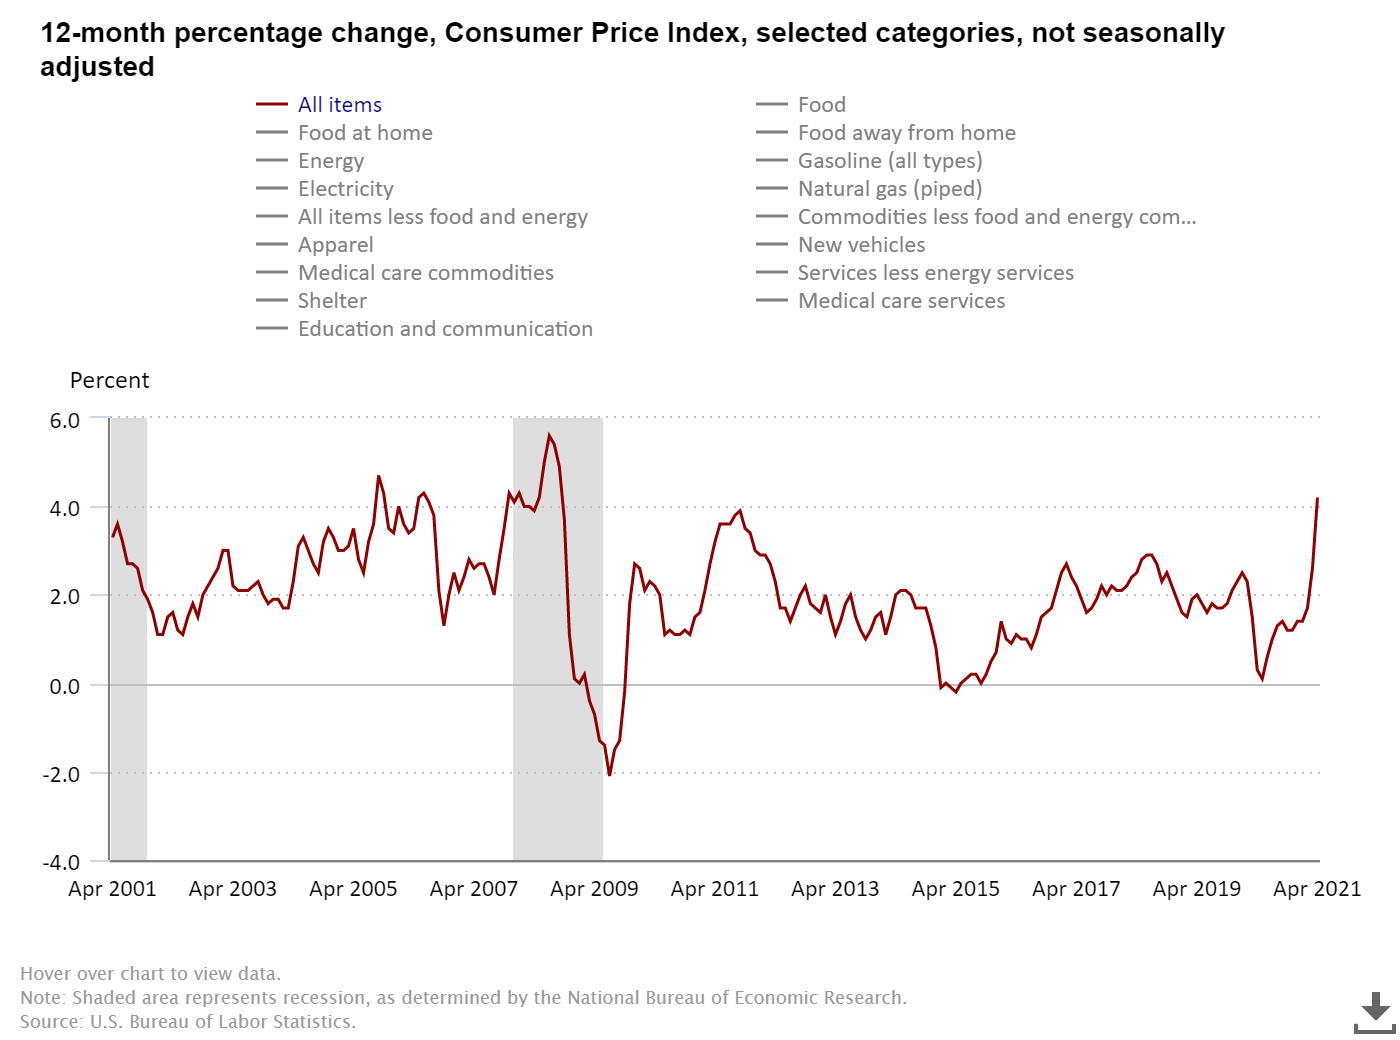
    Consumer price inflation increased by 0.8% from March to April, the largest increase since June 2009. It increased by 4.2% year over year, the highest since September of 2008. Core inflation is up 3% year over year. Experts blame supply chain challenges and last spring’s weak readings and believe this inflation is short-term and will settle down in the coming months. Housing has taken on the largest rate of inflation at 18% (nationally) year over year. Consumers call it appreciation and economists call it inflation.