Economist Dr. Peter Linneman said that the roaring (20)20’s would see continued asset appreciation, job growth, GDP growth, and other good things from a healthy economy until – the one thing that ends all healthy growth emerges – and emerge it did. He was talking about greed.
RIP Demand:
During the summer of 2021 before the ridiculous iBuyer nonsense started, the Greater Phoenix housing market was starting to normalize. The spring frenzy cooled as the last of pent-up demand was exhausted. Initial evidence of seasonality appeared but not for long.
Money was cheap so Opendoor, Zillow, and several other institutional investors were all flush with cash (AKA other people’s money) and were ready to spend. The investor frenzy commenced, and no one spent more than Opendoor and Zillow. Properties sold in minutes, far above asking. The median sales prices grew 1% to 2% a month.
Institutional buyers purchased from each other. Many properties never even hit the market. The intensity of the frenzy killed Zillow’s iBuyer business by Q4 2021. Zillow realized that Q3 2021 losses shouldn’t have been $422M during the most intense seller’s market in 16 years.
This Wall Street funded frenzy broke the emerging seasonality and pushed prices up and sidelined regular buyers. Inflation grew further and the Federal Reserve realized it wasn’t transitory. Demand peaked in early January 2022 as the increasing prices took their toll.
Mortgage rates rose and demand dropped below normal levels in early May. Prices peaked in late May. The relationship between supply and demand that had treated sellers so well for so long turned its back on the sellers. The demand finally had some supply to choose from, but the demand was now priced out.
The corporate investors and iBuyers outbid their competition, regular buyers, and now those same corporate investors and iBuyers are losing money on those investments. They forgot that in order to make a profit, their target consumer needs to be able to afford the product.
Disruptors Disrupted:
Eventually, investors expect profits or at least market sustainability. As the cost of capital increases and mortgage rates hang out around 7%, demand continues to fade further. The result, market caps decline and losses mount. Mike DelPrete shared this information on Opendoor’s Q3 results and Zillow’s final quarter of iBuying results. He also mentioned Opendoor shuttered its mortgage company, Opendoor Finance.
Inflation & Rates:
While the Federal Reserve is tasked with reducing inflation, it is limited to altering the Fed Funds rate. After artificially holding rates low for over two years, the Fed has increased rates 5 times this year which has pushed mortgage rates to around 7%. Unfortunately, despite the rate hikes, the inflation remains high.
One big cause of inflation, that isn’t lowered by increased rates, is the country’s significantly increased money supply. There is simply a lot more money flowing through the economy. According to Shadow Stats, September’s money supply was 121.6% above the pre-pandemic high. The way to reduce inflation caused by increased money supply is to remove capital from the economy.
Housing economists worry that the Fed has already over-corrected and is leading us to recession because the inflation data is a lagging indicator (tells us where we were). The Fed is expected to increase the Fed funds rate by 0.5% to 0.75% before the end of the year.
The Fed does not use the CPI to gauge inflation. Instead, it uses the Personal Consumption Expenditures (PCE). Both the CPI and PCE weigh housing (rents) heavily, the CPI at 42% and the PCE at 23%
PCE is currently up 6.2% year over year and has already started to stabilize.
PCE is a survey of businesses and adjusts over time.
A foreclosure crisis remains unlikely. The total number of residential notices of trustee sale declined by 2% from September to October. Notices of trustee sale and foreclosures remain below 2018 and 2019 levels.
Demand Isn’t Completely Dead:
In order to have a healthy real estate market, two things are required: 1) jobs and 2) inbound migration. Jobs and migration create new housing demand. While today’s demand has been sidelined by volatile mortgage rates and affordability challenges, it is important to note that the demand does exist. We saw a glimpse of it in early August went rates dropped down to 5% and we had a spike in new contracts for a few weeks. When rates went back up above 6% (and continued to rise) that demand cooled, waiting again. And we have jobs and people are still moving here.
The Greater Phoenix Economic Council (GPEC) has been busy this year bringing more businesses and jobs to Greater Phoenix. During fiscal year 2022 (10/1/21 – 9/30/22):
55 new businesses came to Greater Phoenix
10,859 new jobs
$635M+ in payroll was generated
Average high-wage salary: $76,000
Future prospects include:
214 domestic businesses
58 international businesses
A potential of 4,748 high wage jobs
Final Thoughts:
The Greater Phoenix median sales price peaked in May at $480,000. Through October the median is down to $436,000; a 9% decline in only five months. Prices will continue to decline through the end of the year. The high prices and high mortgage rates have sidelined most of today’s buyers.
Yes, it is true that this is the second largest price decline since the end of WWII. And that sounds scary, but it is ok. It will ultimately help our market normalize. The 2021 housing market was unsustainable and unhealthy.
We are going through growing pains, or shrinking pains, we need to go through in order to get back to a healthier, calmer market. It is only a matter of time.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
Founder and owner of the Keystone Law Firm, attorney Francisco Sirvent, discusses the best practices for property and asset protection in a volatile housing and economic environment. For more information visit keystonelawfirm.com or call 480-209-6942.
Topics Include:
Should a real estate investor use one LLC or multiple per number of properties?
Is there a contingency plan if the primaries have incapacity issues
Are their techniques available to aid in legal avoidance of the Federal Estate Tax?
Inflation and Interest Rates Rising! How can protect my assets now?
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
Today is all about the AZ market. Recently, Clear Title hosted a Market Update with the Cromford Report’s Tina Tamboer. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.
Before diving in, our first episode of Beyond the Transaction Podcast is available now. Our first guest was the illustrious Tina Tamboer! To listen and subscribe, click here.
To learn more about a Cromford Report membership, click here. To register for our September 14th Cromford Market Update with Tina Tamboer, click here.
July was rough, but…
Nothing lasts forever and things are getting better. There is good news we have seen a week of improvements. Remember, it takes 3 weeks to make a trend so fingers crossed this is not an anomaly. Contracts are up. Cancellations are down. New listings are not coming to market as quickly. Demand is declining at a slower rate. The increase in activity is likely due to the few rate drops we have seen lately and shows us that the demand is there waiting for the right price.
The stock market overall actually had a great July despite builders not feeling as optimistic as they were only a few months ago.
Affordability:
Affordability remains a major issue. Sellers can only sell to people who can afford to purchase the property. The same goes for landlords who can only rent to people who can afford the monthly payments. If sellers sell for less than anticipated or landlords rent for less than anticipated, they are not losing money they are experiencing a less than expected return, not a loss. The challenge to affordability has slowed the market to a crawl and it has caused fear that the situation is similar to drops we have seen in the past. The majority of the liability is held by Wall Street and private venture capital firms and not individuals.
The US Census data we have to use for income is terrible (self-admitted). Bad data leaves a lot of wiggle room for variation. The data used in the affordability index is only released annually so take this with a grain of salt. In the past, Greater Phoenix was always more affordable than the country as a whole. We used to be the cheapest big city in the country. Not anymore. In Q2 2022 our affordability index dropped from 43.9 to 22.3. The normal range is 60-75. The national level for Q2 2022 was 42.8.
Intended Use:
Primary residence transactions provide market stability, which is why real estate is less stable than it used to be. Redfin’s CEO, Glenn Kelman explained why changes are speeding up in real estate, “I just think as Wall Street owns more of Main Street, the housing market will look more like the stock market, which is extremely volatile.” He went on to explain that investors are more likely to make drastic price drops to move inventory, which complicates selling for regular homeowners competing with institutions – which represent one-third of the available national market.
Q2 2021 was the first time we saw a huge decline in primary residence home ownership in Greater Phoenix. Many were pushed out of the market by cash investors who accelerated price appreciation.
From 2015-2019 owner occupied purchases averaged 70%-76% of the market.
In 2020, owner occupied purchases averaged 80%-83% of the market.
In Q4 2021 that number dropped to 64%.
Q2 2022, through June, the number declined to 62%.
Q2 2022, through June, saw 36% of sales going to investor buyers.
Second home buyers peaked in Q4 2021 at 13.5% and declined to 12.2% in Q2 2022.
Second homes are scaling back at a normal seasonal rate. In Q2 2021 iBuyers and institutional buyers went on a purchasing rampage leaving the consumers behind. The only way to make money from consumer spending is to stay within the general confines of affordability. Essentially saying, if no one can afford to buy the product, no one will buy the product. The group that is in the best position, owner occupied buyers. Anyone who purchased 12+ months ago remains in good shape in their ability to resell. Remember, prior to the pandemic, the rule of thumb for purchasing a property is that it takes two years to recoup the investment.
Investor Flips:
A property is considered a flip if it is acquired and sold within a 6 month period. It is tougher to turn a profit on a flip property in a balanced market. The savvy local investors know how to operate in shifting markets. Flip sales peaked in March and by June dropped by over 39%.
The iBuyer model has only ever operated in seller’s markets. Launched in late 2014, Opendoor, the first iBuyer, has only ever operated in seller’s markets and is struggling to manage today’s market. Opendoor currently has 10% – 12% of today’s active listings while it only has about 3% of the current sales. Opendoor seems to be slashing prices in order to get more under contract. Offerpad is not aggressively slashing prices and therefore continues to have far more active listings than pending listings. iBuyers are still acquiring property, offers are now coming in about $100,000 under what seller expectations.
The FTC’s $62M fine against Opendoor is about 2018 and 2019 advertising. Not for today’s current acquisition and sale environment.
Contract Ratio:
The overall market is in balance now. There are some lingering hot markets but those are cooling quickly as well. There are only 3 areas with cold markets, one in Gilbert, one in Avondale, and one in south Scottsdale. These are changing quickly.
The good news is that the contract ratio is no longer dramatically plunging, it has slowed into more of a glide down. The increase in contract activity offset the inventory coming to market. Hopefully, this is the beginning of a trend! We need more data to be sure.
The dramatic rate of change is slowing. The contract ratio is a bit colder than it was in 2014, the last time we had a balanced market. There is a difference between normal and balanced markets. Normal is based on long term averages. For example, normal supply (long-term average) is about 20,000 to 25,000 available properties. Normal under contract is about 9,000. Balance is when supply and demand meet. The under-contract count matters the most. The $1M+ is still a warm market. The contract ratio for the luxury market is around 38 when it normally is around 10-15. This is likely due to the extremely low inventory count in this segment. There are currently over 700 $1M+ properties in escrow.
Emotions & the Market Cycle:
The market is moving through the regular market cycle. Sellers are going through the stages of grief and are currently in denial. The sellers need to understand this market is different. They have to fix up their properties. They missed the peak of prices, and that is ok. Once sellers arrive at acceptance then they will be able to sell their home. The severity of each part of the cycle depends on the market. If we see a continued increase in contracts then despair may be short-lived.
Days on Market:
There are 3 stages in a market shift. The first is price reductions which have increased, further details are below. The second is an increase in days on market. That has definitely increased. On May 1 the median days on market prior to contract was 7. It is now up to 25. People are upset about it. When you see an increase like that it is unnerving but historically speaking it is great. In 2007 the median days on market prior to contract reached 130 days. And that was before prices crashed! The third stage is an increase in seller concessions, which we are seeing. More details on that are below also.
Price Reductions:
Weekly price reductions have increased 746% over the past 5 months. About 23% to 26% of active supply is dropping prices weekly. The median reduction is $13,000. This does not mean prices are crashing. These are list prices coming down significantly which are down 18% since the market began shifting 5 months ago.
Sales prices are down about 4% since May. List prices are coming down which is bringing the prices down to where the buyers are. It is not crashing the market. Sales prices are not as far down as list prices.
Mortgage rates declined and even dropped down below 5% which stirred buyer interest. When rates go down monthly costs go down. Combined with declining prices, payments fell 5.7% since June.
Payments:
Our market is still not affordable. The median monthly payment for the median home selling at $450,000, with 10% down is $2,674. For that to be within the affordable range, household income needs to be at $115,000 a year. Based on the estimated Greater Phoenix median household income of $88,800, in order for payments to be affordable, they have to be $2,072 a month. The median monthly rental payment is $2,250 which is affordable for a household income of $96,000 a year.
Interest Rate Buy Down:
A great way to bring down the monthly costs for a buyer is to do an interest rate buy-down. A seller can buy down the buyer’s interest rate. There are different options for these and be sure to discuss the details with your lender as there are a lot of conditions. There is a permanent buy-down option or a 2-1 buy-down which drops the buyer’s interest rate by 2 points for the first year of the loan and 1 point for the second year of the loan. By year 3 there is the potential for more desirable interest rates. Market the monthly payment, not the asking price. Be sure to note that some of these concessions could actually be cheaper than a price reduction.
These are estimates only, talk with your lender for actual costs and details:
Seller Concessions:
In August 9.6% of all closings included a seller concession, up from 7.1% in July. The long-term average is 25%. Expect this number to increase. Offers are not as clean as they were but this is also allowing sellers to make fewer price reductions.
Weekly accepted contracts are up week over week but remain down 24.1% year over year. The percentage of seller concessions is increasing weekly. This is an unseasonal increase in weekly accepted contracts. It is likely due to interest rates and increased seller concessions. This tells us that the demand is there, but it is right below the surface, and likely will emerge when rates drop down below 5%. That is not a trend yet, but it is exciting.
Supply & Demand:
Active listings are not increasing as quickly. In July there were 1000 new active listings added a week and in August it dropped to 500 new active listings being added in a week. The decline in new listings help stabilize the market and will help the existing sellers. Not on the 2005 track anymore. During 2006-2007 there were about 3500 new active listings added a week. We are nowhere close to that. We could be reaching a normal realm though.
Demand has stopped dropping and the luxury market is showing signs of normal seasonality. WOOHOO!
Cromford Market Index (CMI):
The best tool for predicting future price appreciation trends and is available on the main page of the Cromford Report: https://cromfordreport.com/ (without a subscription)
100 is balanced and prices rise at the rate of inflation (currently 9.1% nationally, 12.3% in Greater Phoenix), below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110.
Between 90 – 110 prices roughly follow the rate of inflation.
Yesterday we were at 107.4
All-time high: 3/14/2021 at 514.9
2022 High: 2/7/2022 at 474.6
One month ago, 7/25/2022 it was 131.6
CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI. It tells us where we are.
Our market is officially in balance. When we are in balance homes appreciate at the rate of inflation. The math does not support a crash or lots of price declines. We could see a short buyers market. We won’t see a price crash but a price correction could be 10-15%. Right now, we are looking at a 4% decline so far since June.
In 2007 we had 57,000 active listings with only 4,000 under contract. That was a crash. Today we have about 19,000 active listings and 8,800 under contract, not a crash but yes to a correction.
The CMI’s decline is slowing and the curve is turning into a balanced market. Demand is declining more slowly and supply is being added more slowly, together this is creating some stabilization.
Broken down by city, the top seller markets are Fountain Hills, Paradise Valley, Scottsdale, Cave Creek, and Goodyear. The cities in balanced markets are Avondale, Phoenix, Mesa, Glendale, Peoria, and Chandler. The cities in a buyer’s market are Surprise, Tempe, Gilbert, Maricopa, Queen Creek, and Buckeye. New home communities add supply which brings them into a buyer’s market faster than the areas without new construction.
Prices:
The sale price to list price ratio is now 97.9% (from the last list price, not original) Sellers are getting about 98% of asking. A normal, balanced market is about 97%. In May it was 101.7%.
The median sales price in May was $480,000. August to date is $450,000 which is a 6.25% decline. Year over year prices are still up 11%. It is still higher than the rate of inflation. We are looking at about a 2% decline a month, not a crash.
Today the average price per square foot is ($293.79) up from July ($289.86) but down from May ($306.01). Sellers are getting more for each square foot. Year over year average price per square foot is up 17.3%. Averages change when there are fewer luxury sales. Overall we have seen a 4% drop since the peak in May, which is a 1.3% drop a month. If we stay on this trajectory, we could see another 4% decline by the end of the year. We could see a total decline of 8% this year. That is a correction, not a crash.
2005-2008 Bubble Vs. 2022
The biggest risk to all housing markets is vacant homes.
2005: HIGH VACANCY & HIGH FORECLOSURE RISK:
False demand leads to vacant properties and vacant properties lose value.
Bad financing: 100% (or more) loans, interest-only loans, no equity
Lots of speculation: no intention of occupying the property
Overbuilt for 10 years, no labor or supply shortages, built quickly
2022: HIGH EQUITY, LOW FORECLOSURE RISK, LOW VACANCY RISK
Good loans with significant down payments
Cash does not foreclose
Stable buyers
Intent to occupy
New home development struggles to keep up with demand
Wall Street’s returns may be lower than expected, rentals/short term: moderate risk of vacancy due to potential pull back on rentals
Lack of water creates a high risk of vacancy
The common denominator between the 2005 and 2022 markets = Wall Street. People always take more risk when spending other people’s money. A flood of capital in any sector often creates chaos. In 2005 investors put all of their money in lending and mortgage-backed securities (MBS). The Dodd-Frank Act prevents that from happening again. The risk for today’s investors is a lower than expected return, not a flood of foreclosures.
We do have to watch water, the outskirts are impacted the most. People will not be as interested in buying or renting if there is a water shortage. Expansion will be restricted in areas with stressed water resources. It will likely push more density in areas with a solid water supply. Water supply could impact future housing demand in shortage areas.
Distress?
Today’s desperate sellers are ibuyers. A balanced market is tough on iBuyers. Both Opendoor and Offerpad purchased far more houses than they are selling. And their model requires continuous purchasing. Both companies are seeing huge inventory increases and few sales.
Investors pushed the market further than it could bare so they are pulling back and that is why the market is crumbling now. Most price declines are leading to lower than expected prices but owners are not losing money.
In July there were 238 notices of trustee sale (pre-foreclosure) recorded. In July 2019 there were 465. In 1996 there were 515. In 1996 there were more than double today’s amount and back then Gilbert was a farm. Kierland and the 101 didn’t exist. The population of Greater Phoenix was significantly lower. Foreclosures are not currently posing a big threat to the market.
Final Thoughts:
Welcome to a balanced market. We are currently in stage 3 of the market shift, an increase in seller concessions. We will likely stay here for a while. It is important to set clear expectations with your home buyers and sellers. While the days of the runaway seller’s market are long gone, today’s sellers are not desperate (aside from iBuyers) and will not sell if they do not have to. We are working our way through the chaos and a stable market may actually be in sight.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
After 8 years of wanting to go, this year I finally got to go to an Inman Connect conference. Earlier this month, I joined 3,000 other real estate professionals at the Aria in Las Vegas to talk about real estate. It was awesome! This is my summary from 36 pages of notes.
Major Themes:
Customer service: this is a relationship business
Focus moves from growth to profitability
Increase efficiencies, streamline systems
Reduce expenses
The ultimate goal is to be efficient and transparent.
Profitability:
Sustained unprofitability was accepted 2 years ago and now it is a liability. Cash is still king. There are real estate tech companies that are hemorrhaging huge amounts of money, some have a longer runway than others. Opendoor can weather quarterly losses (Q3 will be brutal) and the FTC $62M fine for now, with roughly $2.5B in cash, it has months of operating costs covered.
A profitable business allows for continued growth during tougher markets, not just survival.
Big tech and start-ups are looking to continue growing and many of these companies are looking for a portion of Realtor commissions to fund that growth. Opendoor does so by lowering co-broke offered. Zillow and Realtor.com do so with leads, Compass plans to adjust up its splits to become more profitable by “improving economics with agents.”
Profitability is a big struggle for many brokers. How do they attract talent by offering great tools and resources along with competitive splits? The answer, is they don’t. It isn’t possible. The race to the bottom is over and there are no winners.
Brokerages are able to increase profitability by increasing headcount, and productive headcount. For example, not only does eXp’s model has lower overhead, it has grown substantially in agent headcount.
Big tech and the overall market have stopped trying to eliminate the Realtor and have realized that technology doesn’t sell houses, agents sell houses. The technology enables them to scale. With the understanding that agents are central to the transaction, businesses are coming after commissions, which in 2021 were $20B higher than in 2019 due to more sales and increased sales price.
What happens to these models if the DOJ’s suit against Realtor commissions finds on the side of the plaintiffs? What happens if buy-side commission is reduced or the requirement eliminated?
Zillow’s recent partnership with Opendoor brings seller leads back into Zillow’s offerings, a strategic plan given today’s uncertainty.
Real Estate Volatility:
Real estate is less stable than it used to be. Redfin’s CEO, Glenn Kelman explained why changes are speeding up in real estate, “I just think as Wall Street owns more of Main Street, the housing market will look more like the stock market, which is extremely volatile.” He went on to explain that investors are more likely to make drastic price drops to move inventory, which complicates selling for regular homeowners competing with institutions – which represent one-third of the available market.
The Consumer:
Derek Thompson, a journalist with the Atlantic, explained what people want. He said, “we have a deep bias for the familiar.” Meaning that while people think they want novelty and newness, they also want at least a hint of something similar to what they already know and love. He said that we stop listening to new music when we are 33 years old because he like what we like. And often what we like is based on what we see regularly. The more often we see it, the more we like it. People want surprising yet familiar. This is why anything too novel is rejected.
Industry Changes:
Expect a significant increase in mergers and acquisitions across the industry. Expect outside businesses to enter through acquisitions. Expect the brokerage model to shift and to see an increase in splits. Gross broker revenue has declined from 22% to 11% today.
Final Thoughts:
The real estate industry is fiercely competitive and the best of the best shared their “secrets.” There were power buyers, iBuyers, and investors. There were also attorneys and venture capitalists. There were machines that “hand-write” notes. There were CRM and lead generation companies. Photography. Virtual assistants and high-end print marketing. There were mortgage and title companies and a lot of top-producing Realtors. It was an exciting and exhausting 3 days. I am thrilled I got to go.
A special Thank You to Dane Briggs and Clear Title for sending me to represent the company.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
For the 4th Time, Clear Title Agency of Arizona has been recognized as one of America’s fastest-growing companies on the Inc. 5000 list
Phoenix AZ, August 17, 2022 – Inc. has revealed that Clear Title Agency of Arizona has ranked No. 4,059, with three-year revenue growth of 118%. The annual Inc. 5000 list is the most prestigious ranking of fastest-growing private companies in America.
The companies on the 2022 Inc. 5000 have not only been successful, but have also demonstrated resilience amid supply chain woes, labor shortages, and the ongoing impact of Covid-19.
“This recognition is a direct result of our team’s ability to consistently provide best-in-class title and escrow services,” said Bart Patterson, Chief Executive Officer of Clear Title Agency of Arizona. “The work done by our team makes a real difference to those in our community that are buying and selling real estate. People have come to understand that when they open escrow with Clear Title, they are working with the most knowledgeable and customer focused team in Arizona.”
Complete results of the Inc. 5000, including company profiles and an interactive database that can be sorted by industry, region, and other criteria, can be found at www.inc.com/inc5000.
“The accomplishment of building one of the fastest-growing companies in the U.S., in light of recent economic roadblocks, cannot be overstated,” says Scott Omelianuk, editor-in-chief of Inc. “Inc. is thrilled to honor the companies that have established themselves through innovation, hard work, and rising to the challenges of today.”
Methodology Companies on the 2022 Inc. 5000 are ranked according to percentage revenue growth from 2018 to 2021. To qualify, companies must have been founded and generating revenue by March 31, 2018. They must be U.S.-based, privately held, for-profit, and independent—not subsidiaries or divisions of other companies—as of December 31, 2021. (Since then, some on the list may have gone public or been acquired.) The minimum revenue required for 2018 is $100,000; the minimum for 2021 is $2 million. As always, Inc. reserves the right to decline applicants for subjective reasons. Growth rates used to determine company rankings were calculated to four decimal places. The entire Inc. 5000 can be found at http://www.inc.com/inc5000.
About Clear Title Agency of Arizona Locally owned and operated, Clear Title Agency of Arizona provides full-service residential and commercial title and escrow services with multiple locations across the Valley and in Flagstaff. The company has been recognized by Inc. 5000 Fastest Growing Companies and Phoenix Business Journal’s Best Places to Work numerous times and ranks in the top 1% of all First American agents nationally. For more information, visit www.cleartitleaz.com.
About Inc. The world’s most trusted business-media brand, Inc. offers entrepreneurs the knowledge, tools, connections, and community to build great companies. Its award-winning multiplatform content reaches more than 50 million people each month across a variety of channels including websites, newsletters, social media, podcasts, and print. Its prestigious Inc. 5000 list, produced every year since 1982, analyzes company data to recognize the fastest-growing privately held businesses in the United States. The global recognition that comes with inclusion in the 5000 gives the founders of the best businesses an opportunity to engage with an exclusive community of their peers, and the credibility that helps them drive sales and recruit talent. The associated Inc. 5000 Conference & Gala is part of a highly acclaimed portfolio of bespoke events produced by Inc. For more information, visit www.inc.com.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
Today is all about the AZ market. Recently, Clear Title hosted a Market Update with the Cromford Report’s Tina Tamboer. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.
To learn more about a Cromford Report membership, click here.
To register for our August 17th Cromford Market Update with Tina Tamboer, click here.
OMG so much change!
Despite knowing that the market was going to normalize – no market lasts forever, especially not savagely unbalanced, unsustainable markets – but the speed of this change has been surprising, to say the least.
The Greater Phoenix residential real estate market has seen 15 weeks of change but in the past 4-5 weeks that change has been amplified by a lot.
What affects demand?
Population growth
Every person, whether a renter or owner, is an element of demand.
We still have population growth, but it is slowing, it is possible for population growth to happen without increasing demand, when there is household consolidation. That increases vacancies and roommates.
Relocation (inbound)
Households relocating from outside Greater Phoenix brings one excess element of demand without adding to supply.
Household formation
Population doesn’t need to grow for demand to grow if new households are forming. You can increase demand without population growth. Household formation is mostly related to affordability.
When 1 household splits into 2 (growing), one excess element of demand is created.
When 2 households merge into 1 (shrinking), one element of demand is removed.
The latest household formation data is from March. It is expected to fall in the next release.
Affordability
Employment/income – impacts household formation and affordability
Appreciation/depreciation
Appreciating home prices decrease affordability and decrease demand.
Depreciating home prices increase affordability and increase demand (eventually but not immediately)
Interest rates (can offset effects of Appreciation/Depreciation)
Lower rates increase affordability and increase borrower demand
Higher rates decrease affordability and decrease borrower demand
Over the past 4-5 weeks interest rates have been very volatile, moving from 5.3% to 5.8% and back to 5.2% in only a week. It makes it very difficult for buyers to lock in. Buyers will freeze because they are waiting for some stability, so they feel more confident locking in a rate.
Loose/tight lending practices (can offset effects of interest rates)
Loose lending practices increase demand.
Tight lending practices decrease demand.
The affordability rate was awesome right when the pandemic hit. 70% affordability. Then we dropped below normal within a year.
Many investors are only now learning that they cannot continue to push the prices up forever. Eventually, the population will need to be able to afford these prices. Not everyone can afford the properties that were flipped.
36% of homes that are currently active were bought in the past year.
25% of homes that are currently active were purchased in 2022.
Those who bought homes in 2020 or earlier are fine.
Consumer Sentiment – could the most important factor
Emotions, such as euphoria or utter despair, based on speculative opinions or unreliable forecasts can cause some home buyers to make decisions that are not in line with market indicators.
This is bringing out a lot of emotions. A lot of wealthy people are thinking about selling off their property. When people start to panic sell, more people will panic sell and create a self-fulfilling prophecy. If homeowners think the market is tanking, so they may sell at a discount because they think that is what is what they have to do so then it creates exactly what they are afraid of.
Intended Use:
Q2 2021 was the first time we saw owner occupied affidavits dipping below 70%. As of May, it was 62%. From 2015 through 2019, owner occupied purchases ranged from 70% to 76%. In May, 13% of buyers were second homeowners (slightly above normal), 20% were investors, and 5% iBuyers. The majority of the elevation is investor and iBuyer purchases.
Cash Purchases:
Not a crash. The vast majority of purchases in 2005 – 2008 included loans; only 10% of purchases were cash. Lots of risky loans. Foreclosure crises come from too many bad loans. Now investors own the properties free and clear.
Cash purchases have been growing. 30% of buyers pay cash. Cash doesn’t foreclose. We are not looking at a looming foreclosure crisis. News media is very far behind. The only way to keep up with the market is to follow exactly what is happening as it happens; ignore the noise.
Interest Rates:
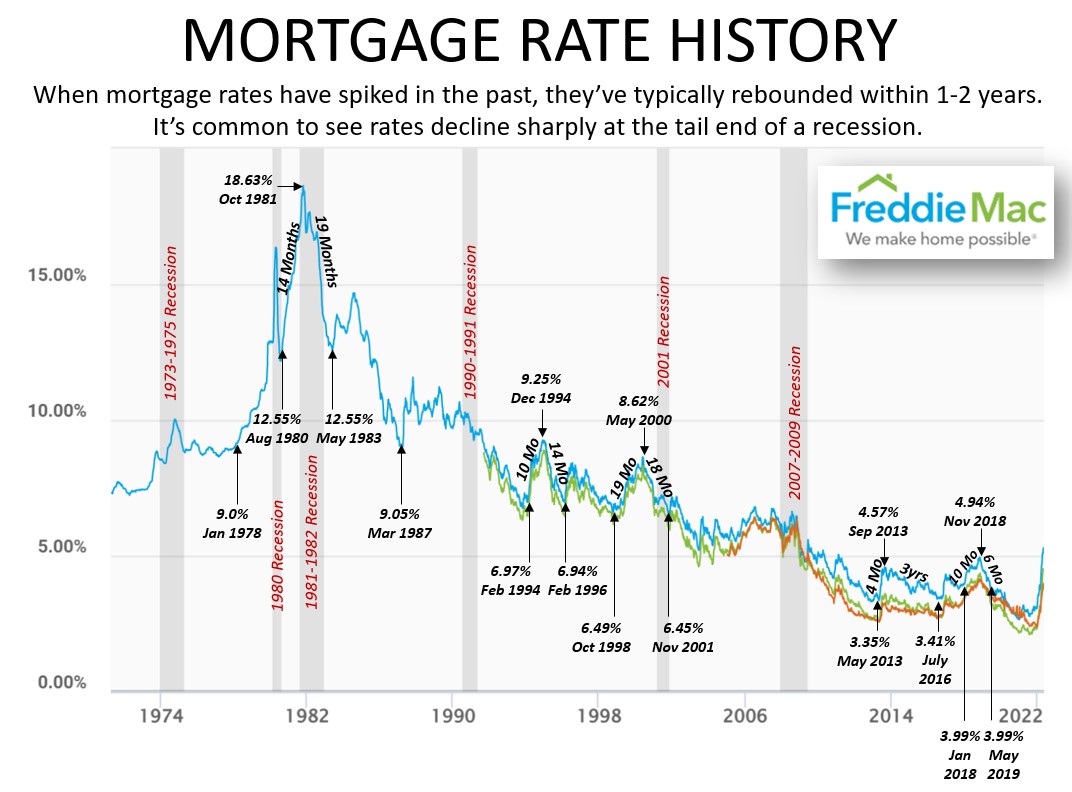
By rapidly raising interest rates to tame inflation, the Fed pulled the emergency brake on real estate. Is Chairman Powell channeling inner his inner Chairman Volker? He was the Fed’s chairman in the 80s who rapidly increased rates. At the end of both of the 1980s recessions, mortgage rates declined. Many people already believe we are in a recession, or we are going into a recession very soon. Interest rates always tend to drop sharply at the end of a recession. The ability to refinance is likely if the recession happens soon or now.
The majority of owners have payments that are much lower than today’s rents. People are not going to walk away from fixed mortgage payments that are lower than rents. They won’t, even if property values decline by 10%. Predictions planning a mass foreclosure crisis are unfounded. No homeowner wants to walk away from their equity. It makes no pragmatic sense. Why walk away to pay more in rents because prices will come down from the peak?
Interest rates don’t stay high or low forever. They always change. Nothing is forever. None of our markets are forever. The only constant is change.
Buyers primarily focus on monthly payments. The only market that matters is the market we are in right now. We can’t know what will happen but we do need to understand how we got to where we are.
15 weeks ago, mortgage interest rates surpassed 4.4%. Supply started increasing slowly. It was a very subtle turn. By April, after rates increased above 5%. Supply shot through the roof. The rate volatility has created chaos for buyers. With the lack of stability buyers have sidelined themselves.
Also, about 15 weeks ago we saw a big stock market drop. Anything that is Wall Street based is impacted. Wall Street funded institutions started pulling out of escrows. Similar to what happened at the onset of Covid. Corporations act more slowly. They stopped writing contracts. How long will Wall Street stay on the sidelines? We do not know.
Contract Ratio:
Welcome to balance. Unfortunately, it comes with a high interest rate. Buyer’s markets are loser’s markets. Seller’s markets are winner’s markets. Buyer’s markets have fewer buyers.
Seller’s markets are a dump your junk market. Everything sells in extreme seller’s markets.
Buyer’s markets are great for buyers that need more help. We will see more down payment assistance, lower down payments, first time buyer programs, FHA loans, etc. This is great for buyers who need a little help getting into a home.
The contract ratio looks at how many homes are under contract relative to how many are on the market. And it moves faster than the Cromford Market Index (CMI). It is not seasonally adjusted, and the ups and downs are more visible. On June 2 the market was still in a frenzy. By July 11 the market was warm. A warm market is a balanced market.
15 weeks ago, the contract ratio was 249, last week it was 53.2. A contract ratio of 30 – 60 is considered balanced, above 60 is hot, above 100 is a frenzy. Below 20 is a cold market. We have been living in a frenzy for 1.5 years. It is not normal to have more under contract than what is available on the market.
Are we at normal supply yet? That is a very typical question that isn’t easy to answer. Inventory counts are not that far from 2018-2019 counts. 2014 was the last balanced market we had. There were 20-25K properties on the market in 2014. A balanced market is when the number of available listings and the number of properties under contract correlate.
With a contract ratio of 53 the market is in the warm stage, balance. The contract ratio is lower than 2018 and 2019. It isn’t about the supply number it is about how many are in escrow. We should have between 10-11K in escrow for July. But only 7700 are in escrow so we are moving towards a buyer’s are market.
Everything listed over $400K is in balance.
Days on market prior to contract is now at 17 days or 3-4 weeks. Expect it to continue to slow. For any new listings, prepare sellers for 4 weeks of active status. Expect price reductions and seller concessions. There are 143.9% more listings on the market this year than there were last year. The $400K-$1M price range has had the biggest increase in available supply.
The Market Cycle:
The market is cyclical. There are different emotions associated with the different stages of a cycle. Speed up the process and the emotions gain intensity. Capitulation is the action of surrendering or ceasing to resist an opponent or demand.
Price Reductions:
The first indicator of a balanced market is an increase in price reductions. The first wave of reductions makes a difference, but after multiple reductions the price drops don’t matter as much. Sellers have to do more to get their houses sold.
Price reductions have increased by 496% in 15 weeks. The overall median price reduction amount is $15,000.
Listings under $200K had a $10,000 median reduction
Listings at $200K – $400K had a $10,000 median reduction
Listings at $400K – $800K had a $15,000 median reduction
Listings at $800K – $1M had a $25,000 median reduction
Listings at $1M – $2M had a $50,000 median reduction
Listings at $2M – $3M had a $100,000 median reduction
Listings over $3M had a $152,500 median reduction
Interest Rate Buy-Downs:
As the institutions have pulled back sellers have to focus on traditional buyers. The median sales price is slightly down from $469,000 (May) to $459,000 (July). But the payments are about the same because the interst rates are keeping the payments high. Price reductions don’t have the same impact when rates are going up.
December’s interest rates and median price worked for the median annual household income of $88,000. They do not today with higher rates and higher sales prices.
The median monthly payment for the median house is $2,745. The median rental rate for the same median house is $2,295. We have to beat rent prices to make buying desirable. In order to do that we have to pull out an old tool that hasn’t been used in 10 years.
The interest rate buy-down. A seller can buy down the buyer’s interest rate. There are different options for these and be sure to discuss the details with your lender. There is a permanent buy down option or a 2-1 buy down which drops the buyer’s interest rate by 2 points for the first year of the loan and 1 point for the second year of the loan. By year 3 there is the potential of more desirable interest rates. Market the monthly payment, not the asking price. Explain what this means to buyers. Do something different than the competition. Advertise something different. Get creative.
This is an estimate only, talk with your lender for actual costs and details:
Scenario 1:
Based on the July 9 median price of $457,000 at a 5.3% interest rate the estimated PITI is $2,733, if a seller does the median price reduction of $15,000 it will save the buyer about $86 a month.
Scenario 2:
A permanent buy-down may cost around 3% of the loan amount, assuming a purchase price of $457,000 at 5.3% and a 10% down payment, a permanent buy-down of 1% could cost the seller $12,339. A 4.3% interest rate would save the buyer $248 a month.
Scenario 3:
A 2-1 buy down may cost around 2.2% of the loan. Assuming a purchase price of $457,000 at 5.3% and a 10% down payment, a 2-1 buy down could cost the seller $9,048. The 3.3% interest rate the first year would save the buyer $481 a month. A 4.3% interest rate the second year would save the buyer $248 a month.
If a seller is willing to give up the money in a price reduction, the seller may be willing to pay for the buy-down option instead.
Supply:
For sale and rental inventory is up!
The MLS rental supply is up 111% since September 2021.
The MLS rental supply is up 51% since January.
One investor increased the rental inventory by 12% in only 3 days.
Always check rental supply and rates. More people are renting, and we are seeing more roommate situations. So far in July, 37% of leases closed below asking. Last year it was only 22%.
Homes for sale on the MLS increased by 220% in 15 weeks.
Homes for sale on the MLS increased by 144% year over year.
Most price points have more competition.
Sellers are rushing to sell to get the peak price, but we are already past the peak. Weekly new listings are outpacing every year since 2000 except 2006 and 2007.
Investors and flip models are driving many of the newest listings. This is unusual.
25% of active listings were purchased since January.
11% of active listings were purchased in the second half of 2021.
36% of active listings were purchased in the past 12 months.
52% of all active listings are vacant. Not normal.
13% of active listings are new builds.
12% of active listings are iBuyer owned.
Owner occupied listings have an advantage. Showing a lived in house looks good. This is not your as-is market. This is the best of the best of the market. ibuyers are still buying homes right now. They are not positioned to hold properties.
Demand:
It is always important to watch new listings (supply) and new contracts (demand). When the market shifts there is always a change in either supply or demand. Buyer demand has fallen off a cliff, which ultimately was the intention of the Federal Reserve. 40% of inflation is housing.
5 weeks ago demand took a dive. Prior to that, in June, we were ok, hanging around normal-ish demand. And when the first institutional buyers not only stopped buying but cancelled existing contracts, demand tanked. Combine that with the interest rate fluctuations, most traditional buyers have been sidelined. We need to get more buyers into the market. Teach awareness of ways to make payments better.
15 weeks ago was a great market for sellers. And now there are fewer properties under contract than there were in 2014, our last balanced market. Based on the trends it is not going to get better before the end of the year.
Greater Phoenix’s weekly accepted contracts are trending lower than any week of 2021, aside from the very last week of the year. Listings under contract are down nearly 26% year over year.
The one sector that has not been crushed by fluctuating interest rates are homes listed at $3M and up. Typically, this market is not as rate sensitive, but it does tend to be impacted by stock market fluctuations. At this point, we haven’t seen the impact of the falling stock market, but we may still.
Properties falling out of escrow is increasing. It isn’t super high but is an important number to watch. Canceled listings is increasing rapidly, 2021 had very few cancellations. Despite the increase, the cancellations are not enough to significantly slow the increase of supply. Expired listings are also increasing rapidly.
Cromford Market Index (CMI):
The best tool for predicting future price appreciation trends and is available on the main page of the Cromford Report: https://cromfordreport.com/ (without a subscription)
100 is balanced and prices rise at the rate of inflation (currently 9.1% nationally, 12.3% in Greater Phoenix), below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110.
Between 90 – 110 prices roughly follow the rate of inflation.
Yesterday we were at 139.1
All time high: 3/14/2021 at 514.9
2022 High: 2/7/2022 at 474.6
One month ago, 6/20/2022 it was 210.2
CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI. It tells us where we are.
There is no number that defines normal. It is about the relationship between supply and demand. When the numbers for supply and demand are the same, the market is in balance.
Property value is declining while rate of appreciation is still positive. Values are declining but the seller (as long as they owned 1 year or more) won’t lose money. To lose money on a house a homeowner has to sell for less than they paid. Losing money if they are selling with in a 6 month period. Historically it took about 2 years of ownership before purchasing costs are recovered.
It is mostly buy and hold investors losing money. They are only getting slightly less than expected but a large scale. Regular owners are in really good shape. Watch what was actually invested in the property.
Supply is rising faster than demand is dropping. Month over month prices were flat from May to June and will decline from June to July. We are getting close to year over year declines but supply has to be bigger than demand for year over year prices to drop.
In 2007 it was builders and homeowners who couldn’t afford their payments who listed their homes and spiked inventory. Today’s homeowners are credit worthy, have great interest rates, and can afford their payments. They are not flooding the market with listings. Investors are listing property. Many investors paid cash, which does not foreclose.
Prices:
Sales prices represent what the market was like 4-6 weeks ago. In July there has been a sharp median sales price decline. The year over year appreciation rate in June was 19% up. So far the year over year appreciation rate is only 13% up. This is a bigger decline than normal. It usually drops off the second half of the year. Expect each month to have a smaller and smaller year over year appreciation rate.
Sale Price to List Price Ratio:
As of July 10, nearly 37% of listings closed over asking for a median of $10,000 above. Both the amount and percentage are dropping and will likely be down to 2%-3% of sales close for over asking in August.
June ended with a sale price to list price ratio of 100.0%. It is coming down now. Do not expect full price offers in July. Currently, the rate is 99.3% A decent seller’s market often sees a 98%-99% ratio. A balanced market has a ratio around 97%.
Seller Concessions:
25-28% of closings with concessions is normal. We are up to about 5.5% now. This is the third stage of a shift. First days on market increase, second price reductions increase. Third, seller concessions increase. Expect this number to continue to grow.
Distress? Nope!
Today’s desperate sellers are ibuyers. A balanced market is tough on iBuyers. Both Opendoor and Offerpad purchased far more houses than they are selling. And their model requires continuous purchasing. Both companies are seeing huge inventory increases and few sales.
Investors pushed the market further than it could bare so they are pulling back and that is why the market is crumbling now. Most price declines are leading to lower than expected prices but owners are not losing money.
Mortgage credit availability will not increase anytime soon. Most lenders believe that people will be refinancing in the next 3 years. It is tough for investors to want to increase credit because they make all of their money in the first 3 years and the lenders know people will refinance as soon as rates decline.
Not seeing a lot of pre-foreclosures or foreclosures, we are still running below 2019 numbers. A notice of trustee sale is a pre-foreclosure. A homeowner is given 90 days notice. The current median days on market before a contract is 17 days.
Final Thoughts:
Buying is fun again. All month over month metrics are down. This can be scary for the industry yet it is necessary for the market. The severity of the previous year’s imbalance is unsustainable.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
Sellers have less power than they did only 6 weeks ago. The market is very different than it was recently. It is not catastrophically bad, but it is far trickier than it was.
National Real Estate:
Available single family inventory increased to 491,000 or by 3.25% two weeks ago, a 31% year over year increase and 60% up from the bottom in early March. Based on the steepness of the increases, there are no signs of slowing.
There was an increase in new listings during the week of the 4th of July, a first in over seven years.
31.5% of active listings in the largest metros reduced their price in June. Boise had the highest rate of reductions at 62%. For the city specific price reductions, click here.
About 60,000 purchase contracts were canceled in June, or about 14.9% of all homes that went under contract during the month.
More than 50% of builders also saw an increase in contract cancellations in June.
Purchase loan rate locks (a way to measure demand) were down 10.8% from May to June and down 22.7% in Q2 2022.
81% said the economy is on the wrong track, an all-time high.
20% said it was a good time to buy, an increase from May’s all-time low of 17%.
26% said it was a bad time to sell, an increase from May’s 19%.
27% expect prices to decline in the next 12 months, an increase from May’s 24%.
Real Estate News:
One of the previously thrown out commission lawsuits against NAR and others, which seeks class action status, has been amended and is back in court. The suit alleges price fixing on commissions damages buyers.
Due to the 9.1% inflation rate (12.3% in Phoenix) the Fed could raise rates by up to one full percentage point.
Final Thoughts:
In Tom Ruff’s June STAT report, he wrote about a recent article that accurately describes our current situation. He wrote:
“As “affordability issues take their toll”, it has become much more difficult for traditional buyers, particularly first-time buyers, to purchase a home. In the link just provided, a report done by First American Financial Corporation lists Phoenix as the fifth city in the country where affordability has declined the most year-over-year at 56.1%. Charlotte, North Carolina, led the nation at 62.5%. In the report, Mark Fleming, Chief Economist at First American, reiterates what we already discussed, ‘The pandemic-driven supply and demand imbalance that fueled historically strong house price appreciation is coming to an end as the housing market rebalances to a new normal.’”
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
It happened. The residential real estate market was going so fast that the only way to slow it down was to pull the emergency brake. And boy, was that emergency brake pulled. It threw the market into chaos but this chaos won’t last long. It may feel as though we are spinning out of control. It is all in an effort to find normal.
Normal is not exciting. It is rather boring. And change is scary. But normal isn’t exhausting. Normal is healthy and sustainable. But we aren’t there yet.
We are in the chaos. Inventory is up, price reductions are up, and consumer sentiment is down.
National Real Estate:
Supply of unsold single family homes in the US increased by 5.6% last week, up to 396,000. We probably have 12 more weeks of climbing inventory before we see a peak. Inventory is up 16% year over year and is up 22.3% in the past four weeks.
Price reductions continue to increase. Two weeks ago, we saw the largest weekly increase in price reductions and last week’s increase was even bigger. Now 25.5% of homes on the market are taking price cuts. That is a 1.4% increase, week over week, which is significant. We will probably be at a normal level of price reductions (30%) in July. Based on this trajectory, we could see above normal price reductions by the fall.
At 23%, immediate sales continue to decline, despite falling more slowly than expected. Expect this to keep dropping and to see more inventory, longer market time, and fewer bidding wars as we go deeper into the year.
Fannie Mae’s June forecast now predicts a 13.5% decline in total sales this year due to increased mortgage interest rates and another decline of 11.2% next year due to the Fed’s rate hikes which Fannie Mae believes will push us into a recession in 2023.
According to Redfin, luxury home (top 5% priciest homes in a market) sales declined by 18% year over year through the end of April. Non-luxury home sales declined by 5.4% over the same timeframe.
Consumer Sentiment:
The latest news of unexpected higher inflation which caused Wall Street to freak out and fall into a bear market and drove the Fed to increase rates by 0.75% instead of the expected 0.50% scared a lot of people. All of that happened in 4 days. And add that to the uncertainty with the war in Ukraine, gas prices, and still rising mortgage rates; people are nervous. This is why consumer sentiment is so important. If enough people freak out, it can stop the market, even when things aren’t as bad as they believe.
The most important thing right now is to not overprice listings. The perception with all of these price reductions is that prices are going down. That isn’t the case at all. The current year over year appreciation rates are about 15% nationally and 20% locally. As you know, sellers want the moon right now and many still believe they can have it. But as more and more listings drop their prices, buyers will pull back more waiting to see how much lower they will go which will further soften the market.
June’s preliminary Consumer Sentiment level dropped 14% from May to 50.2 reaching its lowest recorded value. Increased gas prices are the biggest cause. Gas prices are up 65 cents nationally since May. All consumers are feeling pitched. Fluctuations in interest rates impacts that housing sector more than any other sector.
Rates, Inflation, and the Fed:
Housing makes up about 40% of costs in the CPI so the huge appreciation rates of the past 2 years is considered the primary cause of inflation. When inflation increased in May, the Federal Reserve increased rates by 0.75 of a point, the largest increase since 1994. More rate hikes are likely ahead, as the Fed tries to cool off the U.S. economy without causing a recession.
Dr. Lawrence Yun, NAR’s Chief Economist, said, “The Federal Reserve set a big increase in interest rates and means several more rounds of rate hikes are on the way in upcoming months. So far, the short-term fed funds rate that the Fed directly controls has risen by 175 basis points. But the 30-year fixed rate mortgage has risen even more, by nearly 300 basis points. On the same $300,000 mortgage, the monthly payment has risen from $1265 in December to $1800 today. That’s painful and, consequently, will shrink the buyer pool.”
The AZ Market:
While the Greater Phoenix housing market follows the same trends of the national housing market, it does so first (currently running 4-6 weeks ahead versus the usual 6-9 months ahead). The cooling trend emerged 10-12 weeks ago locally, while nationally the trend became more apparent in April. Not only does the Greater Phoenix market run ahead of the national market, it has bigger swings. Our highs are higher and lows are lower. For example, over the past three months, the national single family inventory has increased by 64% and during the same time period, Greater Phoenix’s single family inventory increased by 148%.
Total active listing inventory is up 47% in the past month.
The median number of days prior to contract is now 11, up 4 days from last month.
Price reductions are up 471% since the beginning of the year.
The current median sales price is $475,000.
Sales prices are likely peaking now and pending sales prices peaked the second week of May. This means monthly price appreciation will likely go flat in the coming weeks (if not days).
Join us for our next Cromford Market Update with Tina Tamboer on July 13. For details and registration, click here.
Short term rental bookings increased by 2.6% year over year and yet occupancy rates declined by 8.6% in May. This is due to a 24.7% (57,000 properties) increase in Airbnb and VRBO listings.
Final Thoughts:
The imbalance in the market was caused by very low supply, not unusually high demand. This is the fundamental difference between the 2005 market and the 2021 market. In a market with already falling demand, drastically rising mortgage interest rates has pushed our current demand off a cliff.
The data line to watch is active inventory. If inventory continues to climb at its current rate, we will be in a buyer’s market soon. However, at roughly 13,000 active listings, if inventory slows or flattens we will stay in a weak seller’s market.
We are once again, in uncharted territory. Hopefully, the chaos clears soon.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
Today is all about the AZ market. Recently, Clear Title hosted a Market Update with the Cromford Report’s Tina Tamboer. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.
To learn more about a Cromford Report membership, click here.
A lot is happening in housing and there is no reason to panic. The market of the past two years is unsustainable. In order to get to the calm of a more balanced market, we have to go through the chaos of change.
In order to really see what is going on in Greater Phoenix real estate, we have to take a granular look at exactly what is happening right now.
Interest Rates:
Interest rates are never low or high forever. Sometimes they come down as fast as they go up. In 2018, it took 10 months to go up and 6 months to come down.
The speed of movement hasn’t been like this since the 1980s. The speed is comparable to the 80s but the actual rates are very different.
Look at the changes during a recession. What do interest rates do during recessions? At the end of all of the past recessions, interest rates dropped. If we are going into a recession, then we will likely see rate drops towards the end. Aside from 2008, most recessions last only about a year.
In time rates will likely come down. Remember people buy payments. They are watching payments. Potential buyers should buy now, start building equity, and refinance later when rates drop. Homeownership is the greatest creator of wealth in the US, this is true regardless of interest rates.
Active Supply:
This is the chaos. Active inventory is up 86.2% year over year and up 108% in 10 weeks. Listings are rising and demand is down, causing inventory to grow even faster.
New listings are up 11.2% year over year. We are just coming in over 2021 but not higher than 2005. Before the crash of 2008, we had a ton of new listings. This does not mean the market will crash. We are at an inflection point though. Are the numbers turning seasonal or will there be an acceleration of new listings? It is important to watch these numbers.
Accepted Contracts:
There is always a drop in accepted contracts over Memorial Day weekend. Newly accepted contracts were down 11.3% year over year. There will be another drop off for the 4th of July weekend. Expect the decline to continue. The accepted contracts are matching the pace of 2019. This is another metric to track.
Pending listings have declined in each of the past four months. 10 weeks ago, listings under contract started coming in lower than in 2021. Now that count is 15.9% below last year’s count. About a year ago the market started normalizing when Zillow and Opendoor both went on a purchasing rampage, creating the frenzy of the second half of 2021. That will not happen again this year.
29% of buyers in April paid cash. Investors are not buying everything.
Supply & Demand Changes:
Overall, active supply is up 92.4% year over year and at the same time listings under contract is down 15.9% year over year. Buyers are seeing inventory rise after two years of rejection. Now is the time to prepare your sellers for what is happening right now. Today’s market is very different from the market of only a few months ago.
$300,000 – $400,000 listings
Active supply up 23% year over year
Active supply up 84% in 10 weeks
Listings under contract down 45% year over year
Listings under contract down 36% in 16 weeks
$400,000 – $1.5M listings
Active supply up 174% year over year
Active supply up 105% in 7 weeks
Listings under contract up 29% year over year
Demand is still quite high but there are way more listings coming on the market, many sellers do not want to miss the top of the market. If it were following seasonal patterns, demand will flatten.
$1.5 – $3M listings
Active supply is still low compared to previous years
Active supply up 38% year over year
Active supply up 112% in 10 weeks
Listings under contract up 6% year over year but on a steep decline, will fall below 2021’s numbers in the coming weeks. If following normal seasonality, this will decline through the end of the year.
Over $3M listings
Active supply up 20% year over year
Active supply up 34% in 12 weeks
Listings under contract up 19% year over year
Flip investors, private landlords, and first time home buyers tend to buy below the median. The current median is $480,000. There are not very many listings available below $480,000. This has impacted first time buyers and investors on a budget, there is both a lot of competition and profits are lower for flippers in the lower price ranges.
If this market slows down enough, down payment assistance programs will likely increase. There is aid available but only when demand is low enough will sellers accept offers from buyers utilizing the programs. This is not seasonal.
Price Reductions:
Price reductions are often the first indicator of a market shift. When buyers believe they can afford the asking price is when they will come into the market.
$300,000 – $400,000 listings
Price reductions are up 208% in 10 weeks
Median amount reduced: $10,000
$400,000 – $1.5M listings
Price reductions are up 302% in 10 weeks. In the same 10 week period listings under contract are down and inventory is up. Sellers need to adjust accordingly.
Median amount reduced
$400K – $500K: $10,000
$500K – $600K: $10,000
$600K – $800K: $12,000
$800K – $1M: $25,000
$1M – $1.5M: $50,000
Over $1.5M listings
Price reductions are up 172% in 10 weeks.
Median amount reduced
$1.5M – $2M: $77,500
$2M – $3M: $136,000
Over $3M: $187,500
Days on Market:
Behind price reductions, the second indicator of a market shift is an increase in average days on market prior to contract. For most of the year, listings were on the market for 7 days prior to accepting a contract. In May, that number hit 9 days and by the end of May it was up to 11 days. May’s increases were quick and with more inventory coming to market, this number will continue to increase. Sellers will need to adjust their expectations from an offer coming in one week to two weeks.
Contract Ratio:
Housing is no longer in a frenzy. A frenzied market is when there are more properties under contract than there are on the market. The contract ratio for a frenzy market is over 100. A month ago listings up to $2M were still in a frenzy. Each week another price range dips below frenzy level. With a contract ratio of 98.3, we are still in a very hot seller’s market. A year ago the contract ratio was 224.8. A normal contract ratio is around 85.
The decline in contract ratio is more about increased inventory than it is about decreased demand. Inventory has grown faster than demand has declined. The recent drastic declines in the contract ratio represent the chaos before the calm.
Cromford Market Index (CMI):
The best tool for predicting future price appreciation trends and is available on the main page of the Cromford Report: https://cromfordreport.com/ (without a subscription)
100 is balanced and prices rise at the rate of inflation (currently 8.6%), below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110.
Between 90 – 110 prices roughly follow the rate of inflation.
Yesterday we were at 227.6
All time high: 3/14/2021 at 514.9
2022 High: 2/7/2022 at 474.6
CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI. It tells us where we are.
There is no number that defines normal. It is about the relationship between supply and demand. When the numbers for supply and demand are the same, the market is in balance.
In 2005, the CMI dropped for 4 months before prices flattened. In the next 3 months, we will likely see a slowing in appreciation rates. Cash investors are still very strong buyers in our market. Less competition so they are offering less.
Supply is 60% below normal. Demand recently fell below normal and is now 7.5% below normal. Supply is increasing faster than demand is decreasing. When demand falls below 100, the number of transactions declines. The closer demand is to 100 or higher keeps transaction counts high. It is better for the industry and overall economy for supply to come up to meet demand versus demand dropping to meet supply.
The CMI declined at record rates over the past 8 weeks. CMI data goes back to 2000 and the last month had the fastest CMI drop on record. With this many outside influences impacting the market, it is impossible to know what will happen next. The CMI can change on a dime. There is no indication that prices will decline anytime soon but this does show weekly declines in the seller’s advantage. Now is not the time to over price a listing. We don’t have desperate sellers. They can wait and not panic sell. Worst case they keep their home and an awesome interest rate for a little longer than planned.
Sales Measures:
Sales measures tell us what happened in the past, not what is happening in the future. The media is using closed sales, past activity, to explain the market. Things are shifting so quickly right now it is impossible to predict the future past 3-4 months from now. The sales measures for the month of May are still very good. But that is not the future, it explains what the market did 30-60 days ago.
May ended with a median sales price of $480,000 and year over year annual appreciation rate of 22%. The sales price to list price ratio was 101.7% (expect this to drop in the next 4 weeks) and 54.6% of homes closed over list price. The third indicator of a shifting market is increased seller concessions (when a seller pays some of the buyer’s closing costs). Currently, seller concessions are low at 4.1% but are just starting to increase.
Flips:
Flips dropped off in April, likely due to the increased interest rates and declining demand.
Opendoor Activity:
Opendoor made its first profit in Q1 2022.
May through November 2021 Opendoor acquired 3,609 properties and sold 1,861. They acquired 94% more homes than they sold.
December 2021 through March 2022 Opendoor acquired 1,408 properties and sold 2,149. They sold 53% more than they acquired.
April 2022 Opendoor acquired 510 properties and sold 494. They acquired 3% more than they sold.
Offerpad Activity:
June through December 2021 Offerpad acquired 1,050 properties and sold 742. They acquired 29% more than they sold.
January through March 2022 Offerpad acquired 201 properties and sold 546. They sold 172% more than they acquired.
April 2022 Offerpad acquired 94 properties and sold 93. They acquired 1 more than they sold.
The iBuyers struggled to turn a profit during the largest resale year in history. The rest of the flip investors did very well. Regular, private flip investors hold properties for shorter timeframes than do the iBuyers.
Rentals:
Available rentals in the MLS is up 26% since the beginning of the year. This indicates that there are more vacant homes. Vacant homes are bad for a housing market.
4.9% of May’s closed rentals closed over list price. 53.5% closed at list price. And 41.6% closed under list price. There are no bidding wars for rentals.
Crash Versus Correction:
A crash is a big drop. A correction is a slight fix. Correction is getting back to where we would be anyway. We are experiencing a disruption. We do not know how long it will last. After the disruption, we will experience a correction. Do not expect foreclosures.
2005-2008 Bubble Vs. 2022
The biggest risk to all housing markets is vacant homes.
2005: HIGH VACANCY & HIGH FORECLOSURE RISK:
False demand leads to vacant properties and vacant properties lose value.
Bad financing: 100% (or more) loans, interest-only loans, no equity
Lots of speculation: no intention of occupying the property
Overbuilt for 10 years, no labor or supply shortages, built quickly
2022: HIGH EQUITY, LOW FORECLOSURE RISK, LOW VACANCY RISK
Good loans with significant down payments
Cash does not foreclose
Stable buyers
Intent to occupy
New home development struggles to keep up with demand
Wall Street’s returns may be lower than expected, rentals/short term: moderate risk of vacancy due to potential pull back on rentals
Lack of water creates a high risk of vacancy
The common denominator between the 2005 and 2022 markets is Wall Street. People always take more risk when spending other people’s money. A flood of capital in any sector often creates chaos. In 2005 investors put all of their money in lending and mortgage-backed securities (MBS). The Dodd-Frank Act prevents that from happening again. The risk for today’s investors is a lower than expected return, not a flood of foreclosures.
There is risk with short-term rentals and second homes. If the investors cannot rent the property, they will sell. If short-term rental owners can’t rent to vacationers, they will go to long-term rentals.
We do have to watch water, the outskirts are impacted the most. People will not be as interested in buying or renting if there is a water shortage. Expansion will be restricted in areas with stressed water resources. It will likely push more density in areas with a solid water supply. Water supply could impact future housing demand in shortage areas.
Final Thoughts:
We are early in the shift. Start bracing sellers for market prices, increased days on market, and potential concessions. Do not expect to see more of the 2% month over month appreciation rates, expect to see an appreciation rate of less than 1% month over month.
The market is attempting to normalize and is doing so quickly. We have to move through the chaos to get to the calm.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.
In rapidly changing markets the best thing to do is focus on the most current data. Ignore clickbait headlines and any forecast that goes out further than three months.
It is very early in the housing market shift and no one knows what will happen. It is not market changes themselves but the speed of change that is causing the feelings of chaos. Right now, after a long run up in home prices we are going through a market disruption, where the markets behave erratically. Once the disruption settles down, we will likely enter a correction (not necessarily in all markets) as the housing market attempts to normalize. The markets of the past two years are unsustainable. Remember, a correction is not a crash.
Consumer sentiment is among the most powerful market drivers in any economic sector. When consumers are nervous, they pull back. Fear-mongering headlines do not help empower consumer sentiment. For example, Inman recently ran a headline that said, “Zombie foreclosures post 1st increase since moratorium’s end” The article mentions the 7,500 properties going through the foreclosure process in Q2. During normal times there are around 200,000 properties in pre-foreclosure, so 7,500 foreclosures is not a number to cause panic.
There are a lot of forecasts from different publications, analysts, and economists. It seems as though the analysts and economists who are not in real estate tend to predict that home prices will decline. Many of the housing analysts and housing economists say that appreciation will go flat but unlikely go negative by much if at all. I am not sure if the housing analysts either know more than the others or they do not want to give bad news to the real estate industry. I’d like to believe that it is because they know more but at this point, anything could happen.
National Real Estate:
Available single family home inventory is still rising but at a slower rate. Inventory increased 3% last week to 375,000, slower than the 5.7% week over week increase two weeks ago, or the 8% week over week increase three weeks ago. We now have more homes on the market today than we did at this time last year. Inventory is up nearly 56% from the bottom on March 7 (241,000)
Demand:
Price Reductions increased by one full percentage point week over week last week, up to 24.1%. That is the highest level of the year. Normally about 30% of homes take a price reduction before selling so last week’s rate is still below normal, but the rate of increase was steep. Price reductions typically peak in the fall before resetting around the holidays. Based on our current trajectory, we may hit 30% reductions by next month, which is back to the normal rate.
We had the fewest immediate sales this week since last winter, likely because of the holiday weekend. It is normal to have fewer new listings hit the market over Memorial Day weekend. Despite having a smaller number of immediate sales, last week’s percentage increased from two weeks ago. Before last week’s increase, we had 6 weeks of declines in immediate sales. Take it with a grain of salt, it isn’t a real increase in new listings. Expect this decline to continue next week. Last week was an anomaly. Immediate sales has been a defining aspect of this current market.
Fannie Mae predicts that new home sales will decline by 1% in 2022 and by 13% in 2023. Because the new home market is so much smaller than the resale market, it moves faster and can give us a forecast of what is to come for the resale market.
Home buyer sentiment declined for the third consecutive month. Only 17% of Americans surveyed in May said it was a good time to buy a home, breaking previous record lows of 19% seen in April and 24% in March.
Due to the decline in demand, builders are feeling pressure to drop prices and increase buyer incentives.
In April existing home sales declined for the third month in a row, down 5.9% from a year ago.
Inflation:
As announced on Friday, inflation reached a new 40 year high as CPI climbs to 8.6% in May, up from 8.3% in April. Experts had predicted that we peaked in March after April saw a slight decline. Gas, shelter, and food (all basic human necessities) are what drove the increase.
Real Estate News:
NAR’s appeal challenging the class certification in the Sitzer/Burnett commission lawsuit was rejected. The trial is set to being in February 2023.
Half of the people who bought a home over the past 2 years say the process made them cry.
A lawsuit against Realogy over cold calls from Coldwell Banker agents is heading to trial as a class action now that an appeals court has rejected a request for review from the brokerage giant.
Final Thoughts:
A lot is happening in housing and there is no reason to panic. The market of the past two years is unsustainable. In order to get to the calm of a more balanced market, we have to go through the chaos of change.
Sarah Perkins is an award winning account executive and has been in title sales since 2004. As the Director of Industry Research & Senior Account Executive, Sarah’s role is to bring real estate transactions to Navi Title. Sarah supports her clients by helping them navigate the ever-changing real estate space through thorough research and understanding of current trends impacting today’s home buyers and sellers.