Category: AZ Real Estate

  • Greater Phoenix Real Estate Update 4/16/2021

    Despite our fear of change, humans are quite resilient and are far more flexible than we realize. Quite often, change is good. Demand is declining and seasonality is beginning to emerge in the market. I am hearing stories about an FHA buyer who finally had a contract accepted and a seller who agreed to a few concessions. This is good news for our exhausted buyers; they need some wins too. This is how the machine is supposed to work.

    Demographics:

    The post-2008 market crash recovery was the weakest recovery in real estate history. Nationally we have been in a seller’s market since 2012, here in AZ it has been since 2014 (we had a deeper hole to climb out of than most of the country). From 2017-2020 resale closings ranged from 5,340,000 (2018) to 5,640,000 (2020); that is not a huge variation.

    There are more than 32,400,000 Americans aged 27-33. This is the largest group, in the largest generation and this is the prime time for getting married, having babies, and buying houses. Logan Mohtashami, senior economist at HousingWire says, “This is when people date, mate, and buy real estate.”

    The demand wasn’t here 10 years ago but it is here now and likely to stay elevated through the end of 2024. The combination of high demand and low inventory indicates we will stay in a strong seller’s market for years to come. The biggest problem buyers face today is declining affordability.

    New Construction:

    Builders have been underbuilding since 2009 due to the extremely slow recovery. The baselines for months of inventory for new homes is different from resale. At 6.5 months, builders stop building. At 4.4-6.4 months builders are ok as long as sales are consistent. Under 4.3 months builders are happy and building as fast as possible. Nationwide there is a 3.3 month supply of new homes. The building frenzy is warranted.

    While many are looking to builders to solve our inventory crisis and therefore aid in slowing this massive appreciation, builders will not overbuild. Builders are sellers, they want to maximize profits too. Like many of us, they too remember the pain of the crash and adjusted their business models accordingly.

    Lumber costs are the most notable, having nearly tripled in the past 12 months, but other material costs have increased also. Combine that with the labor shortages and huge demand, costs continue to rise for builders, who then push the additional costs to the buyers.

    Institutional Investors:

    Since the end of the Great Recession, institutional investors have purchased over 7M single-family homes to keep as rentals. These buyers are home rental firms, like Invitation Homes which owns about 80,000 houses in 16 markets, private equity, pension funds, sovereign wealth funds, etc.

    According to John Burns Real Estate Consulting, institutional investors are currently purchasing about 20% of all single-family homes in the US. Due to the continuously climbing rental rates in Phoenix, these buyers are purchasing about 30% of the single family supply. They pay cash and will go over the asking price in order to secure the property; something many buyers simply can’t compete with. Additionally, these properties are held longer than a typical owner stays, meaning these properties are being completely removed from the market.

    National Real Estate:

    Many industry experts predict that 2021 will have more sales than 2020 despite the low inventory. NAR predicts 6.5M resale closings, which is significantly up from 2020’s 5.64M resale closings. We do have strong demand and the market is, very slowly inching towards thinking about maybe trying to get closer to being normal, demand is not booming, which makes me doubt that 6.5M sales projection.

    Single-family active listings declined by another 3,000 listings this week so we are now down to 306,546. We may have another week or two of declines and by May, it is likely we will start to see an increase in inventory. Inventory levels are expected to stay low for years but not at these low historically low levels.
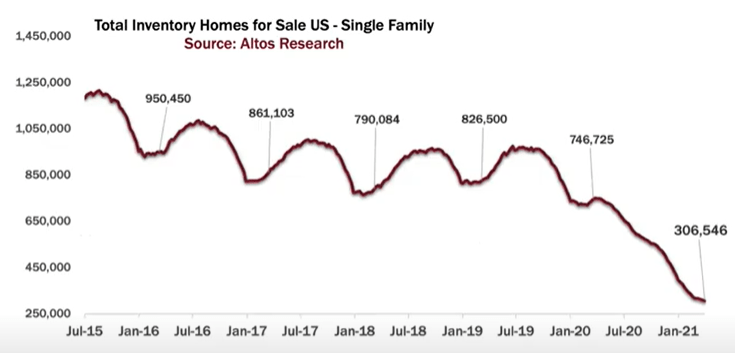
    Prices have stabilized, for the past 3 weeks, the median new listing asking price has remained at $350,000. Expect this to fall as we get later into the year. During normal cycles, more expensive homes are listed in the first half of the year.

    While prices and inventory have started to stabilize, the speed of homes going under contract has not. 38% of single-family homes went under contract within hours of listing and 70% sold in less than a week on the market.

    The AZ Market:

    The Case-Shiller Index measures residential values using a very specific set of data and guidelines and runs a couple of months behind the current market. Many large institutions, including the US Census, use it to gauge appreciation. The most recent data is from January and it shows, for 20 months straight, that Greater Phoenix has the highest appreciation rate in the country. January came in at 15.8%. More info on Case-Shiller click here and here.

    Demand is dropping, as of yesterday, it is 9.2% above normal. And inventory is increasing, it now only 77.7% below normal. Active listing supply is down over 70% from last year (during lockdown protocols). The median sales price is up over 18% year over year to $360,000.

    Remember in January 2020, when Tina Tamboer with the Cromford Report told us to expect a 10% appreciation in 2020 and it was shocking? I do. A lot has changed since then.

    Lending:

    • Many experts believe that despite rising interest rates (with the exception of the past 2 weeks) buyer demand will not dampen. In a press release from March, Fannie Mae stated that while some buyers are being pushed out of the market, an ample amount of buyers remain.
    • For the second week in a row, 30 year fixed mortgage rates declined. Despite the drop Freddie Mac expects rates to rise slowly throughout 2021.
    • While interest rate increases often make people nervous, remember the largest home purchase year in history was 2005 and rates were about 7.5%.

    Forbearance:

    The forbearance numbers saw one of their largest improvements this past week, dropping down to about 2.3 million borrowers or 4.66% of loans. That is down from 4.9% the previous week.

    “Almost 32 percent of borrowers in forbearance extensions have now exceeded the 12-month mark. In terms of performance, more than 88 percent of homeowners who have exited into deferral plans, modifications or repayment plans were current on their loans at the end of March, compared to 92 percent of all homeowners. The accelerating economic recovery in March helped more homeowners recover and become current on their mortgages, in addition to helping other homeowners with more stable financial situations exit forbearance.”

    Mike Fratantoni , MBA senior vice president and chief economist

    Policy:

    President Biden’s first-time homebuyer tax credit has evolved and was submitted to Congress on Wednesday. In the current iteration of the legislation, it is less of a tax credit and more of a down payment assistance program offering up to $25,000. Eligibility requirements include but are not limited to buyers who have not owned a house in the past 3 years, none of the borrowers’ parents may have owned a house unless they lost it due to foreclosure or short sale, income limits, and additional funds are available to groups recognized as socially disadvantaged. For more information click here.

    Real Estate News:

    • After multiple failed attempts to acquire CoreLogic, CoStar, which is heavily involved in commercial real estate, plans to acquire Homes.com for $156M as it continues to enter the residential space.
    • California Regional MLS, the country’s largest MLS with 104,000 members, has declared Saturday a business day. Some suspect it is to prevent a loophole in the Clear Cooperation Policy.
    • The SEC is warning investors about an increase in “lawsuits alleging inadequate disclosure by SPACs.” Going public via SPAC has been perceived as a cheaper, easier process than via IPO. However, in November, Harvard published a study showing that SPACs are more expensive than an IPO and investors are paying those added costs, for now.

    Final Thoughts:

    Today’s market is nothing like that of 2005 but the intensity of it feels very similar. As the market begins to cool, fear will rise, the 2008 crash wasn’t THAT long ago, right? A lot has happened in 13 years.

    That hasn’t stopped the housing fear Googling though. Searches asking, “When is the housing market going to crash?” increased by 2,450% in the past 30 days. Searches asking, “Why is the market so hot?” doubled in the past week. And searches asking “How much over asking price should I offer on a home 2021?” increased by 350% in the past week.

    Let’s spread the word, housing is, hopefully, starting to normalize which is good for everyone. Prices will continue to rise but at a slower rate.

    Copyright 2021 Sarah Perkins

  • Greater Phoenix Real Estate Update 4/9/2021

    Now, this is a headline that says it all, “Who’s Lying About The Housing Market? The housing market is heating and cooling at the same time, depending on the data in question. Who’s telling the truth?  Actually, maybe everyone…” Author, Matthew Graham explains that prices are appreciating faster than they have in 15 years, homes are selling in minutes, and bidding wars are commonplace all while demand is actually falling. Demand was THAT high and remains above normal.

    National Real Estate:

    • 36% of newly pending sales were immediate, meaning they went pending either before they hit the market or within 24 hours of going active.
    • 64% of newly pending sales were on the market for one week or less.
    • Nationwide there are only 309,883 active single-family listings available. The decline in inventory has slowed over the past 4 weeks.
    • As the market moves towards typical seasonality, it is likely that inventory will increase towards the end of April. Anything moving towards “normal” is good.
    • The supply/demand imbalance drove the 15% year over year appreciation leading to 58% of all households, or about 71.1 million, could not afford to buy the median-priced new home.
    • The median sales price last week increased to $374,000, a new all-time high. As typical seasonal cycles emerge, prices are expected to keep rising through June. More sales usually happen in the first half of the year which is why October through December 2020 had record-breaking sales.
    • The newly listed cohort asking price is flattening at $350,000 and will continue to flatten as more listings come to market and there is more competition. This is also normal for this time of year, again seasonality is good.

    The AZ Market:

    For one week only – from April 10 through April 17 – local home builder, Fulton Homes, is allowing buyers under contract to cancel and receive a full refund. They did this because of the 1 to 6+ month building delays due to supply chain shortages, lumber costs, labor shortages, etc. While yes, this benefits buyers with specific timelines but the builder is also benefitting. This will lead to more spec homes to sell allowing the builder to capitalize on the 1-3% of monthly appreciation our market is experiencing.

    The Greater Phoenix housing market and the overall economy have been a top performer throughout the pandemic. The affordable housing we have enjoyed for many years has brought much business to Arizona from more expensive cities. However, now after many months of having the highest rental appreciation in the country and among the highest sale appreciation, we are not so affordable anymore.

    On Monday, Elliott Pollack & Company wrote, “So while the local economy is performing better than any other in the country at the current time, demand for housing is pushing costs beyond the reach of some, even with low-interest rates. Housing cost is something to watch over the next couple of years with the hopes it does not detract from our competitive advantages.”

    With 5 buyers for every available listing and 18-20% year over year appreciation, this concern is very real. While demand is declining – we no longer have 8 buyers for every listing – prices continue to increase and will continue increasing for the foreseeable future.

    Lending:

    • The Data has yet to show that rising interest rates are hurting buyer demand. The current closings are with buyers who locked in at a lower rate; we may see the impact in the coming weeks. The segment to watch is the second home market because those loans just got a lot more expensive.
    • Purchase applications decreased by 4% last week from the week before. They are up 51% year over year; keep in mind that one year ago we were in the middle of the 8-week downturn in the market.
    • Sam Khater, Freddie Mac Chief Economist said, “After moving up for seven consecutive weeks, mortgage rates have dropped due to the recent, modest decline of U.S. Treasury yields. As the economy recovers, it should experience a strong rebound in the labor market. Combined, these positive signals will continue to bolster purchase demand.”

    The Economy & Employment:

    • Yesterday, economist Elliot Eisenberg wrote, “The economy continues to roar back to life. The Institute for Supply Management’s services index rose to a record high of 63.7 in March, and in the process blew away the previous high of 60.9 of 10/18. This is great news as the recovery in services has, for obvious reasons, lagged well behind the manufacturing renaissance, and that index hit 64.7 in March, its best reading in nearly 40 years!”
    • The Fannie Mae Home Price Sentiment Index reached 81.7 in March, nearly exceeding pre-pandemic numbers for the first time in a year. It is up 0.9 points year over year and up 5.2 points from February.
    • Between decreasing unemployment, increased vaccine distribution, and the latest round of stimulus checks consumers are optimistic about the economy. Doug Duncan, Fannie Mae senior vice president, and chief economist said. “Home-selling sentiment experienced positive momentum across most consumer segments – nearly reaching pre-pandemic levels and generally indicative of a strong seller’s market.”
    • About 62% of jobs lost last year have been recovered. Today, there are still about 4 million more people unemployed than in February 2020.
    • The real estate industry added 10,000 jobs in March which was a huge improvement after losing 4,500 jobs in February.

    “There’s a seismic shift going on in the U.S. economy. Fear is subsiding, and American households are sitting on a lot of cash from saved stimulus checks and other money people would normally spend on travel or going out. That’s going to support spending, especially in the services sector.”

    Beth Ann Bovino, a Ph.D. economist at S&P Global, told the Wall Street Journal.

    CFPB Proposal:

    On Monday, the CFPB proposed a ban on foreclosure starts through the end of 2021. This means that lenders and servicers could not even start the foreclosure process until January 1, 2022. Different states have different timelines for the foreclosure process. Here in AZ, the process takes 90 days so we would not see any properties go to auction until about April 2022.

    The CFPB’s foreclosure rules state that a borrower needs to be at least 120 days delinquent before the foreclosure process can start. They extended timelines because they are concerned that borrowers in forbearance will exit forbearance and then immediately go into foreclosure.

    Of the roughly 2.5 million borrowers in a forbearance plan, about 2.1 million are on a plan extension, meaning they have been in forbearance for at least three months (timelines depend on loan type and/or servicer). The CFPB’s proposal does not take into consideration that about 41% of forbearance plan exits are current on their payments at the time of exiting. For more forbearance data, check out my AZ Forbearance Update from Wednesday.

    A number of industry leaders are questioning the proposal stating that the CFPB is violating legal contracts and agreements that are currently in place.

    “I was surprised we went all the way to the end game. Candidly, I’m not sure the CFPB has the legal standing to disrupt a contract law across the country, especially as some of these are private loans and there is a contract made between the borrower and lender. This is the first time the CFPB has really tried to interject itself in this dramatic manner. So I do suspect if they come out with this ruling, we might see legal challenges to it by somebody in the industry.”

    -Rick Sharga, RealtyTrac

    The proposal is open for public comments through May 11. To comment, email: 2021-NPRM-COVID-Mortgage-Servicing@cfpb.gov. Include Docket No. CFPB-2021-0006 in the subject line of the message.

    Real Estate News:

    • For 1.5% of the sales price, Offerpad will allow sellers to stay in the property up to 60 days after close of escrow.
    • Announced Monday, Redfin finalized its $608 million acquisition of RentPath, the parent company of ApartmentGuide.com, Rent.com, and Rentals.com. Rental listings will be available on Redfin by 2022.
    • Eight new real estate executives joined the ranks of the roughly 200 real estate executives on this year’s Forbes Billionaire List. Zillow co-founders Rich Barton and Lloyd Frink and eXp founder Glenn Sanford are now among the 2,755 richest people in the world.
    • Last summer New York City reached its highest vacancy rate in 14 years. Sales in Q1 2021 in New York City increased by 58% year over year and reached the highest total first-quarter sales in 14 years.
    • According to a Zillow survey released on Tuesday, 11% of Americans moved during the pandemic accelerating the trend which began in 2018 of people moving to smaller, less expensive cities in the Sun Belt. From January through November 2020 Phoenix, Charlotte, and Austin had the highest inbound moves from expensive, high-tax cities.
    Zillow

    Final Thoughts:

    Residential real estate is indeed heating and cooling at the same time. Homeowners have gained serious equity, savings rates are high, and economists are optimistic. 2020 created more billionaire real estate executives while 9.7 million people remain unemployed.

    Copywrite 2021 Sarah Perkins

  • AZ Forbearance Update 4/7/2021

    In this 15 minute video, Lydia Wietsma and I discuss forbearance, evictions, delinquencies, extensions, and appreciation.

    Forbearance Numbers:

    The number of loans in a forbearance plan dropped for the fifth straight week. This week we decreased to 4.90% from 4.96% of all loans are in forbearance. The number of borrowers remains right around 2.5 million.

    Forbearance by Stage:

    • 13.7% are in the initial stage, down from last week’s 13.8%.
    • 84.1% are on extension, up from last week’s 83.4%. Over 21% of these borrowers have been on a forbearance plan for over 12 months.
    • 2.2% are re-entries, down from last week’s 2.8%.

    Forbearance exits from June 1, 2020 through March 28, 2021:

    • 41.2% of borrowers either continued making their payments throughout their forbearance plan or got caught up upon exit. This is down from last week’s 41.7%.
    • 13.9% of borrowers exited their plan, still behind on their payments and without a loss mitigation plan in place. This is a decrease from last week’s 14.1%.

    Of the total exits in March 2021, 21% received a loan modification due to income declines.

    Logan Mohtashami, the lead housing economist for HousingWire believes that the increased employment numbers may end forbearance sooner than expected.

    Evictions:

    For the third time, the CDC extended its eviction moratorium. This time through June 30th otherwise it would have expired at the end of March.

    Based on US Census surveys (not the big one) renters owe an estimated $60 billion in back rent payments and other housing costs.

    Landlords who either cannot continue with the financial obligations of the investment or who are tired of owning it are starting to list and sell the properties with the non-paying renter included. There are investors who want properties and are willing to take on non-paying renters in order to acquire the property. The amount owed to the current landlord is often made up in the sales price.

    This is a good option for struggling landlords.

    Delinquencies:

    In February delinquencies ticked up slightly from January. Experts believe this is mostly due to the short month. We will know when we see March’s numbers.

    Despite the increase, 30-day lates are 19% below pre-pandemic numbers. There are still 5 times more 90+ day lates before the pandemic. That is about 1.7 million more than there were a year ago. This number includes those in a forbearance plan.

    Foreclosures:

    On Monday, the CFPB proposed furthering the ban on foreclosures through the end of 2021. Under current CFPB foreclosure rules, a borrower must be 120 days delinquent before the foreclosure process can start. I am not sure what the timelines are for those who were in the foreclosure process last year when the moratoriums were put in place. The services want to start where they left off, but will they be able to? It sounds like the CFPB does not agree though. The 120 days is to protect those who exiting their forbearance plan more than 90 days late from immediate foreclosure.

    Servicers:

    Servicers are hiring and preparing for more REOs and foreclosures. They are at the mercy of federal policy but they are preparing nonetheless.

    Appreciation:

    It is very difficult to make predictions in this current environment. Policy is changing regularly. We do know one thing that is helping all homeowners, struggling or not, it is the sky-high appreciation. Nationwide it is nearly 16% and here locally it is 19%. This gives homeowners options, whether or not they are struggling to make payments.

  • This Week in (Greater Phoenix) Real Estate 4/5/21

    In this 10 minute video, Amber Kovarik and I discuss the latest in mortgage rates, unemployment, inflation, and inventory.

    Headline:

    I would like to address a very specific headline I am seeing more and more often. It is the one that says there are 10 million mortgage borrowers behind on their payments. That is NOT the case. According to the US Census, there are about 10 million renters and borrowers behind on their payments. And according to Black Knight, who does the most thorough analysis of delinquencies and forbearances, about 3.4 million borrowers are delinquent on their payments, and that number includes borrowers in forbearance. With that being said, it is safe to assume that there are about 6.6 million renters behind on their payments. The renter data is tough to collect so I am not sure if that is just the count in large apartment complexes or if that includes single-family renters.

    These numbers are important to keep in mind when we look at the future health of the housing market.

    Policy:

    Today the CFPB proposed furthering the ban on foreclosures through the end of 2021. Under current CFPB foreclosure rules, a borrower must be 120 days delinquent before the foreclosure process can start. I am not sure what the timelines are for those who were in the foreclosure process last year when the moratoriums were put in place. The services want to start where they left off, but will they be able to? It sounds like the CFPB does not agree though. The 120 days is to protect those who exiting their forbearance plan more than 90 days late from immediate foreclosure.

    Last week the CDC extended the eviction moratorium for the third time, this time through 6/30/21.

    Market Shift:

    There is a lot of talk about the market shifting. It is and this is a good thing. Don’t be nervous when you hear other agents are talking about fewer showings and fewer offers. Going from 30 offers to 5 offers is still great for the seller. Demand is dropping faster than supply. Supply has leveled over the past few weeks, it is still 78% below normal while demand is 11% above normal. As long as demand is higher than supply, prices will go up. The 19-20% appreciation rate we are seeing is not healthy and as people are priced out of the market due to sky-high appreciation, demand will continue to slow. Prices will still go up, just at a slower rate.

    Our local median sales price reached nearly $360,000 and the national median sales price reached an all-time high of $370,000. That is even higher than the housing bubble highs.

    Interest Rates:

    The stock markets have hit all-time record highs this morning after being closed all day Friday. The Friday new jobs report, which showed 916,000 new jobs created in March, the best monthly report in 7 months, and today’s better-than-expected ISM index report on the growth of the services sector of the U.S. economy, are the two top drivers of the markets this morning.

    In regards to interest rates, there are two independent forces in play that could push up interest rates on 30-year fixed-rate mortgages. The first is a general force that will push up all interest rates, due to a rebounding economy which increases the demand for borrowing and drives inflation rates higher. As the U.S. economy continues to recover, this traditional force of supply-and-demand will naturally push up the rates on 30-year fixed-rate mortgages.

    The second important force, which specifically applies to mortgage rates, is the Fed’s monthly mortgage-backed security purchases which are artificially holding mortgage rates 1/2 – 1%  below where they would be in a normal market price. The Fed cannot continue these monthly purchases indefinitely and at some point, they will need to reduce and then stop these completely. The Fed will stop when unemployment clearly reaches 4.00-4.50% and inflation consistently exceeds 2.00%.

    Second Home Loans:

    The MBA and many lenders and mortgage companies have stated opposition to the recent Fannie Mae and Freddie Mac rule only allowing 7% of their portfolios for second home loans. Currently, most lenders are selling closer to 14% of their second home loan portfolio to the GSEs. What many lenders are doing is increasing the interest rates on those loans. Guild has increased refinances by about 1% hoping that satisfies the requirement and allows them to sell those loans to other investors. As more info comes out about these changes, we will be sure to share the news.

  • Greater Phoenix Real Estate Update 4/2/2021

    The human condition versus efficiency.

    Real estate disruption is all about creating efficiency. As we lead busier and busier lives, fast and efficient is appealing, right? In theory, buying and selling a property with Amazon-like ease sounds great. In reality, our human condition drives us to desire human input, not just in reading interesting articles but in being able to talk to someone about specifics.

    For example, in a recent HousingWire article about where Realtors fit into Zillow’s plans, Matthew Blake writes, “Zillow wants to do it all in real estate. And the role of agents in this isn’t nothing. But agents’ role seems more like one worker on an assembly line, instead of a hand-holder amid the dynamic, stressful and inefficient process that is the home sale.” Does an assembly line strategy best serve the consumer? Unlikely. Yes, the industry definitely has inefficiencies to improve but in order to create greater efficiency do we also have to give up individual guidance for the consumers who want it? I don’t think so.

    On Tuesday, Brad Inman wrote, “In this fast-changing world, the digital face off will become more pronounced for the consumer. Advertising dollars are flowing into the digital alternatives, giving the customer more choices with a mix of competing benefits. Efficiency versus human touch; higher versus lower fees; and the old way versus something new and often untested.”

    IPOs, SPACs, and Unicorns:

    • Knock hired Goldman Sachs to take them public either via IPO or SPAC with a goal of a $2 billion valuation.
    • Compass successfully completed its IPO and went public yesterday giving it an $8 billion valuation and about $450 million in capital (roughly half of the goal outlined in the initial S-1 filing). Investors and real estate professionals alike are closely watching Wall Street’s reaction to the IPO. Compass has positioned itself as a tech company like Redfin or Zillow with valuations of $28.7 billion and $32 billion, respectively. But many in the industry consider it a traditional brokerage more like Realogy with a valuation of $1.78 billion or RE/MAX with a valuation of $1.19 billion. (despite the huge variation in valuations Realogy and RE/MAX are profitable while the others aren’t) While it is not unusual for valuations to fluctuate, we will soon know how Wall Street defines Compass.
    • WeWork, a co-working company, announced it is going public via SPAC in Q3 2021 with an expected valuation of $9 billion. In 2019 WeWork attempted and failed to go public via IPO and its valuation dropped from $47 billion to $3 billion.
    • To be considered a “unicorn” a company must reach a $1 billion valuation (there are about 600 on the planet) and the frequency of real estate tech companies reaching unicorn status is increasing, here are three examples:
      • Side a back office brokerage and technology platform that keeps teams and agents front-facing.
      • Pacaso creates co-owner opportunities for second homes.
      • Divvy Homes offers rent to own solutions and down payment options.

    National Real Estate:

    • Pending home sales declined by 10.6% from January to February; mostly due to low inventory.

    “The demand for a home purchase is widespread, multiple offers are prevalent, and days-on-market are swift but contracts are not clicking due to record-low inventory. Only the upper-end market is experiencing more activity because of reasonable supply. Demand, interestingly, does not yet appear to be impacted by recent modest rises in mortgage rates.”

    -Dr. Lawrence Yun, NAR’s chief economist
    • Demand increased in March as people rushed to lock in their rates as they rose. It is too early to see the true impact the rising interest rates will have on buyer demand.
    • After two weeks of staying relatively flat, this week’s active single family listings nationwide decreased by about 3,000 listings to 312,872.
    • According to Realtor.com, nationwide, the median sales price in March reached $370,000; up 15.6% year over year. The highest median sales price ever, even above the highs of the 2005 bubble.
    • Asking prices for new listings has just started to level off after the giant run-up. Leveling off at the end of March/early April is normal seasonal behavior. We will likely see it start to fall towards the end of April, which is also part of the normal seasonal real estate cycle.
    • Price reductions increased slightly to 16.3% from last week’s all-time low of 16.1%. The number of price reductions is a great way to gauge buyer demand, which based on these numbers remains extremely high.

    “Only higher rates will result in more days on the market and thus larger inventory. We need these two things in order for buyers to have more choices and more reasonable price growth. Again, the question remains if rates will get high enough to have this effect on the market before more price damage is done. Right now home prices aren’t high enough to impact demand in a major way.”

    -Logan Mohtashami, HousingWire’s lead analyst
    • As sales prices climb, homeowner equity rises too. According to this chart homeowners in CA and VT have the most equity. It also shows that 32.5% of Arizona’s homeowners have at least 50% equity.

    The AZ Market:

    Cromford Market Index (CMI): Is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 502.7. On 3/20/2020, it reached the pre-COVID peak of 241 and on 5/15/2020 it bottomed out at 145.2 and started increasing continuously until 3/14/2021 when it reached 514.9. It was then that demand continued decreasing while inventory finally stopped dropping, albeit at 78% below normal. As of yesterday demand is 11% above normal.

    The supply versus demand imbalance has pushed the median sales price up to $358,250 giving us a 19% year over year appreciation.

    The Milken Institute recently published a report ranking top US cities. The ranking is based on jobs, wages, tech growth, housing affordability, and broadband access. Phoenix ranked #7 and is the largest population. Phoenix isn’t just for cowboys, retirees, and spring break. We have a growing high-tech economy with a highly educated workforce.

    Elliott D. Pollack & Company

    Lending:

    • For more on forbearance, foreclosures, and inflation check out my update from Wednesday, here.
    • Purchase mortgage applications declined last week by 1% week over week, mostly due to low inventory. They are 39% higher, year over year. Throughout April, year over year numbers will be will not be a good market indicator since last April we were on lock down and had a curfew.
    • Freddie Mac announced yesterday that despite the low interest rates, buyer demand has started to pullback. At the beginning of 2021 demand was 25% above pre-pandemic levels and now demand is at 8% above pre-pandemic levels.

    “We even see that purchase demand is diminished today as compared to late May and early June of 2020, when mortgage rates were the same level. This is confirmation that while purchase demand remains strong, the marginal buyer is feeling the affordability squeeze resulting from the increases in mortgage rates and home prices we’ve experienced in recent months.”

    -Sam Khater, Freddie Mac’s chief economist

    Federal Policy:

    Real estate groups are praising President Biden’s proposed $2 trillion infrastructure plan because it of its focus on housing. The plan calls for funding for repairs and upgrades to buildings, roads, bridges, the electrical grid, water systems, and more including:

    • $213 billion for affordable housing.
    • $40 billion to improve public housing.
    • $20 billion in tax credits for affordable housing.
    • $10 billion to modernize federal buildings.
    • Create grant programs for cities and towns that remove barriers for building affordable housing (like exclusionary zoning laws).

    Real Estate News:

    Final Thoughts:

    The real estate market will not stay like this forever. Today the story of a $275,000 fixer in suburban DC that received 88 offers, 76 of which were cash, and 15 sight unseen and sold for $460,000 is surprising. Six months ago it would have been shocking. A year ago, no one would have believed it.

    Inventory will increase, appreciation will slow, buyers will once again have options, and sellers will list their houses without the fear of having nowhere to go.

    As Ella, my family’s nanny, reminds us regularly, this too shall pass. Strike while the iron is hot, save for tomorrow, and hope for the best.

    Copywrite Sarah Perkins 2021

  • AZ Forbearance Update 3/31/2021

    In this 11 minute video, Lydia Wietsma and I discuss the latest in forbearance, inflation, and foreclosures.

    Predictions & Inflation:

    There is a lot of talk about what will happen next. While we do not have a crystal ball and the real estate market is unpredictable, there are a few assumptions we can make based on the numbers. There are tons of headlines and YouTube videos all about how the market will crash in 2021. The problem with many of these predictions is that they exclude very important data. Today I saw a YouTube video with many thousands of views and used lots of numbers to illustrate his point. Throughout the entire video, he never made mention of buyer demand or homeowner equity. Remember, the foundation for all economics is the relationship between supply AND demand.

    While, yes the supply could and will likely rise as the foreclosure moratorium is lifted. But these will be for properties with equity and the homeowners can do a normal sale and walk away with money in their pocket. 40% of residential housing is owned free and clear and And nearly 57% of mortgaged homes have at least 50% equity. In 2020 alone, homeowners gained $1.5 trillion in equity.

    With all the of stimulus being pumped into the market, concerns over inflation are rising. The feared inflation is already here but rather than oil companies or grocery stores increasing their prices, it is homeowners increasing sale prices of their property.

    Logan Mohtashami of HousingWire described inflation as, “As a general economic rule, widespread inflation is caused by a shortage in goods and services – or in common vernacular, too many dollars chasing too few goods.” This is what we are going through in housing; a severe supply and demand imbalance. Consumers call it appreciation and economists call it inflation.

    Forbearance Numbers:

    Now, let’s talk about the forbearance numbers. We saw improvement again last week and dropped down to a new low in a year. We decreased from 5.05% of mortgages in a forbearance plan to 4.96% or about 2.5 million borrowers.

    Forbearance by Stage:

    • 13.8% are in the initial stage, down from 13.9% last week and reached their lowest level in a year.
    • 83.4% are on extension, down from 83.5% last week. About 17% of borrowers in this category have passed the 12 month mark in a forbearance plan.
    • 2.8% are re-entries, up from last week’s 2.6%.

    Forbearance exits from June 1, 2020, through March 21, 2021:

    • 41.7% of borrowers either continued making their payments throughout their forbearance plan or got caught up upon exit.
    • 14.1% of borrowers exited their plan, still behind on their payments and without a loss mitigation plan in place. This is the group that needs the most attention. They need to know they have options.

    CFPB website with solutions for struggling renters and owners: https://www.consumerfinance.gov/coronavirus/mortgage-and-housing-assistance/

    Foreclosures:

    There were 250,000 foreclosures in process before the pandemic. They will likely be restarted at the same stage where they were in foreclosure before. Based on those numbers and the potential borrowers who may be still struggling after their forbearance plan, we might see around 500,000-750,000 foreclosures in 2021. After the market crashed in 2008 there were nearly 10 million foreclosures.  

  • Greater Phoenix Real Estate Update 3/26/2021

    “There are decades when nothing happens, and then there are years when decades happen,” Notarize CEO Pat Kinsel said after raising $130 million in funding.

    National Real Estate:

    Inventory remained flat again this week, now two weeks in a row. We have 316,073 active single-family listings nationwide. This is a good thing for buyers and means that our market is moving towards a more balanced environment. It is less good for sellers; especially those expecting to sell for $50,000 or more over asking. It is normal for inventory to stay low through March, it usually starts climbing by late March, or at least by April 1. Last year our inventory peaked on April 3 at about 750,000 active single family listings. After that inventory started plummeting for 50 weeks straight.

    The percent of homes with price reductions is currently at record lows at 16.1%. Enough contracts are coming in over-asking which means very few sellers are reducing their asking price. For Realtors working with sellers and potential sellers, the next 3-4 weeks is likely going to be the absolute peak. The rest of the year will continue to have strong buyer demand and increasing prices, but the absolute peak of the demand frenzy is likely happening right now. So now is the time for sellers to get the biggest premium.

    According to Freddie Mac, rates reached 3.17% yesterday, the highest they have been since June.  A year ago they were 3.5%. As interest rates increase, home buyers are spending less on discretionary items, like certain upgrades in new homes or waiving inspections or appraisals in resale homes.

    About 50% of mortgage borrowers in the US have interest rates at or below 4%. Ivy Zelman is concerned that if rates go too far above 4% that it will lock a lot of homeowners in their current properties, unwilling to take a higher rate which would further reduce inventory.

    About 40% of the 138 million residential properties nationwide are owned free and clear. And nearly 57% have at least 50% equity. (KCM)

    Market Headlines:

    Existing home sales declined 6.6% from January to February. No need to panic though, sales were up 9.1% year over year and the market was strong during February 2020. The decline is due to the low inventory combined with the 15.8% year over year appreciation.

    New home sales dropped 18.2% from January to February but are still up 8.2% year over year. New home sales are usually impacted more by interest rates than are existing home sales. Builders are impacted by rising costs too, due to labor shortages, supply chain issues, and lumber costs. A new home now costs $24,000 more, on average, a cost that is pushed to the buyer.

    “Despite the drop in home sales for February — which I would attribute to historically-low inventory — the market is still outperforming pre-pandemic levels,” 

    Dr. Lawrence Yun, NAR’s chief economist

    Many economists and housing experts are talking about the inflation impacting our market, not inflation of goods and services but inflation in housing. Anyone wondering when we will be impacted by inflation doesn’t need a crystal ball. It is here and happening now. Every single home buyer looking in this market will agree.

    The AZ Market:

    • At 2.1% of all home sales, Phoenix had the largest number of iBuyer sales in Q4 2020.
    • New home permits in Greater Phoenix increased by 24% year over year in February, while nationwide permits decreased by over 10% year over year. (Elliott Pollack)
    • Locally, inventory has stopped dropping also. Here is some perspective; in January 2019 we had over 18,000 active listings and in January 2021 we had just over 6,000.
    • As long as there are more pending listings than active listings, we will be in a market frenzy, the extent of that frenzy is based on how wide the gap is.

    Forbearance:

    For info on forbearance, buyer confidence, and a surprising move by some landlords, click here for my update from Wednesday.

    Another Commission Lawsuit:

    NAR, a few CA MLS associations, and several large national brokerages were named in the 5th class action lawsuit going after commissions that was filed last week. The plaintiffs in all five lawsuits want to have homebuyers pay their agent directly rather than having the listing agent share their commission.

    NAR/DOJ Settlement:

    In November the DOJ filed a lawsuit and settlement against NAR requiring 5 changes for NAR to implement by the end of Q1 2021. The most notable change is that the commission offered to the buyer’s agent is to be made public. RE/MAX, Redfin, and a few MLS’s have started making the info available. On Tuesday a spokesperson from NAR said these changes may take months to process. There is no ETA for the actual implementation of these changes and from the sounds of things, they are still working on the details of those changes.

    GSE Second Home Policy:

    On Tuesday, the Mortgage Bankers Association sent a letter to Treasury Secretary and the FHFA director expressing concern over recent amendments including the 7% limit on the GSE’s portfolio for second home loans, a rate well below the current percentage. The MBA asked for a meeting to discuss the potential “unnecessary disruptions in the housing finance system.” For more information on the portfolio limits, check out my video and post from Monday, here.

    Demand for investment properties and vacation homes has risen 84% year over year – more than double the demand for a primary home.

    Real Estate Disruption:

    Zillow had 9.6 billion visits to its website in 2020, by far the most of any real estate company or portal. This is why real estate was the top performing sector in the entire economy.

    Is Zillow becoming a verb? According to a Google Trends report, more people in 2020 searched “Zillow” than “real estate.”

    Real estate tech strategist and iBuyer guru Mike DelPrete said, “The point is not that these business are unprofitable and therefore must be bad. Spending (and losing) money to gain market share is a well-worn path. The point is that these companies are actively doing it, and if you’re in the real estate industry, concerning yourself with disruptors willing to lose billions is a good use of time.”

    Pete Flint co-founder of Trulia said, “I often say that if something can be commoditized, it will be commoditized, and I look at the financing, title and escrow and all these components of the real estate industry that will get digitized, and will get somewhat commoditized. But if you’re providing value as an agent, which cannot be commoditized, then I think you’re going to be fine.”

    Real Estate News:

    • Offerpad announced it is going public through a SPAC created by former Zillow CEO and co-founder, Spencer Rascoff. Ironically, after Rascoff’s departure, Rich Barton, the current Zillow CEO and co-founder, began heavily investing in Zillow’s iBuyer. After going public, Offerpad expects a $3 billion valuation and will receive up to $650 million in cash. They will use the funds to expand to new markets and increase advertising spends in existing markets.
    • Homie is hiring 1,000 new buyer (employee) agents nationwide.
    • The CFPB reversed policies from January 2020 which limited its power. The CFPB plans on exercising greater enforcement “consistent with the full scope of its statutory authority under the Dodd-Frank Act.”
    • According to CoreLogic, American homeowners gained about $1.5 trillion in equity in 2020.
    • Target plans on spending about $4 billion a year expanding and improving its real estate portfolio. After sales in 2020 grew by more than $15 BILLION, more than the previous 11 years combined.

    Final Thoughts:

    For anyone, buyer or seller, on the fence about what to do next; the answer is clear. Buy now, rates and home prices are going up. Sellers sell now, increased inventory is coming and that will create more competition and, likely, more time spent on the market.

    Copywrite Sarah Perkins 2021

  • AZ Forbearance Update 3/24/2021

    In this 10 minute video, Lydia Wietsma and I discuss the latest in forbearance, declining sales, inventory levels, buyer confidence, and a surprising move for landlords.

    Forbearance Update:

    This week’s forbearance numbers are good, we dropped from 5.14% to 5.05% of loans are in forbearance which drops the total number of loans in forbearance by 100,000 to about 2.5 million, which is the lowest number since last March. However, more than 11% of those still in forbearance have exceeded the 12-month mark, and Mike Fratantoni, MBA’s chief economist, says many of those could opt for the recent extensions, allowing up to 18 months in forbearance for government-backed loans. Remember the specific timelines are based on the servicer and loan type.

    Forbearance by Stage:

    • 13.9% are in the initial stage, down from last week’s 14.1%.
    • 83.5% are on extension, up from last week’s 83.3%
    • 2.6% are re-entries, which is the same for the past two weeks.

    Forbearance exits from June 1, 2020, through March 14, 2021:

    • 42% continued making their payments or got caught up upon plan exit. This is down from last week’s 42.3%.
    • 14.2% of borrowers exited their plan while still behind on their payments and without a loss mitigation plan in place. This is down from last week’s 14.1%.

    Buyer Confidence:

    A recent study from Freddie Mac showed that borrowers are more confident in their ability to pay their mortgage. Confidence in the housing market has bottomed in April at 48%, peaked in October at 69%, and averaged 60% in 2020. In February 2021, confidence reached 66%!

    Source: Freddie Mac

    Sales & Inventory:

    NAR’s existing-home sales report just came out and due to low inventory, there was a sales decline of 6.6% in February. The significance of the low inventory is why we are seeing a 20% appreciation, which is very unhealthy.

    To illustrate the point on January 1, 2019 we had 18,000 active listings. On January 1, 2021 we had 6,000 active listings and today we have about 4,000.

    Landlords:

    A surprising number of landlords are declining funds from the latest stimulus package’s $50 billion in emergency rental assistance. The landlords are concerned about the additional restrictions – like not being able to get rid of difficult tenants, paperwork, documentation required.

  • This Week in (Greater Phoenix) Real Estate 3/22/21

    In this 12 minute video, Amber Kovarik and I discuss the latest in housing, lending, and proposed policy.

    Affordability:

    Affordability is and will remain the biggest issue in real estate this year. Not only are prices increasing quickly, but builders are also struggling with the supply chain, labor shortages, and lumber increasing by 200%. The average additional cost to builders is $24,000 per home and that is being pushed to the buyers.

    The increased cost, increased interest rates, and cold winter are all reasons why builders slowed their production in February.

    Offerpad:

    Offerpad is going public with former Zillow CEO, Spencer Rascoff’s SPAC. Since Rascoff left Zillow, Rich Barton has poured tons of money and resources into building up Zillow Homes, Zillow’s iBuyer. This will give Offerpad an equity position of $3 billion and up to $650 million in cash.

    PRO Act:

    The PRO Act is currently moving through Congress and President Biden said he would sign it. As it stands now it impacts independent contractor status and would make it so that anyone who is not incorporated will be considered an employee. Most Realtors create an LLC or PLLC and are employees of their entity. This impacts the 27 right-to-work states including Arizona. I have read arguments on both sides and I have no idea if it will pass or not but if it does, there could have an immediate impact on real estate.

    The timing is interesting as we see many companies following Redfin’s path of employee agents. Zillow, Opendoor, and Homie all have agent employees. Last week Homie announced that they are hiring 1000 buyer agents nationwide.

    The AZ Market:

    Locally, active listings have, finally, stopped dropping. This could be for several reasons. The best one is that maybe we are going back to some element of seasonality and March is the time of year when we have the most inventory growth. Now the numbers are not going up, but they are not dropping. We have like 10 more listings than we had a month ago. Demand is dropping though, faster than supply. It remains nearly 14% above normal while supply is nearly 78% below normal. This means that sellers are getting 10 offers instead of 50 and that appreciate rates will slow. We do not need 20% appreciation rates so this is good for the market. We are currently unsustainable. The market needs some stability and allowing inventory to rise and demand to fall will get us there. And as long as demand remains above supply, prices will continue to go up. No one is expecting a crash or for values to go down.

    The demand dropping is primarily due to buyer exhaustion, affordability challenges from quickly appreciating prices, and interest rates going up, but not as much as one would think.

    Lending:

    Interest Rates:

    Interest rates have been on quite the tear lately. The market headline is that interest rates hit 14-month highs due to market expectations of a recovering economy and increasing inflation.

    Today there is a small glimmer of hope for interest rates as the 10-year Treasury bond yield, which hit a high of 1.754% on Friday did not keep going higher so far today. 

    The pause in the continuous rise of the Treasury bond yields over the past six weeks, is giving hope that interest rates might stabilize for a while. 

    Amber also discussed the importance of talking with all pre-approved buyers, rates are 3.5% now. If a buyer wins an offer in this competitive market it is important that they still qualify for the loan and make the monthly payments.

    Fannie Mae & Freddie Mac Restrictions:

    She also explains what the new Fannie and Freddie regulations mean for second home and investor purchases. Just because the GSEs loan portfolio is now limited to 7% for second home loans; that doesn’t mean those are the only options. There are other options for second home borrowers but they will come at higher interest rates which could further slow demand. As the changes are implemented, we will continue to share the implications and options for these buyers.

    This chart is a recent MBA chart of the week and it shows the growth in second home mortgage applications, either for purchase or refi. The MBA provides this commentary, “In February 2021, 10.1 percent of all applications in the retail and consumer direct channels were for a non-primary residence. This was an increase from 9.5 percent the previous month. 2019 and 2020 saw annual averages of approximately 8 percent. Breaking down the categories, second-home transactions accounted for 3.6 percent of all applications and investment properties were 6.5 percent, totaling 10.1 percent. Average loan sizes as of February 2021 were $430,000 for second homes and $263,000 for investment properties.”

    Mortgage Banker’s Association 3/12/21 Chart of the Week
  • Greater Phoenix Real Estate Update 3/19/2021

    Once again, today is all about the AZ market. Recently, Lawyers Title hosted a presentation with Tina Tamboer with the Cromford Report. She always shares pertinent and timely information. Below I have combined a lot of her information from her presentation, along with additional information from my research.

    What affects supply?

    • New Homes
    • FSBOs
    • Appreciation/Depreciation (equity)
    • Foreclosures/Household Formation (shrinking)
    • Relocation (Outbound)
    • Divorce/Illness/Death/Job Losses/Tragedy
    • Consumer Sentiment

    What affects demand?

    • Interest Rates
    • Appreciation/Depreciation (affordability)
    • Relocation (inbound)
    • Employment/Income
    • Loose/Tight Lending Practices
    • Population Growth
    • Household Formation (growing)
    • Consumer Sentiment – this could be the most important of them all.

    The recent announcement that Fannie Mae and Freddie Mac must restrict second home and investment property loans to only 7% of their total portfolio (far less than it is currently) may negatively impact demand. This move could force second home buyers to pay higher interest rates on their loans.

    Employment:

    • AZ is on track to see 11% job growth over the next 2 years.
    • 519 new companies came to AZ in the past 5 years.
    • The AZ job market has diversified a lot in the past 12 years. We have gone from the majority of our population working in hospitality and housing to also have an emphasis on tech, biotech, manufacturing, health care, etc. 
    • Arizona’s unemployment rate is 6.3% and the national rate is 6.7%. 5% is considered full employment.
    • Initial claims were at 4,108 the first week of March, normal is 3,807.
    • Continuing claims remain significantly heightened. We are running 65,000 continuing claims a week and normal is about 19,000.
    • People will less education have been more negatively impacted than have those with a college degree or higher.

    Renters:

    Due to the high unemployment rates for younger workers and less-educated workers; renters are struggling more than homeowners. In addition to the additional renter’s assistance in the latest stimulus plan, Arizona has quite a few options for rental assistance. Landlords are able to register on behalf of their tenants. For more information visit: https://des.az.gov/ERAP

    Forbearance:

    There are people who think it will be raining homes when the forbearance period ends. This is not going to happen.

    Every 3 months we see an improvement, as more borrowers exit their forbearance plans. But the past few months have been flat. Hovering around 2.6 million borrowers in a plan. The recovery continues making slow progress. At the end of March, we will likely see a lot of forbearance plan exits. There have been additional filing extensions. For more information on forbearance, delinquencies, and demand please see my forbearance update from Wednesday, here.

    Foreclosures:

    What happens with the moratoriums are lifted? We will see a wave of foreclosure filings but not of short sales. After 18 months of no foreclosures, there will be a backlog. But they will mostly be sold normally as owners have more equity today. According to KCM, on average nationwide there are about 69,000 foreclosure a month, during normal times.

    Population:

    • Population growth is creating demand.
    • When you lose population, you have extra homes, when you gain it, you have insufficient supply.
    • AZ is #2 for incoming migration behind Idaho.
    • All of the moving companies agree, people are leaving CA, NY, IL, WV and are moving out to AZ, ID, and TX.

    The majority of AZ’s population growth is from people moving here domestically. It is not from lots of babies or international migration. 

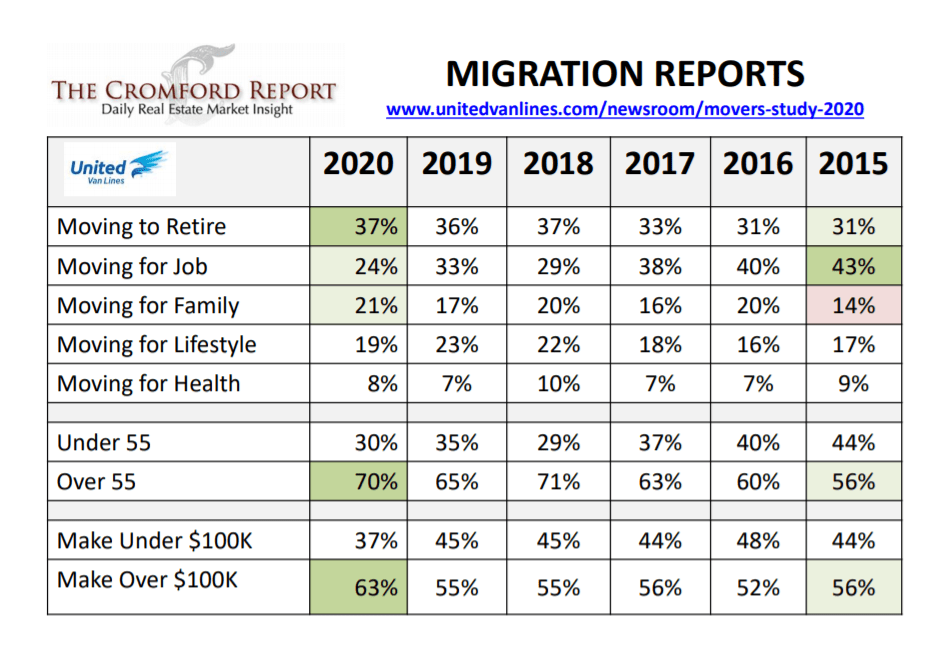
    Most people started moving here to retire versus people moving here for a job in 2018. Look at the ages of the people moving here, their income, and retirement. Our domestic migration is older, wealthier, highly trained, more experienced population and finishing up their career and then retiring.

    Affordability:

    The ideal range for housing affordability is 60-75. Through Q4 2020 in Phoenix someone earning the median income, they can afford 60.6% of what is for sale. In LA it is 9.1% and San Francisco it is 11%.

    Household Income:

    Maricopa county association of governments, shows demographics, click here for the demographics map. Density is increasing in new luxury areas. South Chandler, a lot of Gilbert, east Mesa, and South Mountain is getting bluer. Showing new emerging luxury markets.

    Job Centers:

    Jobs are created by freeways. The heavier the employment area the bluer. A lot of job growth, biomedical, and tech, fueling demand, bringing in people who make a lot of money. Click here for the interactive map.

    The Cromford Market Index:

    Available on the main page of the Cromford Report: http://cromfordreport.com/ (without a subscription)

    • 100 is balanced and prices rise at the rate of inflation, below 100 is a buyer’s market, above 100 is a seller’s market, prices drop below 90, prices rise at 110.
    • On 2/5/2020 we were at 215.1
    • On 3/20/2020 we were at 241
    • On 5/15/2020 we were at 145.2
    • Yesterday we were at 512.6.
    • We peaked on 3/11/2021 at 514.9
    • Prior to this run, the previous peak was 312.9 in the spring of 2005.
    • CMI is the predictor, it moves first and then appreciation follows. Cannot predict the CMI.

    Demand is 14.5% above normal and supply is 77.7% below normal. Despite demand dropping by one percentage point a week and faster than supply is dropping, the market is still in a frenzy. As inventory stabilizes, which it will, this market is unsustainable, things will calm down. Buyers will once again be able to get a house without having to write 10+ offers before one is accepted.

    With the CMI dropping, prices will not go down, they will increase more slowly, which is what we want. This appreciation rate is not sustainable. This doesn’t mean that we will crash. Indicators wants to be together. Markets want to be balanced. Buyer’s markets do not happen because it is time. There are reasons for buyer’s markets, there has to be a cause. Demand needs to be lower than supply in order for prices to drop.

    Is it a good time to buy? Yes! It is best to buy and sell in a seller’s market. Sellers make money and buyers see appreciation right away.   

    What will slow it down? Affordability.

    Affordability in Q1 2021 will likely drop below 60 which puts pressure on prices. the level of demand doesn’t start dropping until we are below 60. How long will it take to get to lower demand? It could take months, who knows. Demand, once it goes to the low side of normal and then we will see supply go up.

    Number of Sales:

    ADRE is adding 500 new licensees a month, not all in residential but it is increasing the amount of competition as more people will be fighting for a certain number of monthly sales.

    Supply will come up when demand goes below normal, prices will continue to go up until demand is lower than supply.

    As transaction counts decrease, it will impact all of our jobs. We need to position ourselves for the 2nd half of the year. Focus all efforts on listings. We have the demand but the competition will be increasing significantly in the 2nd half of the year.

    Interest rates:

    The recent big hike could be a reason for the drop-off in demand. Even though 3% is great, people get scared when it increases. It does limit options for some buyers.

    Those who waited for prices to go down are now paying $20,000 more for the median sales priced home just since December due to rate increases. Since 2018 the median sales price has increased by $80,000 but monthly payments have only gone up by $133.

    Rents:

    Rents are more expensive than mortgages. Rents are rising quickly. The median house rents for $250 more a month than the going rate for a mortgage for the same house.

    Rents are rising = not a bubble, rents decline due to false demand. Rents are declining in San Francisco while houses are still rising, equating to false demand. San Francisco could be considered over-valued. Prices only drop due to vacancies. The number one risk in housing is vacant houses.

    Vacant Homes:

    • 77% of sales in Q4 2020 were owner occupied purchases.
    • The remaining 23% were iBuyer, investor buy & hold or flip, vacation rental, 2nd home properties.
    • Second homes are always counted as vacant. The new Fannie and Freddie rules may impact this market.
    • The new lending guidelines will not impact international buyers.

    Supply: 

    • Supply stopped dropping for the first time in a year.
    • It actually increased by 100 listings in one week.
    • This is the worst year in the past 20 years for new supply, even with the slight increase and despite being the best quarter ever for sales.

    Sales:

    • Selling 2500 houses a week, listing 2000 a week.
    • Pendings have been flat for 1.5 months, we can’t increase properties under contract when there isn’t enough supply.
    • And still are having the best quarter ever.
    • Appreciation is pushing 24% year over year, but most price ranges it is about 10%-15%.

    These markets do not stay like this forever. We will not see then impact of the pullbacks for about a month. Then we may see a slow down in sales. Need more inventory under $500,000.

    Sales Over Asking:

    • 49% of sales closed over asking the first week of March.
    • 40% of sales closed over asking in February.
    • The median amount over asking is $10,000.
    • 50% of all accepted contracts were on the market for only 6 days.

    Population Growth and New Builds:

    We overbuilt for 10 years before we started underbuilding for another 10 years and population growth outpaced building. In 2019 we ate up the last of the glut of housing.

    Developments:

    Without new listings we have to look at new construction which is a challenge due to labor shortages and lumber prices are up 200%, adding, on average an additional $24,000 in cost to the average new build.

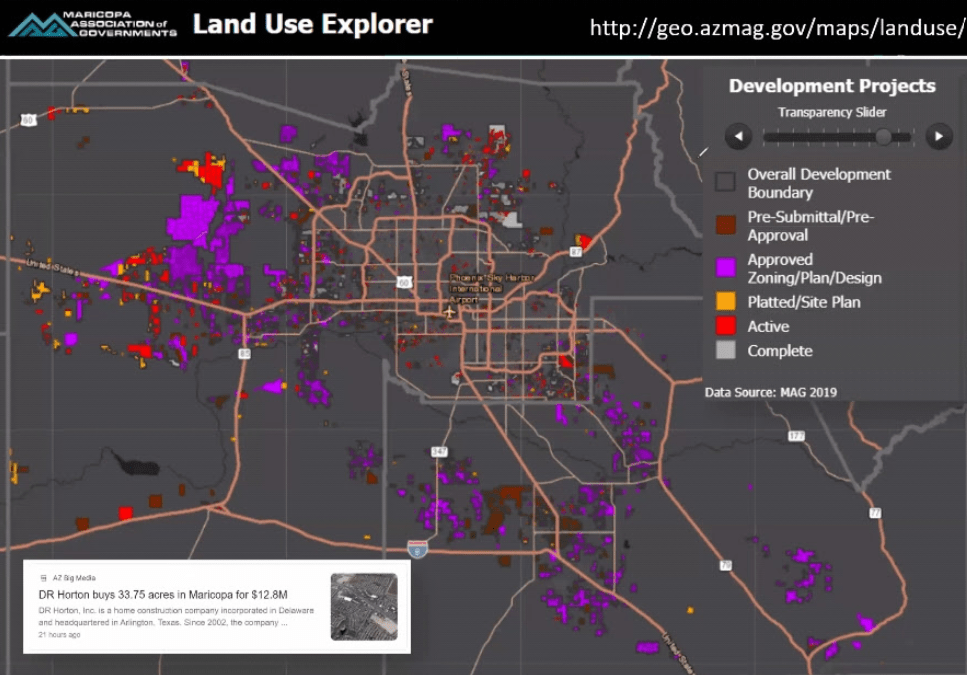
    Most developments are going into the south and west, due to cheaper available land. Very little in the north. Values are increasing the most in the north. Click here for the interactive map.

    Contract Ratio:

    On March 1 the contract ratio was 300. That means for every 100 active listings there are 300 pending listings.

    Final Thoughts:

    • Supply is down 77.7% below normal.
    • Demand is 14.5% above normal.
    • Year over year appreciation is pushing 24%.
    • Sales prices are not going to decline this year.
    • There will likely be fewer sales in 2021 than in 2020 due to the low inventory levels.