Category: AZ Real Estate

  • Phoenix Area Real Estate Update 8/7/2020

    Disneyland announced its closure due to COVID-19 on March 12. Despite being the usual 31 days, March lasted longer than any other month in history. People all over the world were glued to the news; trying to make sense of what was happening. April 19 was the turning point for Arizona real estate. In May the end was in sight. And then it wasn’t. Now it is August, a time when we used to buy school supplies and take the first day of school photos we are, instead, buying laptops for Kindergarteners begging them to hold still for one more minute.

    The intense political climate has brought more confusion than answers. Today it was announced that 50% of Americans do not trust the media. I was surprised that the number was not higher. We know a lot more now than we did five months ago but a great deal remains to be seen.

    Let’s start with what we do know. Real estate is saving our economy.

    What we know:

    Demand for real estate is intense all over the country and it is reflected in the 11% year over year sales price increase for the last week of July. The national median sales price is up to $315,000. (Redfin)

    TheAZMarket:

    Cromford Market Index (CMI): Is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 324, the pre-COVID peak was 241 and bottomed out on May 15 at 145.2. This week we blew past the previous record set in 2005 at 312.9.

    Supply: The available inventory continues to stabilize; it just happens to be at an extremely low level. As of yesterday, our inventory is 63.3% below normal. Active listings excluding under contract accepting backups (UCB) are down over 42% year over year and nearly 11% month over month.

    Demand: Pending sales are down 2.5% since last month but up 16% year over year, which is significant given how much lower our inventory is today. Our demand is nearly 19% above normal and increased by 2.6% in the past seven days.

    Sales & Prices: Phoenix metro area closed sales are up nearly 15% month over month and up 16% year over year. The median sales price is $315,000, up 2.5% month over month and nearly 11% year over year. Healthy appreciation is 3% annually.

    Southeast Valley New Listings, Pendings, and Closings:  This week over week comparison for Tempe, Mesa, Chandler, Gilbert, Apache Junction, and Queen Creek since March 15 shows the recent supply stabilization, demand continues to outpace supply, and sales are increasing. Closings always spike at the end of the month.

    What else do we know?

    • Today’s fast-paced, ultra-competitive real estate market is not only due to pent up demand, the historic low-interest rates and dropping inventory are fueling the fire. Realogy CEO Ryan Schneider said, “Today we are seeing inventory down 15 percent or more in every price band compared to a year ago when inventory was already at historic lows.” (Realogy earnings call)
    • NAR has added a new partnership to the Realtor Benefits Program, ReferralExchange, a concierge, lead vetting company. (NAR)
    • Nationally, new unemployment claims last week was 1.2M. 250,000 fewer than the week prior. We are now at 11% unemployment, down from 11.6% the previous week. (US Department of Labor)
    • New Arizona unemployment claims last week declined by 14% from the previous week. (US Department of Labor)
    • Mortgages in forbearance declined for the seventh week in a row, down to 7.67% of all mortgages or roughly 3.8 million loans. (MBA)
    • Delinquencies for commercial mortgage-backed securities hit 9.6% in July, up from 2.62% last year. (Bisnow)
    • Since the beginning of March 72,842 businesses on Yelp permanently closed. (Elliott Pollack)
    • Judge overturns Governor Ducey’s gym closure, stating they must be allowed to prove they can safely operate during the pandemic. (Phoenix New Times)
    • COVID changed homebuyers timelines, and not in the way expected. More are moving up their purchase timelines. (Redfin)

    “Somewhat counterintuitively, the coronavirus-driven recession is propping up the housing market. Homebuyer demand is surging despite GDP taking a historic nosedive in the second quarter, largely because Americans value the home more than ever and are willing to prioritize housing even as they cut back on other expenses. Additionally, the Fed is using low-interest rates to stimulate the economy, which is giving buyers more purchasing power and boosting home sales. But even with low rates, widespread unemployment and financial uncertainty mean not everyone who wants to buy a home is able to.”

    Redfin Chief Economist Daryl Fairweather

    According to a recent report by Point2, using data from Redfin, homebuyer profiles have also changed since the beginning of COVID. Full report: https://www.point2homes.com/news/us-real-estate-news/the-2020-us-homebuyer-profile.html

    What do we think we know?

    • McMansions are making a comeback. Maybe not 5,000 square foot houses, but definitely 3,000 square feet. (Inman)
    • Schools may reopen for in-person learning on 8/17 unless Governor Ducey extends the required delay in tonight’s press conference. In Chandler, where my kids go to school, the first quarter is now completely virtual with the possibility of in-person learning resuming mid-October.
      • Schools are a big part of location, location, location. If they are closed does the demand for a top-notch school district go down?
      • With kids at home, parents cannot go back to work or look for a new job; which will keep the unemployment numbers high.
      • Parents that are working from home are now also simultaneously teaching from home.
    • Both residential and commercial investors are backing away from new purchases. (Bisnow)
    • Economist Elliot Eisenberg said, “In yet another indication of a stalling national economy, after rising by ten percentage points a month in April, May and June, credit card purchases were flat in July and are now ten percent below their pre-Covid-19 level. This flatlining is probably due to rising coronavirus cases and subsequent behavioral changes in addition to state-imposed restrictions. The lack of continued improvement has primarily hurt restaurants/bars, gas stations, lodging, and airlines.”
    • Since February, rent growth is slowing at a greater rate in urban areas than it is in suburban areas. Reaffirming suburban migration trends. (Zillow)
    • Despite dropping to their lowest levels the “Investor Confidence Index” and “Startup Confidence Index,” investors in this sector are optimistic due to warp speed change, innovation, and increased adoption of new technologies within real estate. (MetaProp)

    What we do not know:

    • Typically, the second half of the year sells less than the first half. Starting in July we tend to see an increase in available listings and that increase remains through November. It is too early to tell if 2020 will fit the pattern.
    • 85% of college students want to return to campus. Colleges and universities want to reopen but how? Some economists question whether major universities will be able to weather this storm. What would Tempe look like without ASU? (Chronicles of Higher Education)
    • StreetEasy, a Zillow owned, NYC listing portal is implementing a 24-hour rule similar to the Clear Cooperation Policy. Non-compliance could lead to loss of the system’s tools and advertising. Will other advertising platforms follow suit? (Zillow)
    • eXp, coming off its most profitable quarter ever, purchased Showcase IDX with plans to create a consumer-facing search portal to compete with Zillow, Realtor.com, and Redfin. Is it possible to compete with portals of this size? (Inman)
    • In an effort to bring commercial tenants back into offices, landlords are now offering healthcare benefits through virtual health startup, Eden Health. Will it work? (Bisnow)
    • What is the future of commercial office space? Projections continue to indicate more trouble for the sector due to more permanent work from home options. (Bisnow)
    • The FED is playing a large role in bolstering the economy. The outcomes of the recent expiration of the expanded unemployment benefits created by the CAREs Act remains to be seen.
    • 1031 Exchanges may be on the chopping block again. Getting rid of the nearly 100-year-old tax program to fund Joe Biden’s childcare and elder-care proposal. What does that mean for real estate? (Inman)

    Too cool not to share:

    Loftus Hall, a 900 year old residential property in Ireland hit the market for $2.9M. In AZ an old house was built in 1980! Check it out here. https://www.irishcentral.com/dream-homes/irelands-haunted-house-sale

    Final Thoughts:

    There is a lot of information coming at us all of the time. After being the cause of a major economic downturn 12 years ago, the real estate industry is taking its role as the solution very seriously. We continue to overcome hurdle after hurdle. I am optimistic that we will continue to do so as we prepare for even more hurdles in the coming months.

    Copyright 2020 by Sarah Perkins

  • Afternoon Bite 8/3/2020 (Video)

    Every Monday afternoon Amber Kovarik and I talk about what happened this week in our local and national real estate market in 15 minutes or less.

    Today’s Takeaways:

    Communication with your clients is key. Be sure to share what is going on in real estate. The real estate industry is the driving force in our economic recovery. Things are happening quickly, demand is high, inventory is low, prices are increasing. This is a great time to be a seller and get top dollar. It is also a great time to buy with mortgage interest rates at historic lows.

    Lending:

    • Usually, there are about $2.5 trillion in loans being pushed through the pipeline, today it is $10 trillion. Four times more volume than usual!
    • Mortgages in forbearance declined again for the sixth week in a row. 7.74% of mortgages are in forbearance which is roughly 3.9 million loans. (MBA)
    • About 1.8 million loans in forbearance are seriously delinquent on their mortgage payments. (KCM)
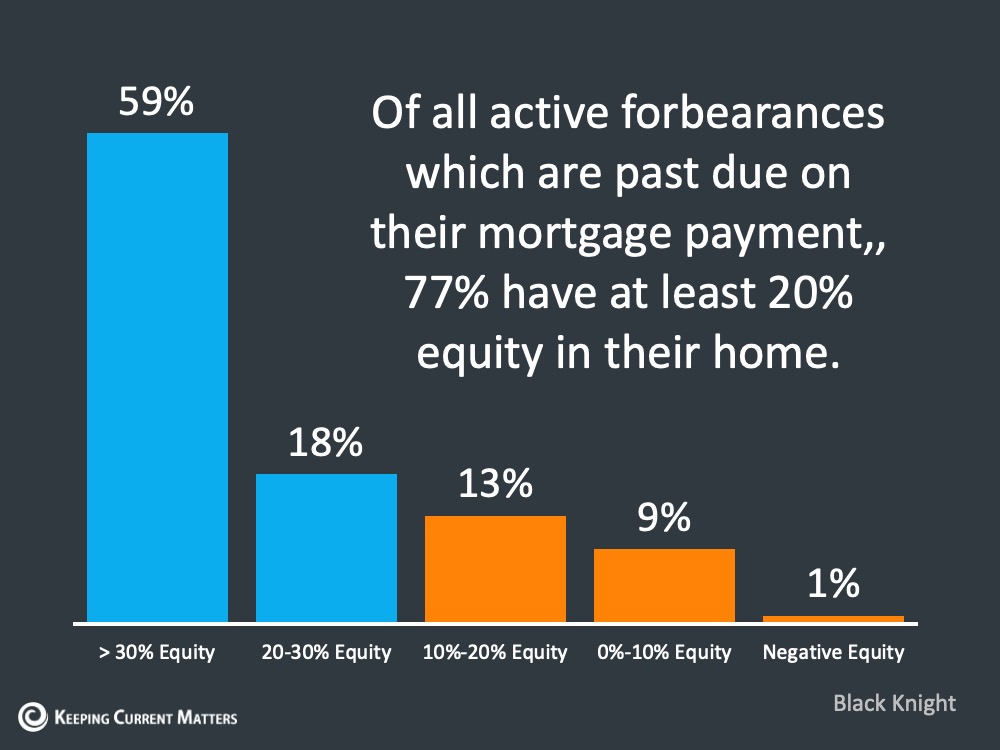
    • 77% of the past due owners have at least 20% equity and 90% have at least 10% equity. (KCM)

    The AZ Market:

    • Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 312.9 (matching the CMI’s record high from the spring of 2005), higher than the pre-COVID peak of 241, and more than double bottom we hit on May 15 of 145.2. Despite the over 15 point increase in the past week, the increase is slowing, slightly, which is good.
    • Supply: The available inventory continues to stabilize; it just happens to be at an extremely low level. As of yesterday, our inventory is 62.5% below normal. Active listings excluding under contract accepting backups (UCB) are down 42% year over year and 11% month over month.
    • Typically, the second half of the year sells less than the first half. Starting in July we tend to see an increase in available listings and that increase remains through November. It is too early to tell if 2020 will fit the pattern.
    • Demand: Pending sales are up 17% year over year, which is significant given how much lower our inventory is today. Our demand is 17.2% above normal and continues to increase.
  • Phoenix Area Real Estate Update 7/31/2020

    Realtors, lenders, buyers, and sellers are exhausted. The Spring and Summer home selling season has been crammed into two months. Not to mention the worldwide pandemic, economic uncertainties, delays in school re-openings, and a heated political climate. To say that there is a lot going would be an understatement. Despite the stress of the unknown, we do know that real estate is driving our economic recovery.

    The AZ Market:

    Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 312.9 (matching the CMI’s record high from the spring of 2005), higher than the pre-COVID peak of 241, and more than double bottom we hit on May 15 of 145.2. Despite the over 15 point increase in the past week, the increase is slowing, slightly, which is good.

    Supply: The available inventory continues to stabilize; it just happens to be at an extremely low level. As of yesterday, our inventory is 62.5% below normal. Active listings excluding under contract accepting backups (UCB) are down 42% year over year and 11% month over month.

    Typically, the second half of the year sells less than the first half. Starting in July we tend to see an increase in available listings and that increase remains through November. It is too early to tell if 2020 will fit the pattern.

    Demand: Pending sales are up 17% year over year, which is significant given how much lower our inventory is today. Our demand is 17.2% above normal and continues to increase.

    Sales & Prices: Phoenix metro area closed sales units are up 13% month over month and up 19% year over year. The median sales price is $315,000, up over 3% month over month and 11% year over year. Healthy appreciation is 3% annually.

    AZ News:

    • According to a recent WalletHub report, four Valley cities made it in the top 30 of the best places to rent in America. #1: Bismark ND, #10 Scottsdale, #18 Gilbert, #25 Chandler, #27 Peoria.
    • New unemployment claims in Arizona continued to decrease with 3.8% fewer claims than last week. (US Department of Labor)
    • Arizona hotel occupancy is down 26.3% year over year. Faring better than most other states. (Elliott Pollack)
    • Phoenix is still the biggest iBuyer market where they are buying the most houses. With that said iBuyer purchases are down 80% from January. (Mike DelPrete)

    Mortgage & Forbearance:

    • FHA mortgage interest rates increased slightly bringing an 18% drop in FHA refinance applications. Despite the slight increase in conventional refinances, total mortgage applications dropped 0.8% week over week. Refinances are still up 121% year over year. (Mortgage Bankers Association, MBA)
    • Mortgages in forbearance declined again for the sixth week in a row. 7.74% of mortgages are in forbearance which is roughly 3.9 million loans. (MBA)
    • About 1.8 million loans in forbearance are seriously delinquent on their mortgage payments. (KCM)
    • 77% of the past due owners have at least 20% equity and 90% have at least 10% equity. (KCM)

    Economy & Unemployment:

    • Stock market earnings for Q2 2020 were down 44.1% year over year. For comparison, Q4 2008 earnings were down 69.1% year over year. (FactSet)
    • As expected Q2 2020 GDP was horrible, declining 9.5%, the largest decline ever recorded (recorded started in 1947). Prior to this, the largest drop was Q1 1958 with a decrease of 2.6%. Given that the recovery started in May, Q3 2020 GDP has the potential for positive growth. (Elliot Eisenberg)
    • The restaurant industry continues to suffer some significant setbacks. In July 100,000 restaurants closed temporarily, the southern and western regions having the most closures. (National Restaurant Association)
    • An estimated 8,000 hotels across the country may close permanently by October. Some investors consider these shuttered hotels as potential options for affordable housing. (American Hotel & Lodging Association)
    • New unemployment claims rose again slightly this week from last week to about 1.4 million. This is the second week of increases after 16 weeks of decreases. This week’s increase was only 12,000 week over week. Continuing unemployment increased slightly this week up to around 17 million. (US Department of Labor)
    • Unemployment rising is not indicative of low home buying activity. Mortgage availability is a bigger indicator. (KCM)

    Rental Market:

    • Rents in expensive areas closer to major employment hubs are declining. San Francisco has seen the largest drops and is down 7.4%. New York City has dropped 6.4% from March to June. Decreases are expected to continue. Areas further out are seeing increasing rents. (Apartment Hub)
    • With the expiration of the CARES Act and the expanded unemployment benefits, renters stand to be the hardest hit. (Zillow)
    • 91.3% of apartment renters made their July payments, a drop of only 2.1% year over year. (National Multifamily Housing Council)
    • Single-family rentals continue to perform the best. Like the for-sale inventory, the available rental inventory in Phoenix metro is very low and has a growing demand. (Phoenix Business Journal)
    • If you know anyone struggling to make their payments, please refer them to https://housing.az.gov/

    Emerging Trends:

    • In a recent Realtor.com survey, 21% of respondents said they are more likely to buy a home sight unseen.
    • According to Redfin, other metro searches hit a record high of 27.4% in Q2 2020, up from 26% in Q1 2020. Top cities searched on Redfin are Phoenix, Sacramento, Las Vegas, Austin, and Atlanta.
    • A commercial leasing company with 30,000 renters based in Florida has added a doctor to its full-time staff to help with wellness and to create a greater sense of confidence for the renters. (Realty Magazine)
    • Despite early opposite projections, NAR membership has increased this year. As of June, there were 1.397 million members, an increase of 1.7% year over year. NAR expects 2020 could see an all-time high membership exceeding 1.4 million. (Inman)
    • Nationally, June buyer showings increased over 50% year over year according to ShowingTime.
    • 32% of employees want to work from home permanently and are willing to make changes to get more space and/or more affordable housing.  (Tom Ferry)
    • Green Street Advisors predict that office demand could drop by 10%-15% as more people work from home more permanently. They also expect this will push workers from expensive gateway cities to more affordable sunbelt cities like Phoenix, Raleigh, and Charlotte.
    • Multifamily investors pull back on affordable housing investments as the eviction moratorium is extended. ITEX Group President, Chris Akbari said, “If that moratorium goes through, they’re probably not going to be investing in new projects. They’re going to be investing their time and capital in trying to protect their current projects that are going to be suffering from not having income coming in and not being able to evict people who were unable to pay their rent.”

    Real Estate News:

    • June had a 21% sales increase, the largest monthly increase since 1968 when NAR started gathering this data. Also, in June we had the lowest available inventory in 20 years. Total sales are projected to be down 6.4% in 2020 from 2019. Yes, there are fewer buyers but more importantly, there are far fewer sellers. (Matthew Gardner, Windermere Chief Economist)
    • NAR’s Pending Home Sales Index shows June increased 6.3% year over year and increased 16.6% from May to June. “It is quite surprising and remarkable that, in the midst of a global pandemic, contract activity for home purchases is higher compared to one year ago,” NAR Chief Economist Dr. Lawrence Yun said in a statement. “Consumers are taking advantage of record-low mortgage rates resulting from the Federal Reserve’s maximum liquidity monetary policy.”
    • Sales of new single-family homes increased by nearly 14% year over year in June. The highest new home sales month since 2007. (US Census Bureau & HUD)
    • On Wednesday, Zillow announced they are allowing most of its employees to work from home indefinitely. Google, Facebook, Twitter, and Slack also recently made the same statement. (Zillow)
    • A new partnership has been formed between Zillow and D.R. Horton, the nation’s largest homebuilder. The builder’s new home buyers may sell their current house to Zillow and may be eligible for cash credits and free local moving services. (Zillow)
    • According to Redfin, with increasing competition and bidding wars, 20% of winning offers are waiving inspection contingencies.
    • Zavvie, an iBuyer comparison platform exclusively for brokerages, and EasyKnock, a home purchasing and leaseback startup, announced a new partnership to help more homeowners sell their property through a variety of options. (Zavvie & EasyKnock)

    Final Thoughts:

    Matthew Gardner, Windermere Chief Economist said, “Sales will continue to recover in most markets and will only be held back because of a lack of supply. Of course, nobody can deny that we are still in very unique times, and significant uncertainty remains, but housing is performing relatively well and, as I have said to you for the past few months, I stand by my position that housing will lead us out of the current economic contraction.”

    Copyright 2020 by Sarah Perkins

  • Phoenix Area Real Estate Update 7/24/2020

    It is ironic that real estate caused the Great Recession and only 10 years later real estate is driving our economic recovery. As we face our economic reality of today; we have to look at the good (real estate), the bad (employment struggles and school closures), and the ugly (unemployment).

    “While other segments of the economy may be stuttering, the housing market continues to be a bastion of hope. Today’s (builder confidence) report indicates builders are confident that consumers will purchase new homes in this era of rock-bottom mortgage rates, despite the high unemployment numbers and other negative economic reports.”

    Bill Banfield, Executive Vice President of Capital Markets for Quicken Loans

    The Good: Real Estate

    • Nationally, homes are selling at the fastest rate ever recorded, on average within 20 days. (Zillow)
    • From May to June home builder confidence went up, housing starts increased over 17%, permits increased by 2%, and single-family completions increased by 9.6%. (US Census Bureau)
    • The national median sales price hit an all-time high in June at $311,300. (Redfin) This makes June the 100th month in a row with median sales price increases. (NAR)
    • Closings were up nearly 21% in June from May. We are now (only) 11.3% behind June 2019 in closed units. (NAR)
    • Industrial real estate, which was growing prior to March, has increased in appreciation and demand. Warehouses and large distribution centers are in high demand across the country. “The reality is these numbers are not the byproduct of the COVID pandemic; they are in spite of the COVID pandemic,” Colliers International principal Matthew Stauber said. (Phoenix Business Journal)
    • Mortgages in forbearance declined again for the fifth week in a row. 7.8% of mortgages are in forbearance which is about 3.9 million loans. (MBA)

    “The sales recovery is strong, as buyers were eager to purchase homes and properties that they had been eyeing during the shutdown. This revitalization looks to be sustainable for many months ahead as long as mortgage rates remain low and job gains continue.”

    Dr. Lawrence Yun, Chief Economist for NAR

    The AZ Market:

    Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 297.5, higher than the pre-COVID peak of 241 and significantly up from the bottom of 145.2 we hit on May 15. Up over 18 points in the past 7 days.

    Supply: The available inventory has started to stabilize. The drastic listing count decreases have slowed and have remained flat for the past 2-3 weeks. This stabilization happens to be at an extremely low level. As of yesterday, our inventory is over 61% below normal. Our total active inventory is down 29% year over year. When we remove under contract accepting backups (UCB) we are down 43% year over year.

    Demand: Pending sales are up 17% year over year, which is significant given how much lower our inventory is today. Our demand is 14.6% above normal and increased by over 3% in the past seven days.

    Sales & Prices: Phoenix metro area closed sales are up 20% month over month and up 13% year over year. The median sales price is $315,000, up nearly 5% month over month and 12% year over year. Healthy appreciation is 3% annually.

    Southeast Valley New Listings, Pendings, and Closings:  This week over week comparison for Tempe, Mesa, Chandler, Gilbert, Apache Junction, and Queen Creek since March 15 shows the very recent supply stabilization. Closings always spike at the end of the month.

    The Bad: Employment Struggles & School Closures

    • Commercial office space occupancy protocols are being adjusted. The plans of phasing employees back into the office in groups of 25% has not worked out. To date, many office buildings are at around 5% occupancy. Rent payments remain near 100%. (Phoenix Business Journal)
    • Employers are looking for childcare options in order to get employees back to work.
    • “The back-to-work and back-to-school efforts are certainly linked,” Global Health Crisis Coordination Center Executive Director Ken Berta said, “We will need to get our children safely back to school to get all employees back to work.” (Bisnow)
    • Demand is increasing for private schools, tutors, and small-group homeschooling options. Given these options are only available to those who can afford it, there is a growing concern of an even larger disparity between the haves and the have nots.
    • It is unclear how the school closures will affect housing and employment, but the potential influences are significant. If schools do not reopen and there is a shift away from traditional education, people will not base their moves on school districts potentially changing the geographic distribution of wealth.

    The Ugly: Unemployment

    • First-time unemployment claims hit 1.4 million last week, up 109,000 from the previous week. This is the first week over week increase in 15 weeks. (Bureau of Labor Statistics)
    • Continuing unemployment claims dropped by 1.1 million to 16.2 million last week. Indicating new hires are outpacing layoffs. (Bureau of Labor Statistics)
    • This does not include the roughly 13 million independent contractors receiving benefits through the Pandemic Unemployment Assistance Program. (Wall Street Journal)
    • Both the expanded unemployed and the independent contractor benefits through the CARES Act are due to expire on July 31.
    • Rather than extending unemployment benefits for a short time, Congress is looking to create a new version of the CARES Act, but it is unlikely to happen before August.

    Other AZ News:

    • Unemployment in Arizona in June was 10%, lower than the national rate of 11.1%. (Bureau of Labor Statistics)
    • Arizona’s job losses are less than 48 states, behind only Utah. (Elliott Pollack & Company)
    • In June jobs were down 3.3% in Arizona year over year, nationally they were down 8.7% year over year. (Elliott Pollack & Company)
    • Greater Phoenix is the strongest employment market in the country; jobs are down only 3% year over year. (Elliott Pollack & Company)
    • Business applications are up 59.5% year over year. (Elliott Pollack & Company)
    • Single-family permits increased 4.3% year over year in the Phoenix metro area. (Elliott Pollack & Company)
    • Governor Ducey announced the extension of the moratorium on residential rental evictions from July 25 to October 31. (Governor’s Office)
    • A new plan has been created by the city of Phoenix officials to add 50,000 new housing units by 2030. According to a housing gap analysis, Phoenix needs an additional 163,067 housing units to accommodate the population growth.

    Emerging Trends:

    • Retail sales increased by 18.2% in May and 7.5% in June. Retail is now up 1.1% year over year. (US Census Bureau)
    • With the looming CARES Act expiration, publicly-traded multi-family property owners are adjusting protocols as they intend to collect past due rents or start the eviction process.
    • According to a recent Yelp survey 53% of the roughly 24,000 restaurants that have closed since March 1, have closed permanently. Other permanent closure rates are 35% for retail, 26% for gyms, 24% for beauty shops. The restaurant closures have sparked commercial investor interest and they are out looking for deals. (Restaurant Consultant Paul Ficalora)
    • The Fannie Mae monthly National Housing Survey which measures consumer confidence for housing shows a V-shaped recovery. Consumer sentiment for buying has made up all of the losses since March and is now matching November 2019 numbers. Consumer sentiment for selling is increasing and is on pace to fully recover by next month.

    Other Real Estate News:

    • According to the Mortgage Bankers Association this week, purchase applications are up 19% year over year, continuing the increase for nine consecutive weeks. Refi applications are up 122% year over year.
    • The First Time Homebuyer Pandemic Savings Act is a newly proposed act that allows first time home buyers to use up to $25,000 from their 401K as down payment, tax-free and penalty-free. It would expire on 12/31/2021. This new act builds on and extends existing provisions of the CARES Act that allows new and repeat buyers to use up to $100,000 of their 401K penalty-free, but not tax-free, and is due to expire on 12/31/2020.
    • The motion for a preliminary injunction filed by Top Agent Network (TAN) against NAR’s Clear Cooperation Policy has been denied. This is after their motion of a restraining order was denied in late May. The judge also stated that TAN is “unlikely to succeed” in their argument. Additional motions have been filed by brokerages and associations. (Inman)
    • The judge ruled against Realogy’s lawsuit forcing SIRVA to complete the $400 million acquisition of Realogy’s relocation company, Cartus. The judge stated Realogy violated the deal’s terms but could pursue a $30 million termination fee.
    • Realtor.com created a new Seller’s Marketplace platform offering traditional and iBuyer selling options. Rather than launching their own iBuyer, Realtor.com partnered with Opendoor, EasyKnock, HomeGo, and WeBuyHouses.com.
    • The Florida Panhandle is the best place to own a vacation rental according to rental management platform Rented Inc. Phoenix is #6.
    Source: Rented.com *based on a 3 bedroom, 2 bath stand-alone home.

    Final Thoughts:

    Arizona is leading the pack in our economic recovery. Real estate is a driving force in that recovery. As we continue in these uncertain times it is important to be cognizant of the facts in order to part of the solution.

    Copyright 2020 by Sarah Perkins

  • Afternoon Bite 7/20/2020 (Video)

    Every Monday afternoon Amber Kovarik and I talk about what happened this week in our local and national real estate market in 15 minutes or less.

    Today’s Takeaways:

    Know your numbers to communicate what is really happening in real estate. Provide good information to buyers, sellers, and borrowers. Without actual numbers, it is difficult for a potential consumer to make decisions.

    • According to the US Census Bureau Household Pulse Study, of the nearly 74 million renter-occupied housing units in the country, roughly 16% did not make their June payment. And of the nearly 150 million owner-occupied properties in the country, 5.5% did not make their June payment.
    • In Arizona, of the just over 1.6 million renter-occupied properties 9% did not make their June payment. And of the nearly 3.5 million owner-occupied properties in AZ, only 3.3% did not make their June payment. (US Census Bureau Household Pulse Study)
    • Mortgages in forbearance declined again, for the fourth week in a row. 8.18% of all mortgages are in forbearance, down from 8.39% the previous week. (Mortgage Bankers Association)
    • One-third of mortgages in forbearance are late on their payments. Two-thirds are current. (KCM)
    • Going deeper, of all the mortgages in active forbearance that are late on their mortgage, 77% have at least 20% equity. Only 10% of the past due mortgages have 10% or less equity. (Black Knight)
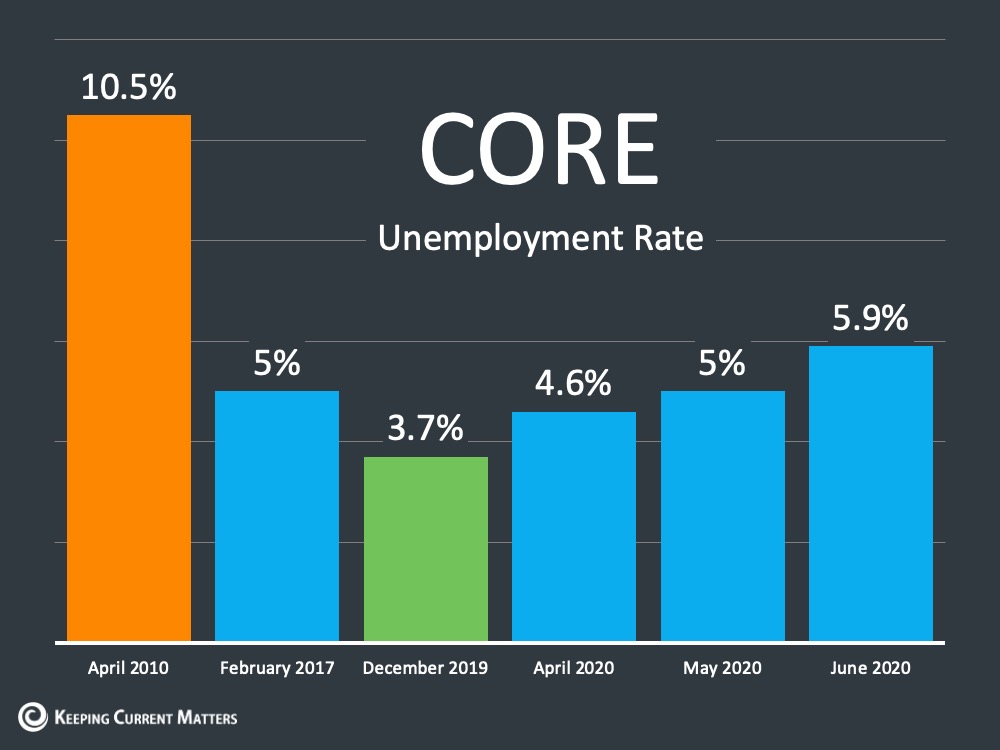
    • There are two types of unemployment temporary and Core or permanent unemployment. June’s Core unemployment was 5.9%. For comparison, it was 10.5% in April 2010 and 5% in February 2017. (KCM)
    • According to the US Census Bureau, 46% of the people who do not have a job and are over the age of 18 live in households with an income of less than $50,000 a year. These households tend to rent.
    • As economies reopen, we will likely see increases in listings. However, with the surges of new COVID-19 cases across the country (AZ isn’t the worst anymore!) sellers may delay selling, keeping inventories low and prices rising quickly.
    • As the CARES Act is set to expire at the end of the month, delinquencies may rise and that may impact housing however, with the high equity rates, the potential “distressed“ listings will still be regular sales.

    Conclusion:

    Windermere Chief Economist Matthew Gardner said, “We are exactly 120 days into this pandemic and, as much as there were some who fully anticipated that the U.S. housing market would have collapsed already, it simply hasn’t happened — and won’t happen.”

  • Phoenix Area Real Estate Update 7/17/2020

    Consumer sentiment has the greatest impact on our economy. It is more powerful than any piece of information or event. With today’s incredibly polarized media where everyone has an agenda, it is almost impossible to get accurate information. The headlines often conflict with what is actually happening, let’s talk about the real numbers.

    For example, look at the second quarter stock market returns versus the economic data. Investors have no idea why the markets ended so well when there was so much bad news in every headline. The S&P 500 increased by nearly 20%, the Dow Jones increased by nearly 18%, and the NASDAQ was up nearly 31%! Almost all of March’s losses were made up and the NASDAQ actually increased from previous highs. (Jeremy Kisner, Surevest Wealth Management)

    Suze Orman, a personal finance expert, not a real estate expert, is advising that now is a bad time to buy a house. That is as helpful as a dentist doing your taxes. Unfortunately for us, she has a large audience.

    Lendingtree released a study stating that 87% of home sellers are concerned about selling due to the pandemic, yet 372,000 homes sold in June. Our pendings are higher than they were 12 months ago and prices are increasing. Houses are selling faster today than they have in years.

    Last week I wrote about a report, from Apartment List, stating 32% of Americans did not make their housing payment the first 3 days of July. The same report said 30% did not make their June payment in the first 3 days of the month. These numbers were so high I dug deeper and found better data.

    According to the US Census Bureau Household Pulse Study, of the nearly 74 million renter-occupied housing units in the country, roughly 16% did not make their June payment. And of the nearly 150 million owner-occupied properties in the country, 5.5% did not make their June payment.

    In Arizona, of the just over 1.6 million renter-occupied properties 9% did not make their June payment. And of the nearly 3.5 million owner-occupied properties in AZ, only 3.3% did not make their June payment. (US Census Bureau Household Pulse Study)

    Forbearance:

    Mortgages in forbearance declined again, for the fourth week in a row. 8.18% of all mortgages are in forbearance, down from 8.39% the previous week. (Mortgage Bankers Association)

    One third of mortgages in forbearance are late on their payments. Two thirds are current. (KCM)

    Going deeper, of all the mortgages in active forbearance that are late on their mortgage, 77% have at least 20% equity. Only 10% of the past due mortgages have 10% or less equity. (Black Knight)

    Price Projections:

    There is a wide range of price projections emerging from top real estate experts. Mortgage Bankers Association projects a 4% annual appreciation and Corelogic, a clear outlier, expects a 6.6% depreciation. David Childers at KCM reached out to the chief economist at CoreLogic asking about this projection and was told it was entirely based on expected low demand solely due to unemployment. They did not address the lack of supply. That seems very odd when supply and demand are the fundamentals of pricing.

    Unemployment:

    According to the US Census Bureau, 46% of the people who do not have a job and are over the age of 18 live in households with an income of less than $50,000 a year. These households tend to rent.

    1.3 million people filed for unemployment for the first time this week, continuing the week over week decline for 15 weeks straight.

    There are two types of unemployment temporary and Core or permanent unemployment. June’s Core unemployment was 5.9%. For comparison, it was 10.5% in April 2010 and 5% in February 2017. (KCM)

    Future of Housing:

    Windermere Chief Economist Matthew Gardner said, “We are exactly 120 days into this pandemic and, as much as there were some who fully anticipated that the U.S. housing market would have collapsed already, it simply hasn’t happened — and won’t happen.”

    As economies reopen, we will likely see increases in listings. However, with the surges of new COVID-19 cases across the country (AZ isn’t the worst anymore!) sellers may delay selling, keeping inventories low and prices rising quickly.

    As the CARES Act is set to expire at the end of the month, delinquencies may rise and that may impact housing however, with the high equity rates, the potential “distressed“ listings will still be regular sales.

    The AZ Market:

    Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market, below 100 is a buyer’s market, prices rise at 110, and drop at 90). Yesterday it was 279.4, higher than the pre-COVID peak of 241 and significantly up from the bottom of 145.2 we hit on May 15. Up over 21 points in the past 7 days.

    Supply: Our local inventory has been dropping every day since May 12. As of yesterday, our inventory is over 60% below normal. Our total active inventory is down 30% year over year. When we remove under contract accepting backups (UCB) we are down 43% year over year. We desperately need more listings.

    Demand: Pending sales are up 16% year over year, which is a big deal given how much lower our inventory is. Our demand is 11.5% above normal and increased nearly 4% in the past seven days.

    Sales & Prices: Phoenix metro area closed sales are up 10% year over year. The median sales price is up 5% month over month and over 11% year over year. Healthy appreciation is 3% annually.

    Southeast Valley New Listings, Pendings, and Closings:  This week over week comparison for Tempe, Mesa, Chandler, Gilbert, Apache Junction, and Queen Creek since March 15 shows the continuation of demand outpacing supply. Closings always spike at the end of the month.

    Other AZ News:

    • Phoenix ranks #16 in the country for in most valuable residential real estate with a total value of $484 billion. (Lendingtree)
    • According to WalletHub Phoenix is the 41st most stressed-out city in the country. We have among the lowest financial, family, health, and safety stress but we are experiencing incredibly high work stress because we have the strongest job market in the country and have lost the fewest jobs. This means more of us are trying to juggle the stress of the world today while continuing to perform at work.
    • Phoenix area builder permits pulled in June increased by 9.6% year over year. (Home Builders Association of Central Arizona)
    • According to the Realtor.com Housing Market Recovery Index, the Phoenix metro area has completely recovered from the pandemic slow down. This index combines supply, demand, price, and days on market.

    Emerging Trends:

    • Realtor.com traffic hit an all-time high in June with 86 million unique visitors, breaking the previous record of 85 million in May. (Move.com)
    • Household savings rates are up 8% year over year, the highest since the early 1990s. (KCM)
    • Spending by the bottom 25% of earners has recovered from the 23% drop in March, while spending by the top 25% of earners is still down 17% though up from the 31% drop in March. The discretionary spending reduction continues to hurt the low-income earners who are the often the workers at salons, movie theaters, and restaurants. (Elliot Eisenberg)
    • Commercial real estate investors are starting to buy office buildings at 10-30% discounts in gateway cities. (Bisnow)
    • Meanwhile, industrial real estate sales prices continue to increase. (Bisnow)

    Other Real Estate News:

    • Mortgage interest rates hit all-time lows, again, keeping the demand high as every percentage drop equals roughly $40,000 of buying power.
    • According to Zillow, luxury home listings are recovering quickly while affordable home listings continue to decline, down 29% year over year.
    • Dotloop, the Zillow owned competitor of Skyslope, has a new third party data sharing policy. Agents using the platform need to opt-out of sharing the data rather than the typical opt-in. (Zillow)
    • In October, when the US Supreme Court reconvenes, they will determine whether or not the structure of the Federal Housing Finance Agency (FHFA) is constitutional. They recently ruled that the structure of the CFPB was unconstitutional.
    • According to the recently released Consumer Federation of America study, agent profiles on Zillow are the most useful for consumers; compared to Realtor.com, Yelp, Facebook, and Homelight.
    • New Silicon Valley start-up, Juno, is “reimaging” multi-family building. The prop-tech company is looking to disrupt the building process. (Jim Dalrymple, Inman)
    • In Fort Worth TX, a struggling multifamily property owner is suing the US Government challenging the eviction moratorium in the CARES Act. (Bisnow)
    • Knock.com is pivoting their model and instead of purchasing property they now offer mortgage financing, bridge loans, and concierge services. They are no longer working direct to consumer and will only partner with real estate agents.

    Final Thoughts:

    The negative news is growing at an alarming rate and the headlines are misleading. With so much bad info, it is important that you talk to your clients about what is really happening in real estate. Share this info, make videos, call your sphere, continue being the solution during these uncertain times.

    Happy Birthday Mom! I can’t wait until I can see you in real life again!

    Copyright 2020 by Sarah Perkins

  • Afternoon Bite 7/13/2020 (Video)

    Every Monday afternoon Amber Kovarik and I talk about what happened this week in our local and national real estate market in 15 minutes or less.

    Today’s Takeaways:

    The AZ Market:

    • Listings under contract are up nearly 20% year over year while active inventory is down 43% year over year. There are roughly 8800 available listings in our market, we should have 25,000 minimum for a market of our size.
    • Monthly median sales price increased by over 11% year over year. Supply and demand.
    • We have 1.5 months of inventory. Normal used to be 6. Three sounds great.
    • Nationally inventory has been dropping since September of 2019.
    • Mortgages in forbearance dropped for the 3rd week in a row.

    Other Real Estate News:

    • After a decade of growth in public transportation use, the car is king again.
    • Pop-up drive-in theaters are emerging in mall parking lots and other unused large open commercial spaces.
    • State and local legislators across the country working to pass upzoning laws. This would allow multi-family housing structures on land zoned for single-family residences.
    • Commercial mortgage-backed security delinquency rates increased to 10.32% in June, nearly hitting an all-time high. The June 2019 delinquency rate was 2.84%.
    • According to the Federal Reserve, the results for the Dodd-Frank mandated stress tests required for banks show that the largest American banks could lose as much as $47.6 billion on commercial real estate loans over the next two years.
    • According to a study by Apartment List released Wednesday, 32% of Americans did not make a complete July housing payment within the first three days of the month. This number will decrease throughout the month. In June it dropped from 30% to 11% of people who did not make their June housing payment in full.
    • Last week the US Supreme Court ruled that the Consumer Financial Protection Bureau (CFPB)’s structure (not the agency itself) is unconstitutional.
    • Last week Airbnb announced renters under 25 who have fewer than 3 positive reviews will not be able to book single-family residences near where they live.
    • The new Chinese National Security Law cracking down on dissent in Hong Kong is making American real estate investors question their investments.
    • Quicken Loans filed for IPO as Rocket Companies.
    • The real estate industry received 3% of the total money distributed by the Paycheck Protection Program (PPP) 
  • Phoenix Area Real Estate Update 7/10/2020

    Maybe the 10 years of growth were the calm before the storm. Even if it was not, the storm is here now. As we adapt to extreme inventory shortages, get comfortable in our masks, and try to stay healthy we now face a new challenge, surviving economic re-closures. Pending sales are up, buyer demand is up, inventory is down.

    “This has been a spectacular recovery for contract signings, and goes to show the resiliency of American consumers and their evergreen desire for homeownership,” NAR Chief Economist Lawrence Yun said, “This bounce back also speaks to how the housing sector could lead the way for a broader economic recovery.” I hope that real estate can continue to lead the economy towards recovery despite the significant headwinds we are now facing.”

    The AZ Market:

    Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market and below 100 is a buyer’s market. Prices rise at 110 and drop at 90). Yesterday it was 258.3, higher than the pre-COVID peak of 241 and significantly up from the bottom of 145.2 we hit on May 15. Up over nearly 26 points since July 1.

    Supply: Our local inventory has been dropping every day since May 12. As of yesterday, our inventory is 58% below normal. Our total active inventory is down nearly 28% year over year. That sounds like a lot; then when we remove under contract accepting backups (UCB) we are down 42% year over year. We desperately need more listings.

    Demand: Pending sales are up over 6% month over month and up 17% year over year, which is a big deal given how much lower our inventory is. Our demand is 7.7% above normal and increased by nearly 6% in the past fourteen days. According to Showing Time, in AZ, physical requests which recovered and from the March-April drop are dipping again, likely due to the low inventory. We are now 9.6% down year over year and 17.8% off the pre-COVID peak. Again, buyers cannot look at (or buy) houses that are not for sale.

    Sales & Prices: Phoenix’s closed sales are up 5.5% year over year. The median sales price is up 8.2% year over year.

    Southeast Valley New Listings, Pendings, and Closings:  This week over week comparison for Tempe, Mesa, Chandler, Gilbert, Apache Junction, and Queen Creek since March 15 shows this week’s increased demand and decreased supply. Closings always increase at the end of the month.

    Other AZ News:

    • Amazon paid $19.85M for 91.5 acres in Goodyear.
    • Mountainside Fitness is suing Governor Ducey over the recent executive order closing gyms due to the surge in new COVID cases in AZ. The gym alleges that the order violates the AZ constitution by not allowing the company to prove that they are not a health risk.
    • A partnership with Davcon Aviation and Mesa Hangar to create a $60M aviation project breaks ground in a Mesa opportunity zone.
    • Wallethub released a study of the 2020 best and worst cities for first time home buyers. Gilbert ranked #5 and Chandler ranked #11. For the full list of cities and their rankings:  https://wallethub.com/edu/best-and-worst-cities-for-first-time-home-buyers/5564/

    Unemployment:

    Initial unemployment claims this week dropped again to 1.3 million, slightly lower than the previous week’s 1.5 million, which continues the weekly decline every week since the end of March.

    4.8 million jobs were added in June dropping the unemployment rate to 11.1% from May’s 13.3%. According to the US Department of Labor, the real estate sector, not including rentals, added over 18,000 jobs. The late June re-closures and re-opening delays will be seen in July’s unemployment report. Most economists are not as optimistic as they were mid-June. While jobs are still down 14.7 million since February, the 7.5 million total jobs regained in May and June is quite impressive.

    66.5% of the unemployed are under 35. And of that group, 53.1% are under 25. According to the NAR buyer and seller report only 3% of homeowners are under 25.

    Forbearance:

    Of all active mortgages in forbearance that are past due on their payment, 77% have at least 20% equity in their home. At least 90% have positive equity, reducing the likelihood of a flood of foreclosures.

    Mortgages in forbearance dropped for the third week in a row. According to the Mortgage Bankers Association, 8.39% of mortgages are in forbearance, down from 8.47% last week. Borrowers are opting out and looking at other relief options.

    Emerging Trends:

    • Historic low rates have made homes more affordable despite the higher price tags. According to NAR today only 14.6% of income is needed to make a mortgage payment. In June of 2018 it was 18.2% and the historic normal is 21.2% of income.
    • After a decade of growth in public transportation use, the car is king again. More people are leaving city centers where cars are less necessary and going to smaller metros with fewer public transportation options.
    • After decades of closures, drive-in movie theaters are making a come back. Pop-up drive-in theaters are emerging in mall parking lots and other unused large open commercial spaces.
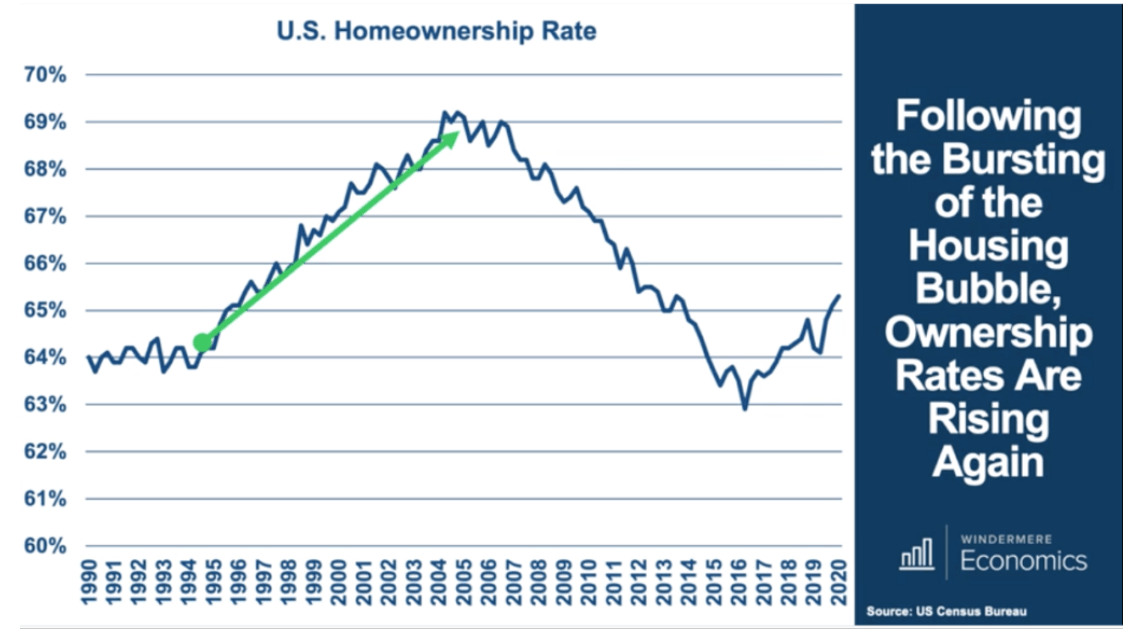
    • Homeownership rates increased from 1990 to 2006. In 2006 they began dropping bottoming out in 2016 at levels lower than they have been since 1990. Since 2016 they have again been on the rise. However, builders have not kept up with the rising homeownership rates leading to historically low inventory levels today. These low inventory levels are pushing prices up faster than incomes are rising.
    • In response to the skyrocketing home prices, state and local legislators across the country working to pass upzoning laws. This would allow multi-family housing structures on land zoned for single-family residences. Oregon and Minneapolis passed these laws in 2019. These laws face staunch opposition as multi-family buildings often reduce the value of the neighboring single-family properties.
    • Commercial mortgage-backed security delinquency rates increased to 10.32% in June, nearly hitting an all-time high. The June 2019 delinquency rate was 2.84%.
    • According to the Federal Reserve, the results for the Dodd-Frank mandated stress tests required for banks show that the largest American banks (Wells Fargo, Citibank, Chase, and Bank of America) could lose as much as $47.6 billion on commercial real estate loans over the next two years.
    • According to a study by Apartment List released Wednesday, 32% of Americans did not make a complete July housing payment. Of the 32%, 13% made a partial payment and 19% made no payment. 36% of renters did not make their full payment. Of the 30% of homeowners that did not make a full payment, 18% made no payment. These numbers seem very high.
    • *Please note this info from June data, “It continues to be the case that the majority of payments missed in the first week of the month are made up with late payments. 89 percent of respondents reported that they had paid their June bill in full as of the first week of July. This is consistent with the end-of-month payment rate for prior months.” For more details https://www.apartmentlist.com/research/july-housing-payments

    Other Real Estate News:

    • Last week the US Supreme Court ruled that the Consumer Financial Protection Bureau (CFPB)’s structure is unconstitutional. The agency was created in the Dodd-Frank Act of 2010 to protect consumers from predatory lending practices. They ruled that the whole agency is not unconstitutional. Chief Justice John Roberts stated, “The CFPB’s single-director configuration is also incompatible with the structure of the Constitution, which — with the sole exception of the Presidency — scrupulously avoids concentrating power in the hands of any single individual.”
    • Last week Airbnb announced new policies to crack down on party houses to further prevent large gatherings, especially as COVID cases surge across the country. Renters under 25 who have fewer than 3 positive reviews will not be able to book single-family residences near where they live.
    • The new Chinese National Security Law cracking down on dissent in Hong Kong is making American real estate investors question their investments. Soon Hong Kong may no longer be a destination for future real estate investment. These investors are looking at other global opportunities.
    • Quicken Loans filed for IPO as Rocket Companies.
    • The real estate industry received 3% of the total money distributed by the Paycheck Protection Program (PPP) 
    • Economist Elliot Eisenberg said, “As part of the CARES Act, lenders that allow borrowers to defer debt payments may not report those payments as late to credit-reporting firms. As such, borrower FICO scores are no longer as good at separating good borrowers from the bad. As a consequence, many lenders are compensating by tightening standards for all consumer loans, credit cards, and auto loans, depriving deserving households of credit, until they can figure out Plan B.”

    Final Thoughts:

    NAR expects to see a total of 4.93 million resale transactions in 2020. In 2021 they project resale transactions to hit 5.35 million. In 2019 we had 5.34 million resale transactions. Some experts say these are lofty goals. However, with proper guidance and education, we can make it happen.

    This is a great time to sell. Do not get distracted by the negative media; the best way to be part of the solution is by getting accurate information out and guiding your clients with the facts.

    Copyright 2020 by Sarah Perkins

  • Phoenix Area Real Estate Update 6/26/2020

    The top real estate experts and economists expect to see a strong housing market through the summer. While there is no reason to expect anything but positive growth, there are a number of outside factors that could negatively impact the housing market. It is important to be mindful while being optimistic. Shifts of this magnitude have never happened so quickly and there are no guarantees. This is not the market for “wait and see.”

    The AZ Market:

    Cromford Market Index (CMI): The CMI is the best leading indicator available (balance is 100, above 100 is a seller’s market and below 100 is a buyer’s market. Prices rise at 110 and drop at 90). On March 20, the CMI peaked at 241, and yesterday it was at 214.3, up from the bottom of 145.2 we hit on May 15 and up over 20 points in the past seven days.

    Supply: Our local inventory has been dropping every day since May 12. As of yesterday, our inventory is 54% below normal. In the past seven days we have dropped by 2.4%. Our total active inventory is down nearly 28% year over year. That sounds like a lot; then when we remove under contract accepting backups (UCB) we are down 42% year over year. We desperately need more listings.

    Demand: Pending sales are up over 18% month over month and up 15% year over year. Our demand is 1.4% below normal and increased by nearly 10% in the past fourteen days. According to Showing Time, in AZ, physical requests peaked on February 22 and then immediately dropped by 63% through mid-April. We made up that drop and then some and have seen a slight decrease of nearly 2% in the past week. Buyers cannot look at houses that are not for sale. Inventory continues to struggle to keep up with demand.

    Sales & Prices: Phoenix’s closed sales are down just over 15% year over year; nationally we are down 27% year over year. The median sales price is 8.4% up year over year. Dr. Lawrence Yun, NAR’s chief economist, said, “Sales completed in May reflect contract signings in March and April — during the strictest times of the pandemic lockdown and hence the cyclical low point. Home sales will surely rise in the upcoming months with the economy reopening and could even surpass one-year-ago figures in the second half of the year. New home construction needs to robustly ramp up in order to meet rising housing demand. Otherwise, home prices will rise too fast and hinder first-time buyers, even at a time of record-low mortgage rates.”

    Southeast Valley New Listings, Pendings, and Closings:  This week over week comparison for Tempe, Mesa, Chandler, Gilbert, Apache Junction, and Queen Creek since March 15 shows this week’s increased demand and decreased supply. Only time will tell if it is pent up demand or actual demand. Based on February’s demand it is likely to be actual. Closings always increase at the end of the month.

    Other AZ News:

    Multi-billion dollar business, Smead Capital Management announced their relocation from Seattle to the Camelback Corridor in Phoenix. Despite higher taxes in Phoenix, the company’s president and CEO, Cole Smead, is moving the company because of the lower cost of living and a larger pool of talent for recruiting in Phoenix. He also stated, “The unrest that has taken place in the city of Seattle … there really is not a downtown business community today.”

    Arizona gained 45,300 jobs in May, which is impressive since the economy did not reopen until May 16. That is an increase of 2.4% and above the national average. Arizona’s unemployment rate through May was 8.9% which is better than the national unemployment rate of 13.3% through May. Arizona is second to Utah for employment performance year to date, meaning our state retained the second most jobs of any state by percentage of the population.

    Phoenix metro is the fastest-growing major employment market in the country year to date. That means we have lost the fewest jobs, as a population percentage, in the country. This could have major implications for real estate. A larger employed population could lead to fewer potential issues down the road.

    Economy:

    Prior to COVID, we used quarterly economic data to analyze the market and create projections. Today’s environment is changing too quickly for that data to be sufficient so we have to use other options, daily or weekly data, known as high-frequency data, which is what we have to use today to analyze the economy. These are high-frequency data points:

    • Vehicle sales were up 44% in May over April. Vehicle sales make up about 20% of retail sales. Year over year retail sales are down only 6.1%.
    • Hotel occupancy rates reached nearly 42% last week, up from the bottom of 32% the week of May 18. It is still down 42% year over year.
    • TSA’s weekly traveler report shows the week of June 13 we were down 82% year over year which is better than the 91% year over year drop we had in mid-May.
    • According to OpenTable, restaurant reservations are down 64% year over year as of June 18.
    • Seated diner traffic in Phoenix is down 51.2% year over year, an improvement from the year over year decline of 84% last month.
    • Steve Hafner, the CEO of OpenTable, predicts up to 25% of US restaurants will permanently close. The Independent Restaurant Coalition predicts up to 80% of independent restaurants will close permanently. There are roughly one million restaurants nationwide, that prior to the pandemic employed roughly 15.6 million people.

    National Unemployment:

    There were 1.4 million new unemployment claims filed this week bringing the total number from mid-March to 47 million. Continuing claims dropped slightly to 19.5 million. Check out this chart from Matthew Gardner, Chief Economist for Windermere.

    Forbearance:

    According to Elliot Pollack, there are roughly 100 million loans, of varying types, on some sort of COVID relief program. This includes 4.2 million mortgages, 79 million student loan accounts, 7.3 million car loans, 1.3 million personal loans, and millions not paying rent or credit card balances.

    The good news (for lack of a better term) came from the Mortgage Bankers Association when they announced mortgage loans in forbearance decreased for the first time since March. For the week ending on June 14 total mortgages in forbearance dropped to 4.2 million, down from 4.3 million the week before. 8.48% of mortgages are currently enrolled in a forbearance program.

    Emerging Trends:

    • According to Zillow 2.7 million adults aged 18-25 have moved back in with their parents during March and April. That is a 9.7% increase in April year over year and 1.4% of the national rental market.
    • Home improvement spending is up. According to Lending Tree personal loans for home improvement is up nearly 8% year over year.
    • Large office buildings and other commercial property owners are re-evaluating policies regarding elevator and stair usage in order to maintain social distancing. High rise office buildings have to come up with new solutions to transport people to their destination.
    • Worldwide mass transit demand is down 59% since January.
    • According to the Urban Land Institute (ULI), there are about 13.5 million families renting making up about 1/3 of total renters. The ULI is calling for developers to create more rental options for families as this sector is expected to grow.
    • Shifts between the suburbs and the city are cyclical. From 2010 through 2018 cities grew faster than suburbs but as time went on the city demand slowly decreased as the suburban demand increased faster. Today’s shift towards the suburbs started in 2019 but was significantly escalated by the pandemic.
    • Vacation rentals are in high demand. The ones that are doing the best are the ones within about 2.5 hours of a large metro area. More people are driving to their vacations than flying.
    • As more businesses relocate to the suburbs, car dependency is expected to grow.
    • According to a survey by Apartment List, 30% of respondents said that they are less likely to move due to COVID 19. The report stated, “While Americans have historically moved more frequently than those in many other countries, the U.S. mobility rate has actually been declining for the past 35 years. According to the Census Bureau, over 20 percent of Americans changed homes in 1985; by 2019, that rate had been cut in half.”

    Other Real Estate News:

    • 42% of US homes are owned free and clear
    • Mortgage loan applications are up 20.1% year over year at an 11 year high.
    • There are 128 million houses in the US. 22.7 million are non-owner occupied. 6 million of those are owned by institutional investors like Blackstone. 16.7 million are owned by regular people or small investors.
    • Starbucks is changing its café’s footprints and closing about 400 locations while adding 300 new locations that do not offer dine-in options.
    • Homesnap and eCommission launched a new payment option that allows agents to purchase Homesnap products using future commissions.
    • According to HireAHelper.com the moving industry will have a revenue drop this year in a range of 12.2%-19.9% or an estimated $1.5 billion to $2.5 billion.
    • The exclusive iBuyer partnership with Offerpad and Keller Williams has ended, likely because of last week’s announcement that Offerpad will be listing and selling along with iBuying, putting them in direct competition with Keller Williams. KW will now also be working with other undisclosed investors for its iBuyer program.

    Final Thoughts:

    Coldwell Banker CEO, Ryan Gorman said, “If you’re contemplating moving, or are one of many people who are contemplating accelerating your life plan a bit, now is a moment to get your property into inventory. Get it prepared, get it priced, and get it on the market.”

    This is a great time to sell. Do not get distracted by the negative media; the best way to be part of the solution is by getting accurate information out and guiding your clients with the facts.

    Copyright 2020 by Sarah Perkins

  • Afternoon Bite 6/22/2020 (Video)

    Every Monday afternoon Amber Kovarik and I talk about what happened this week in our local real estate market.

    Today’s Takeaways:

    According to NAR before the pandemic, our housing supply was short by 5-6 million units. Housing starts are still down by 20% year over year.

    Phoenix is still in the ideal affordable range. We are at 63 and the ideal range is 60-75. The higher the number, the more affordable. For a long time, we hung out at 68 and then recently dropped to 63. 59 is considered unaffordable. What that means is based on annual household median income, in Phoenix, it is $72,500; which means that the average AZ family could afford 63% of homes that sold since the beginning of the year.

    Pre-pandemic our inventory was running about 55% below normal. Today we are 52% below normal and it is dropping daily. Pre-pandemic our demand was about 8% above normal. Today we are 4% below normal and only a month ago demand was 20% below normal. As you can see demand is significantly outpacing supply.

    According to Redfin for the week ending on June 14 new listing median asking price is nearly 12% higher than at this time last year and 2% higher than only last week.

    According to a recent Harvard study, wealthier households are spending 17% less than they were in January, while lower-income households are spending only 4% less than they were in January. The study further suggests that the wealthiest 25% of Americans are responsible for 66% of the decline in spending since the beginning of the year.

    Mortgage purchase applications increased for a 9th straight week, leading to a 75% increase since mid-April, a 20% increase year over year, and putting us at an 11 year high.

    Most loan programs are back. 600 credit scores for FHA and VA

    Down payment assistance programs. These are way better than asking for seller concessions in today’s market.

    Rates are super low. Right now about $5,000 in a sales price is equivalent to about $25 a month in payment.